
Exploring Hidden Treasures In Asian Markets With Three Promising Stocks
As global markets navigate the complexities of inflation concerns and fluctuating interest rates, Asian equities present a unique landscape with their own set of challenges and opportunities. In this dynamic environment, identifying promising stocks involves looking for companies that demonstrate resilience and potential growth in sectors poised to benefit from evolving market trends.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
Consun Pharmaceutical Group (SEHK:1681)
Simply Wall St Value Rating: ★★★★★★
Overview: Consun Pharmaceutical Group Limited, along with its subsidiaries, is engaged in the production and sale of pharmaceutical products in Mainland China, with a market capitalization of approximately HK$12.21 billion.
Operations: The primary revenue streams for Consun Pharmaceutical Group are derived from its Consun Pharmaceutical Segment, generating CN¥3.18 billion, and the Yulin Pharmaceutical Segment, contributing CN¥466.19 million.
Consun Pharmaceutical Group, a promising player in the Asian market, reported impressive earnings for the first half of 2026 with sales reaching CNY 1.78 billion and net income at CNY 595 million. The company's basic earnings per share increased to CNY 0.71 from CNY 0.59 last year, showcasing robust growth. Over the past five years, its debt-to-equity ratio improved significantly from 21.8% to just 4.3%, highlighting strong financial management. Trading at a substantial discount of approximately 71% below estimated fair value suggests potential undervaluation compared to peers, making it an intriguing prospect for investors seeking value in pharmaceuticals.
- Delve into the full analysis health report here for a deeper understanding of Consun Pharmaceutical Group.
Learn about Consun Pharmaceutical Group's historical performance.
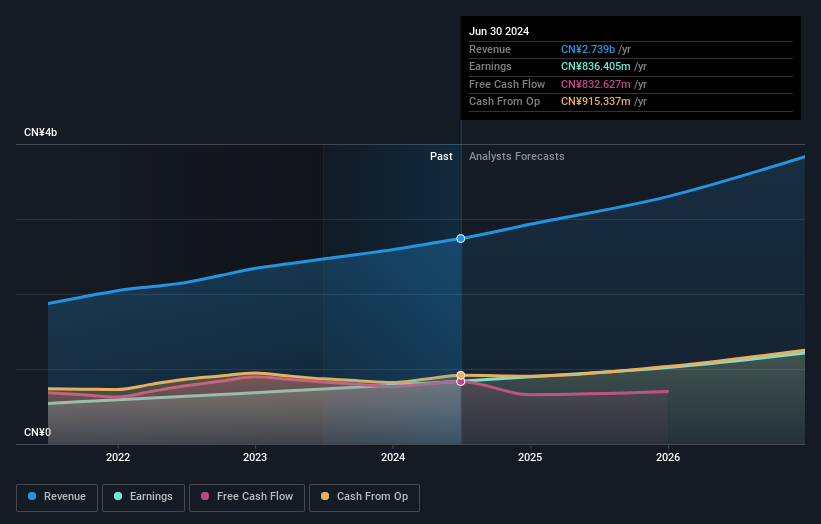
Baolingbao BiologyLtd (SZSE:002286)
Simply Wall St Value Rating: ★★★★★★
Overview: Baolingbao Biology Co., Ltd. is involved in the research, development, manufacturing, and sale of functional sugar both in China and internationally, with a market capitalization of approximately CN¥3.16 billion.
Operations: Baolingbao Biology generates revenue primarily from the agricultural and sideline food processing industry, amounting to CN¥2.85 billion.
Baolingbao Biology, a smaller player in the food industry, has been making strides with its financial health and market position. The company recently reported sales of CNY 1.49 billion for the first half of 2026, up from CNY 1.40 billion a year prior, though net income dipped to CNY 82 million from CNY 93 million. Its debt-to-equity ratio has impressively decreased from 19.7% to just 8% over five years, indicating improved financial stability. Trading at approximately 62% below estimated fair value suggests potential undervaluation while maintaining more cash than total debt underscores robust liquidity management.
- Navigate through the intricacies of Baolingbao BiologyLtd with our comprehensive health report here.
Gain insights into Baolingbao BiologyLtd's past trends and performance with our Past report.

Guangdong TCL Smart Home Appliances (SZSE:002668)
Simply Wall St Value Rating: ★★★★★★
Overview: Guangdong TCL Smart Home Appliances Co., Ltd. engages in the design, manufacture, and sale of smart home appliances with a market cap of approximately CN¥9.50 billion.
Operations: The company generates revenue primarily from the appliance industry, totaling approximately CN¥18.80 billion. It has a market capitalization of about CN¥9.50 billion.
Guangdong TCL Smart Home Appliances is making waves with its financial health and strategic position. The company reported sales of CNY 9.82 billion for the first half of 2026, a slight increase from last year's CNY 9.41 billion, although net income dipped to CNY 511 million from CNY 638 million. Trading at a significant discount to its estimated fair value by about 82%, it seems undervalued compared to peers and industry standards. With a debt-to-equity ratio improvement from 45% to around 25% over five years, TCL's financial stability is noteworthy, bolstered by more cash than total debt on hand.
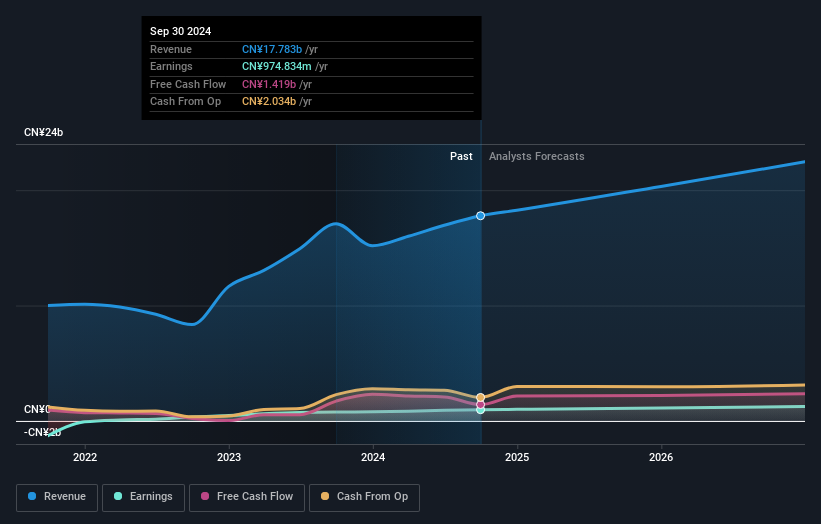
Make It Happen
- Unlock our comprehensive list of 117 Asian Undiscovered Gems With Strong Fundamentals by clicking here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com