
CTF Services (SEHK:659) Eyes Acquisition Led Growth, Is The Stock Still Undervalued?
CTF Services (SEHK:659) has just combined a full year earnings update with a lower proposed final dividend and an acquisition focused expansion plan, putting cash reserves and capital allocation in sharper focus for investors.
CTF Services has attracted fresh attention after the earnings release, with the share price rising 7.79% over the past week and 13.77% year to date, adding to a 1-year total shareholder return of 18.63% and a 5-year total shareholder return of 151.11%. This suggests momentum that has been building rather than fading.
Scan how CTF Services fits into the broader hunt for quality with the hand picked 196 high quality undervalued stocks that combine balance sheet strength with cash flow support.
After a strong run on the latest earnings and a lower cash payout that frees up more firepower for deals, the question for CTF Services now is whether the valuation still tilts the balance toward buyers.
Most Popular Narrative: 21% Undervalued
CTF Services is framed as undervalued in the most widely followed narrative, with a fair value of HK$10.80 against a last close of HK$8.51. This puts the current rally in the context of a wider rerating story built around earnings, margins and funding costs.
The implementation of a sustainable and progressive dividend policy, supported by stable cash flows, indicates a commitment to returning value to shareholders, which can lead to enhanced stock valuations and potential EPS growth.
See why 2 investors see CTF Services as 21% undervalued.
Result: Fair Value of HK$10.80 (UNDERVALUED)
Still, the CTF Services story leans heavily on Mainland visitor demand and a higher net gearing level, which could pressure earnings if conditions turn against those pillars.
Find out about the key risks to this CTF Services narrative.
Another View On CTF Services Valuation
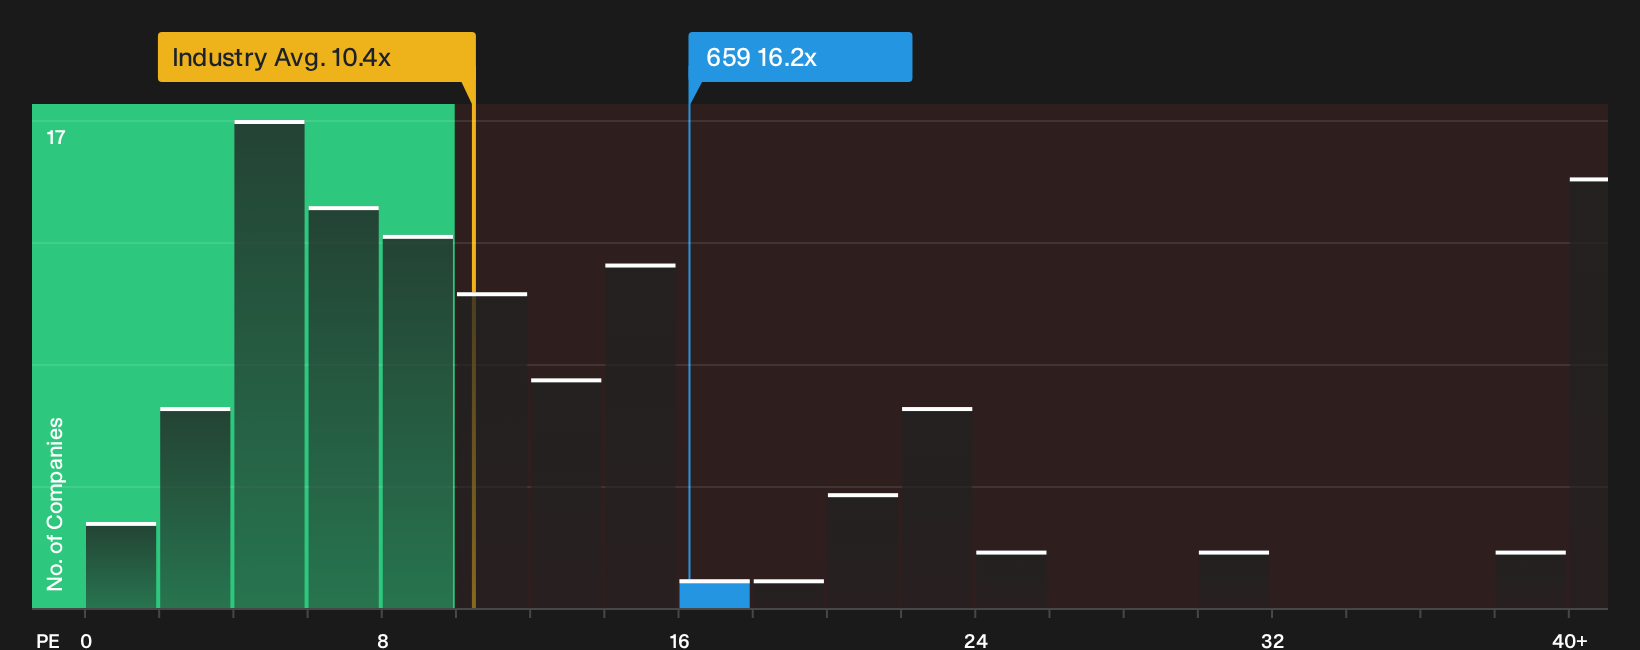
The popular story around CTF Services leans on a fair value of HK$10.80, yet the market is pricing the stock on a P/E of 16.2x versus about 10.7x for the wider Asian Industrials group and a fair ratio of 9.4x. That gap points to richer market expectations, so how comfortable are you with paying that kind of premium for this earnings profile?
Investors who prefer to anchor decisions on earnings multiples rather than narrative fair values may want to cross check the current P/E against the sector and the fair ratio before leaning too hard on the HK$10.80 figure, especially with forecast revenue growth of 1.2% a year and a forecast Return on Equity of 5.6% in three years.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the CTF Services story so far. If you want to move fast and make up your own mind, weigh its 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CTF Services?
If CTF Services is on your radar, broaden your watchlist with a few focused screeners that can surface opportunities you might otherwise miss.
- Target income potential by reviewing dependable payout candidates across sectors through the curated 164 dividend fortresses.
- Pressure test your value thesis by scanning companies that combine attractive pricing with quality fundamentals using the focused 196 high quality undervalued stocks.
- Guard against unpleasant surprises by filtering for sturdier businesses with healthier finances via the dedicated list of solid balance sheet and fundamentals (202 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com