
CEO Succession Could Be A Game Changer For AllianceBernstein Holding (AB)
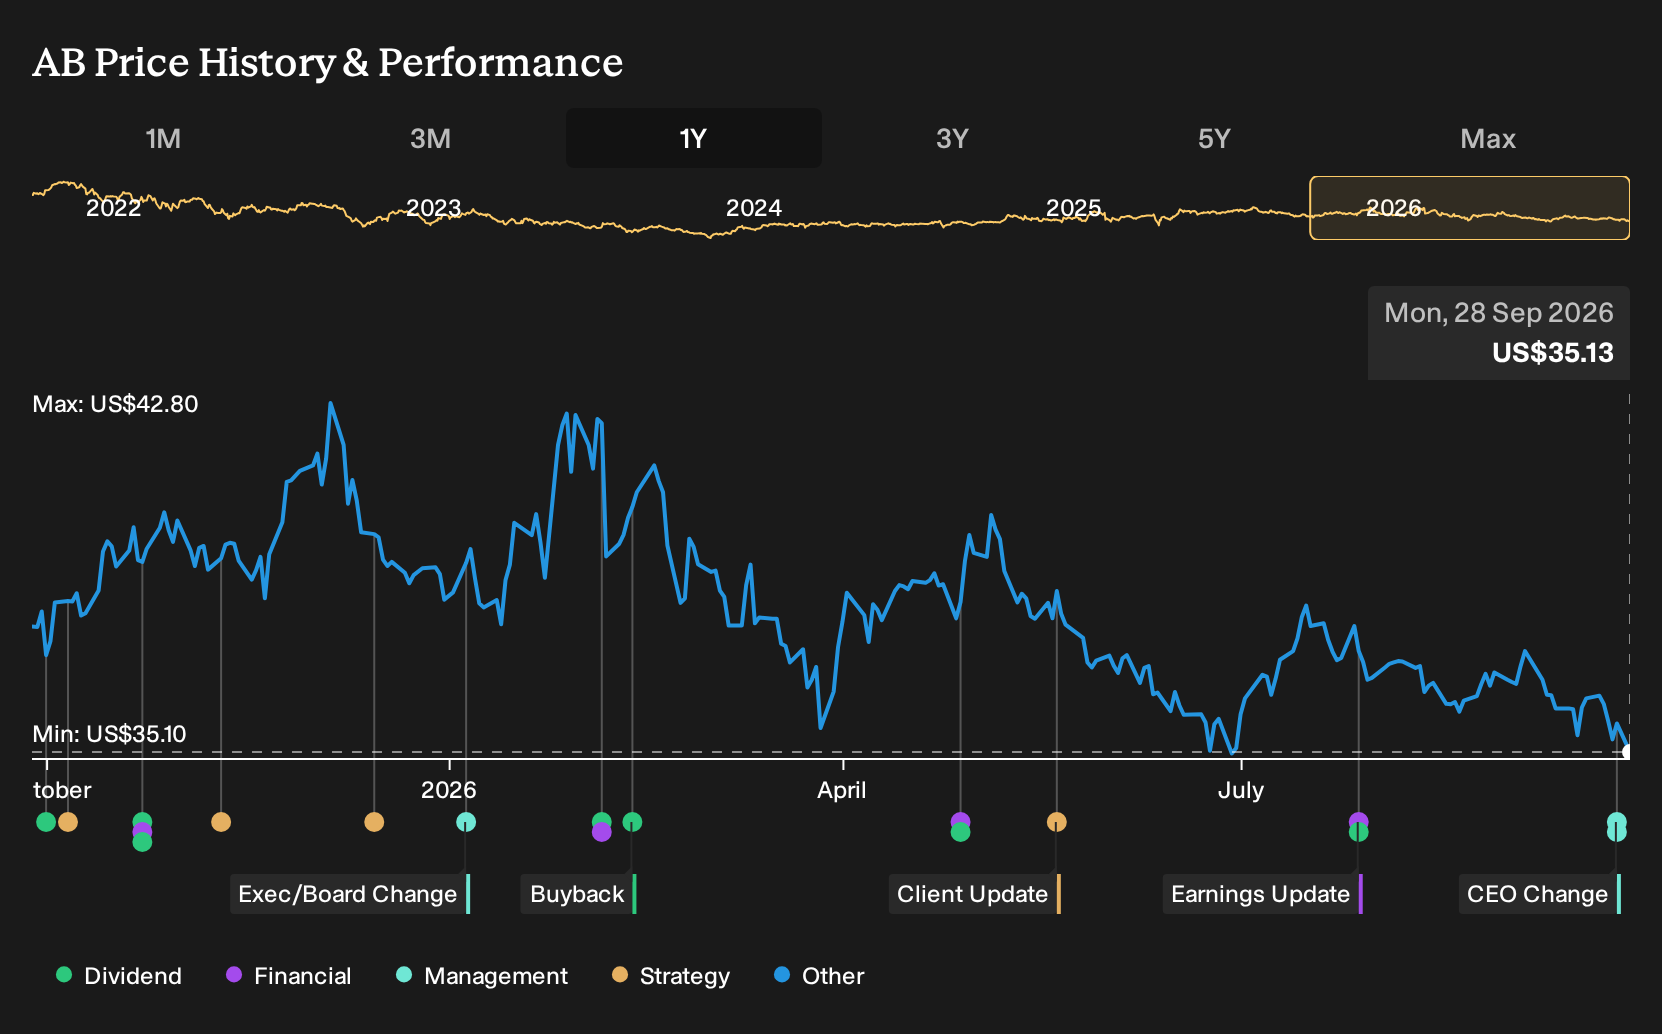
- AllianceBernstein Holding announced that long-time CEO Seth Bernstein plans to retire on March 31, 2027. Current President Onur Erzan is set to take over as Chief Executive Officer and join the Board on April 1, 2027.
- Erzan's leadership over private wealth management, private alternatives and global distribution, along with his McKinsey background, places execution on growth initiatives and product expansion at the center of this succession story.
- This development provides a new lens to evaluate how AllianceBernstein Holding's investment narrative may be influenced by Erzan's planned elevation to CEO and the Board.
Scan how AllianceBernstein Holding's leadership transition compares with other asset managers pursuing similar expansion into private markets and wealth businesses through our hand picked list of solid balance sheet and fundamentals (25 results).
AllianceBernstein Holding Investment Narrative Recap
To hold AllianceBernstein Holding, you need to believe the asset manager can turn its expanded footprint in private credit, wealth and insurance into sustained fee streams despite pressure on active equity flows and fees. The CEO succession looks orderly, so the immediate focus still sits on execution in those newer verticals rather than leadership disruption.
The near term swing factor is whether alternative and high fee strategies scale fast enough to offset any revenue impact from lower performance fees or slower institutional flows. The biggest risk remains fee and margin pressure combined with earnings that analysts currently expect to decline. This makes capital discipline and cost control critical.
The scheduled promotion of Onur Erzan to CEO and Board member in April 2027 is the key announcement tied to this story. He already runs private wealth, private alternatives and global distribution, which are exactly the areas analysts highlight as growth engines through higher fee strategies and new channels such as insurance and retirement solutions.
For catalysts, the question is whether Erzan can keep expanding active ETFs, private credit and global high net worth offerings without adding undue cost or operational complexity. Execution missteps could magnify existing risks like fee compression or slower alternative fundraising, while smooth implementation would support the current narrative around revenue growth and margin improvement.
AllianceBernstein Holding is tied to analyst expectations that revenue reaches US$6.2b and earnings total US$245.7m by 2029, with this outlook implying an earnings decrease of about US$65m from US$311.0m today.
Uncover why AllianceBernstein Holding's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster tightly between about US$38.03 and US$39.57 per unit, which leaves little room for extreme outliers. These individual retail views pre date the AllianceBernstein Holding CEO transition and private markets focus, so use them as one input and explore several alternative viewpoints before forming a view on how fee pressure, interest rate changes or slower alternative fund raising might affect future performance.
Explore 2 other AllianceBernstein Holding fair value estimates, including one that suggests up to 13% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AllianceBernstein Holding research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AllianceBernstein Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AllianceBernstein Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond AllianceBernstein Holding?
Once you have a view on AllianceBernstein Holding, it can help to line it up against other opportunities that fit different risk, income, and quality profiles using the Simply Wall St Screener.
- For investors who want quality and value in the same place, scan a curated mix of strong balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If you prefer opportunities where the market may not be paying full attention yet, focus on potential under the radar prospects by reviewing the 16 high quality undiscovered gems.
- For readers who care most about capital preservation and steadier profiles, filter for sturdier businesses with lower risk scores via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com