
Bayer (XTRA:BAYN) Stock Still Looks Reasonable After Its 84% Run
Bayer has delivered a sharp share price run over the past year, and investors are now weighing whether that move lines up with what the company is generating in sales. The question is how much of the recent momentum is already reflected in the valuation that the market is placing on its revenue base.
- The stock is up 83.8% over the past 12 months, which puts real pressure on the question of how much sales power is already priced in.
- Fresh U.S. FDA decisions around Lynkuet and KERENDIA, along with the planned sale of cancer therapy Stivarga and a €3b capital arrangement on its contraceptives unit, may reshape how investors think about Bayer's future sales mix and the cash those products can bring in.
- Your read on Bayer is one view; the desks covering it have another. See what analysts think Bayer's shares could be worth.
The issue now is whether Bayer's current share price is adequately supported by the level and quality of sales the business is generating today.
If you want to stress test the same sales based valuation question beyond Bayer, you can compare it with a wider set of companies screened by 196 high quality undervalued stocks.
Is Bayer a Bargain on Sales?
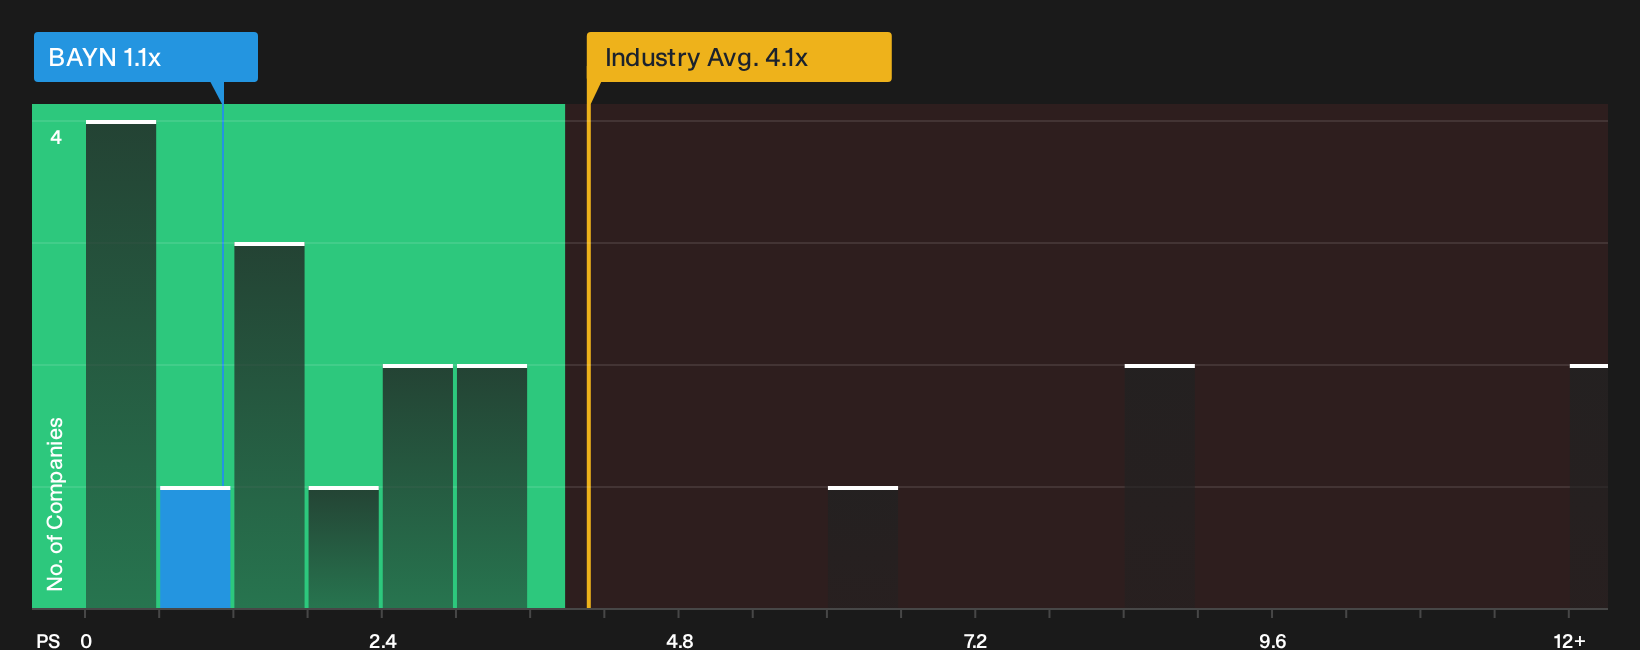
The P/S multiple suits Bayer because the current focus is on how much investors are paying for each euro of revenue while earnings remain noisy. On this yardstick, Bayer trades at about 1.1x sales, which is well below the pharmaceuticals industry average of around 2.7x and also under the broader peer group near 3.9x. Because recent FDA decisions on Lynkuet and KERENDIA have raised attention on Bayer's product portfolio, this lower revenue multiple stands out against the renewed interest in the pipeline.
The tailored fair multiple for Bayer is higher than where the stock trades, so the current 1.1x P/S screens as undervalued relative to what the model suggests could be reasonable given its scale, margins and risk profile. For an investor weighing Bayer today, the key question is whether the current revenue base and the reshaping of the portfolio justify the discount implied by this sales multiple. Explore the numbers behind Bayer's P/S valuation.
The Bayer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Bayer valuation puzzle leaves off. They spell out which expectations on future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price on Simply Wall St’s Community page. Rather than relying on a single multiple, each one lays out the key assumptions behind its idea of fair value so you can track those against Bayer’s actual results over time.
Community views on Bayer are split between a rerating opportunity and a stock that has already moved ahead of its fundamentals.
Bull case: 13% undervalued
"Progress on litigation containment, including large case settlements at low average cost, strategic provision management, and an articulated multi-pronged legal strategy with a target to largely resolve legacy glyphosate and PCB exposures by end-2026..."
Discover why this Narrative puts Bayer at 13% undervalued.
Bear case: 27% overvalued
"Os litígios relacionados ao glifosato (Roundup) continuam a ser um fardo significativo nas finanças da Bayer, com impactos que se estendem a 2026..."
Explore why this Narrative puts Bayer at 27% overvalued.
One more Bayer question that could change how you see the stock
Price to sales tells you what Bayer costs today. Analyst projections for the next few years show what expectations are already baked in and where they differ from your own view. Explore where analysts expect Bayer to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com