
Fair Isaac (FICO) Stock Could Be Cheap Following Its 112% Five Year Gain
Fair Isaac has seen its share price fall sharply in recent months, which raises a straightforward question for investors who follow FICO stock. Is the current US$840.89 price still supported by the earnings power of the business, or has the market moved ahead of what the income statement can justify?
- Over the past 5 years, Fair Isaac has delivered a total share price gain of 112.3%. This puts a lot of past optimism about its earnings strength under the microscope.
- The recent move by the Federal Housing Finance Agency to allow VantageScore to compete directly with FICO in US mortgage underwriting can influence how investors think about future credit score fee income and the durability of Fair Isaac's earnings base.
- The analysts covering Fair Isaac have run their own numbers. See what analysts think Fair Isaac's shares could be worth.
The issue now is whether Fair Isaac's current share price is adequately explained by the level and quality of the earnings it generates today.
If you want to test the same earnings question you are asking of Fair Isaac across a wider set of companies, take a look at 32 high quality undervalued stocks.
Is Fair Isaac a Bargain on Earnings?
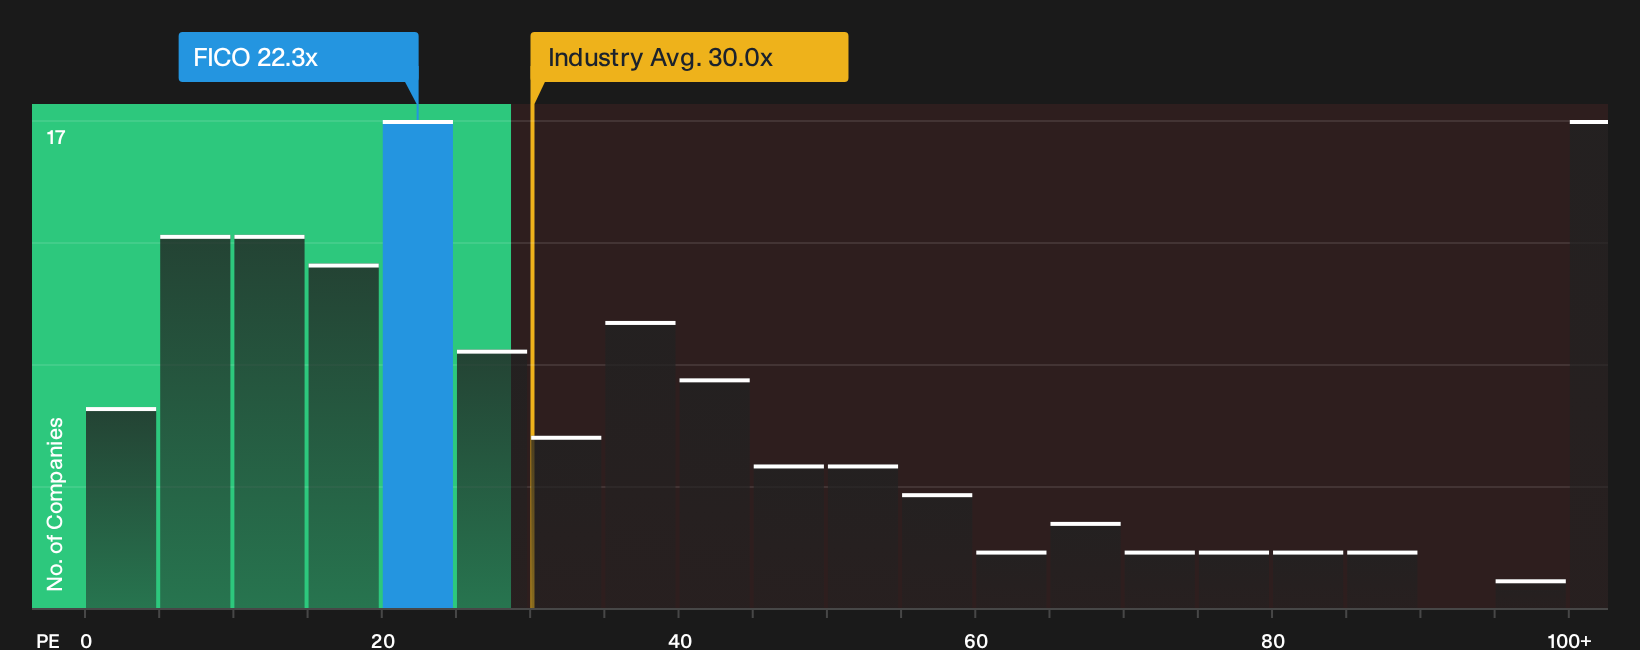
For Fair Isaac, a P/E ratio makes sense because earnings are a central part of how investors frame the credit scoring and software business. On this measure, the stock trades on roughly 22.3x earnings, which is below both the broader software sector on about 30.0x and a peer group closer to 55.2x. Because the recent Federal Housing Finance Agency decision introduces direct competition from VantageScore in US mortgage underwriting, some investors may see that lower multiple as the market baking in extra uncertainty around part of Fair Isaac's fee stream.
The Fair Ratio, which reflects what you might expect to pay for Fair Isaac given its growth profile, margins, size and risk, sits above the current P/E. That points to the shares trading at a discount to what this tailored benchmark would imply rather than at a premium. Despite the FHFA headline pressuring sentiment in the short term, the P/E still leaves the stock pricing below both peers and this Fair Ratio anchor, which places more emphasis on the underlying earning power and less on the latest news flow. Explore the numbers behind Fair Isaac's P/E valuation.
The Fair Isaac Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Fair Isaac pick up where this valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to support a meaningfully higher or lower price than today. Instead of stopping at a single ratio or model output, these scenarios describe the future those figures rely on so you can watch Fair Isaac's actual progress against that storyline over time. Narratives sit on Simply Wall St's Community page and are intended as a reference point for ongoing tracking rather than a verdict.
One of the top community narratives on Fair Isaac: 42% undervalued
"Industry-wide demand for robust, third-party analytics driven by regulatory scrutiny and risk management requirements reinforces FICO's entrenched market position and pricing power…"
Discover why this Narrative puts Fair Isaac at 42% undervalued.
For Fair Isaac, the share price is only one piece of the picture
The next question is who is actually steering Fair Isaac and how their incentives line up with shareholder outcomes, because that structure can shape everything investors care about from here. See who runs Fair Isaac and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com