
How Purell ProCare Launch At Clorox Stock Has Changed Its Investment Story
- Clorox recently launched Clorox Purell ProCare, a combined health and hygiene platform that unifies CloroxPro with the acquired GOJO to serve professional and healthcare customers through a shared sales and distributor network.
- The move consolidates brands like Clorox, Purell, Pine-Sol and Glad under one commercial structure. This could reshape how the business manages costs, product mix and long-term demand in health and hygiene channels.
- We will now look at how Clorox’s investment narrative could shift as the new Purell ProCare platform begins operating at scale.
Scan beyond Clorox and this Purell ProCare launch by reviewing a curated group of hygiene and consumer staples peers in the 30 resilient stocks with low risk scores that may offer steadier risk profiles.
Clorox Investment Narrative Recap
To own Clorox, you need to believe the health and hygiene focus, including GOJO and now Clorox Purell ProCare, can offset sluggish category trends and value-seeking shoppers. The key short term swing factor is whether integration work and ERP execution translate into steadier volumes and better product mix without disrupting service to retailers and professional customers.
The biggest operational risk still sits in cost inflation and a high dividend payout that limits room for error. Purell ProCare matters only if it helps scale contracted and repeat business enough to support margins against more than US$200 million of guided input and supply chain cost pressure in fiscal 2027.
The dividend affirmation on 24 September 2026 is the announcement that ties most directly into this story. Clorox kept its quarterly payout at US$1.25 per share even as the share price has declined and category growth is described as muted. This reinforces how central income is to the equity case.
For you, that dividend decision sharpens the trade off. Management is signaling commitment to cash returns while costs are rising and debt is not well covered by operating cash flow. Execution on Purell ProCare, ERP benefits and SG&A productivity now has to work hard to support both balance sheet resilience and that high payout ratio.
What Analysts Are Baking Into Clorox Forecasts
Clorox's narrative projects US$8.0b in revenue and US$807.6 million in earnings by 2029. This setup assumes revenue grows at 6.2% per year and that profit climbs by about US$220.6 million from US$587.0 million today to reach that 2029 consensus level.
Uncover why Clorox's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
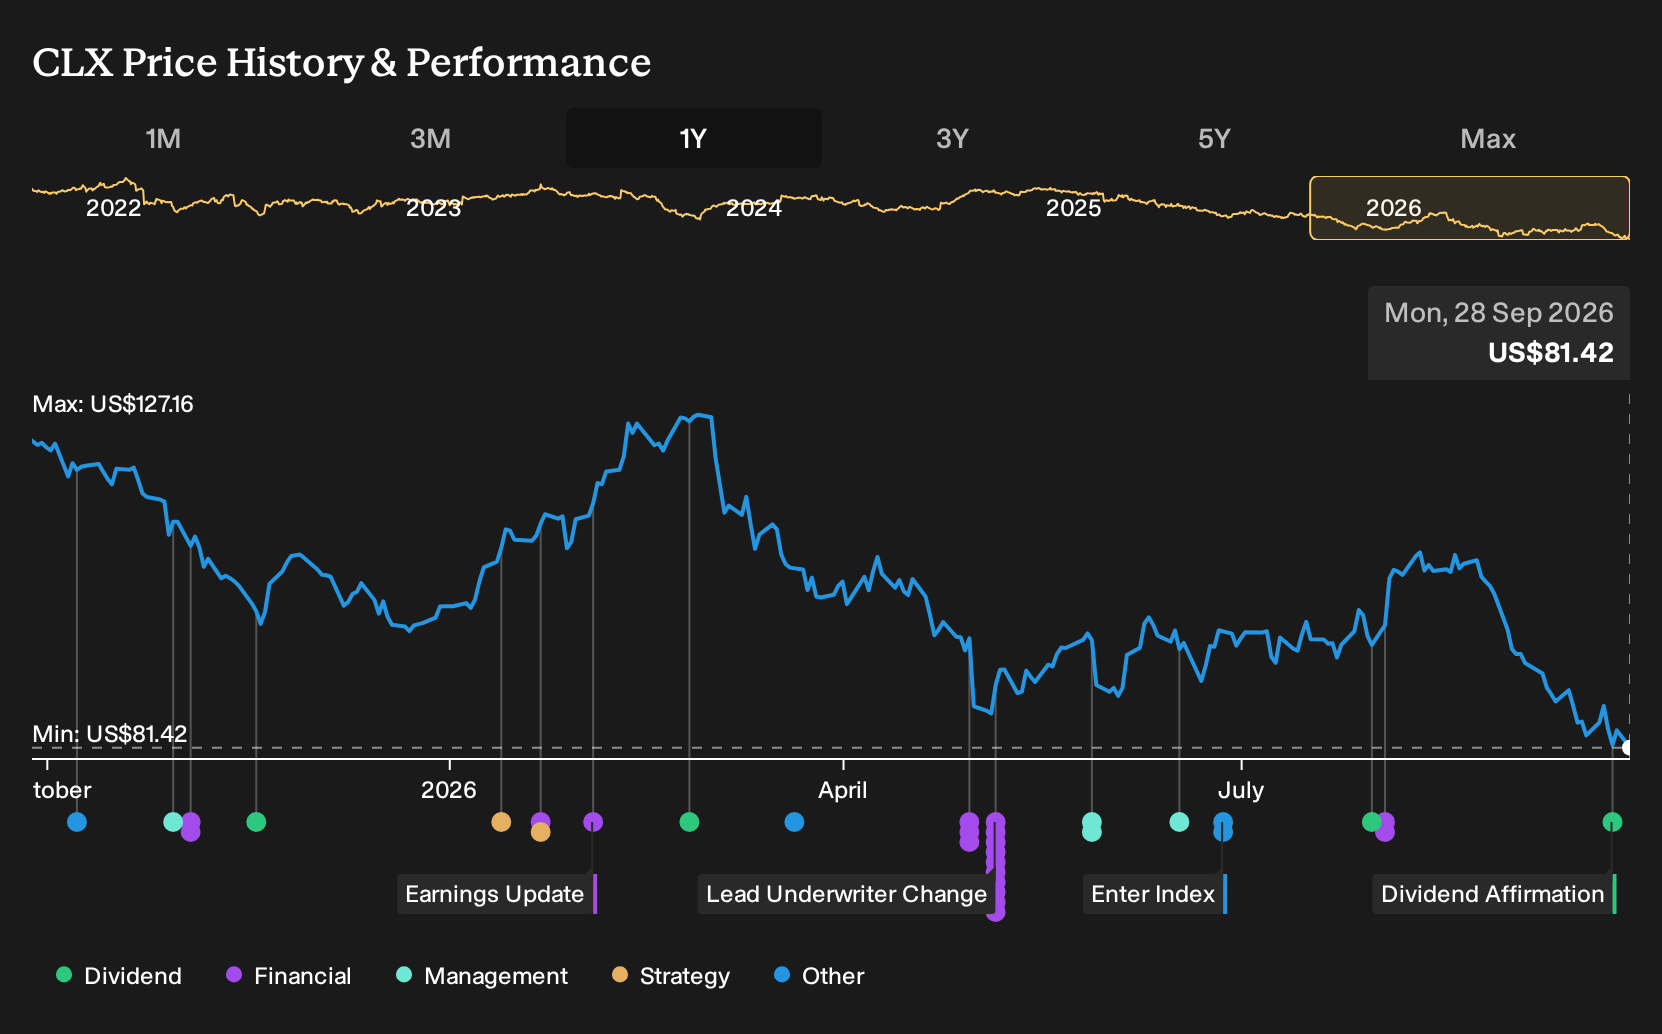
Exploring Other Perspectives
One alternate angle on Clorox focuses on a more optimistic ERP and margin story rather than cost pressure. The most bullish analysts were already penciling in revenue of about US$8.2b and earnings near US$894.7 million by 2029 before this Purell ProCare launch. That shows how sharply expectations can differ and why it can help to compare several viewpoints yourself as this new platform starts to influence the numbers.
Explore 5 other Clorox fair value estimates, including one that suggests as much as 194% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Clorox research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Clorox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Clorox's overall financial health at a glance.
Looking For More Ideas Beyond Clorox?
If the Clorox story has sharpened your thinking about risk, dividends and balance sheet pressure, it can help to widen the lens and compare it with other businesses that fit different profiles on income, quality and volatility.
The Simply Wall St Screener lets you scan for stocks that match those preferences in a few clicks, so you can weigh Clorox against alternatives that may line up better with your own goals and risk comfort.
- If capital preservation is top of mind, start with a curated set of lower risk candidates through the 30 resilient stocks with low risk scores to see which businesses may offer more resilient profiles.
- Income focused investors can zero in on companies offering higher yields by reviewing the 6 dividend fortresses that filters for payouts above 5%.
- If you are hunting for quality at a discount, compare Clorox with the 16 high quality undiscovered gems that spotlight stocks with strong fundamentals which are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com