
IDT (IDT) Could Be 7% Undervalued On Full Year 2026 Earnings And Dividend
IDT (IDT) just reported full year 2026 earnings alongside a fresh quarterly dividend declaration, giving investors new numbers on profitability, cash returns, and how the telecom and fintech operator is currently positioned.
Recent trading has been strong, with the share price up 3.11% over the last day and delivering a 37.55% year to date share price return, while a long term total shareholder return over three years of 220.28% points to momentum that has been building rather than fading.
Scan how IDT compares with other telecom and fintech plays showing strong momentum and fundamentals by checking out the hand picked 16 high quality undiscovered gems in the same space.
IDT has surged on a three year run, yet still trades below analyst targets while some models flag a premium. Is this caution sensible, or is the market mispricing the story?
Most Popular Narrative: 7% Undervalued
On the most followed valuation view, IDT screens modestly below its $75 fair value estimate, with the last close at $69.56. This puts the current rally in context rather than contradicting it.
IDT's NRS segment is launching new features and functionalities, which are expected to deepen market penetration and drive revenue growth in the independent retailer market. This is anticipated to bolster recurring revenue and adjusted EBITDA.
See why 8 investors see IDT as 7% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, the IDT story can change quickly if BOSS Money's heavy working capital needs squeeze cash flow or if acquisition related integration issues drag on margins.
Find out about the key risks to this IDT narrative.
Another View: IDT Looks Priced Rich On Earnings
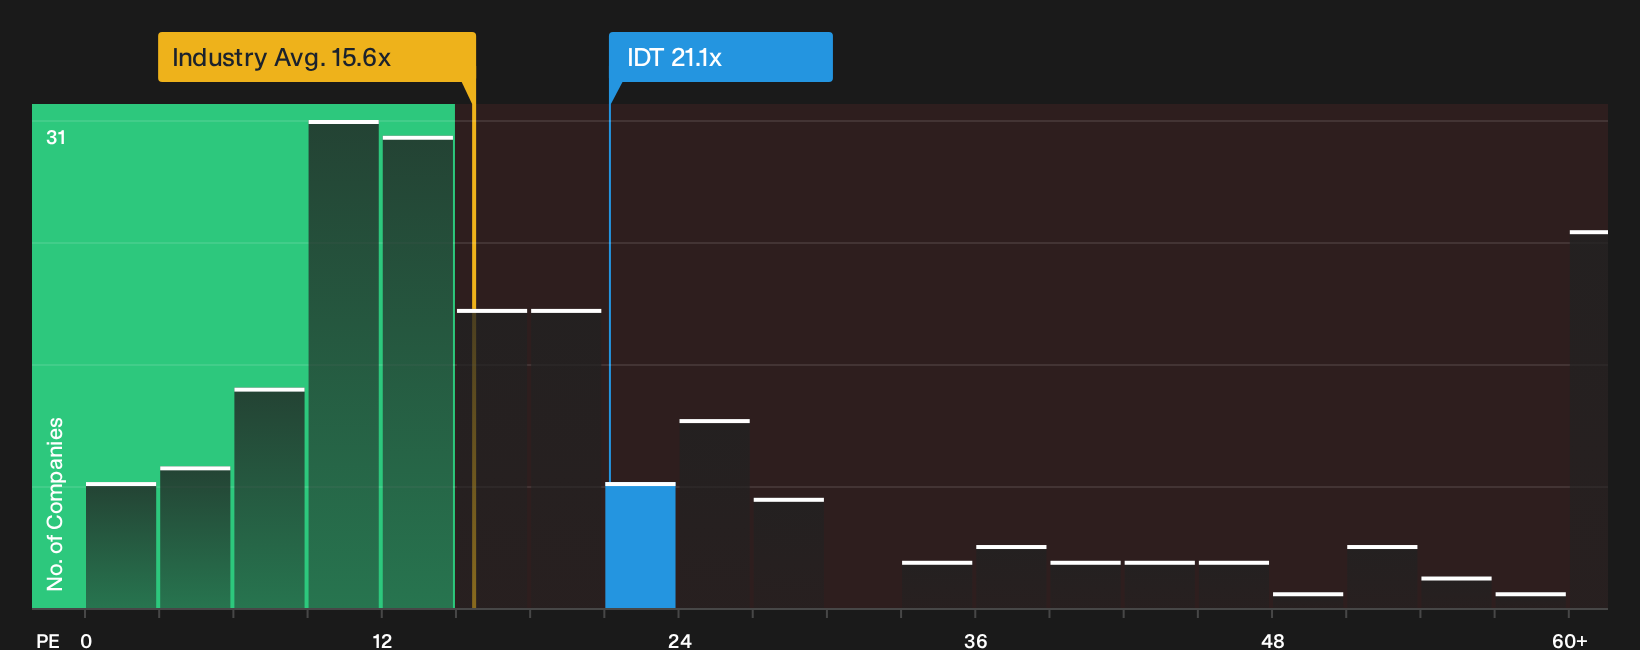
On a simple earnings lens, IDT looks expensive. The stock trades on a P/E of 21.1x, while the global telecom peer group sits at 15.6x and the fair ratio is 17.1x. That gap points to less of a bargain and more valuation risk if sentiment cools.
For a closer look at how this earnings based view lines up against detailed cash flow work, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on IDT is mixed, with solid price momentum and a valuation debate sitting alongside both flagged risks and clear upside angles. Move quickly, review the detail for yourself, and weigh the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond IDT?
If IDT has your attention, do not stop here. Broaden your watchlist now and give yourself more options when the market presents its next opening.
- Target steady compounding by scanning a curated set of reliable income plays through the 6 dividend fortresses.
- Hunt for quality at a discount by reviewing companies that combine strong fundamentals with attractive pricing using the 32 high quality undervalued stocks.
- Dial down portfolio stress by focusing on resilient businesses with robust metrics via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com