
Has Snap (SNAP) Fallen Far Enough to Be a Bargain?
Snap Inc. shares have been under sustained pressure, and that slump raises a straightforward question for investors who still follow the story: Is the current price tag on Snap stock appropriately grounded in what the business is generating in sales today and what the market expects those revenues to support over time?
- Over the past 5 years, Snap's share price has fallen 92.7%, which puts the focus squarely on whether the remaining equity value is adequately backed by its revenue base.
- The recent launch of SPECS Intelligence and high priced AR glasses aimed at enterprise use may influence how quickly Snap can grow its top line and how much additional investment those ambitions will require.
- Your read on Snap is one view; the desks covering it have another. See what analysts think Snap's shares could be worth.
The stock's next move may depend on whether Snap's current market value is well supported by its sales when measured against the Fair Ratio benchmark.
If Snap's AI and AR pivot has you rethinking how you size up this theme, it can help to compare it with other 38 AI small caps.
Is Snap a Bargain on Sales?
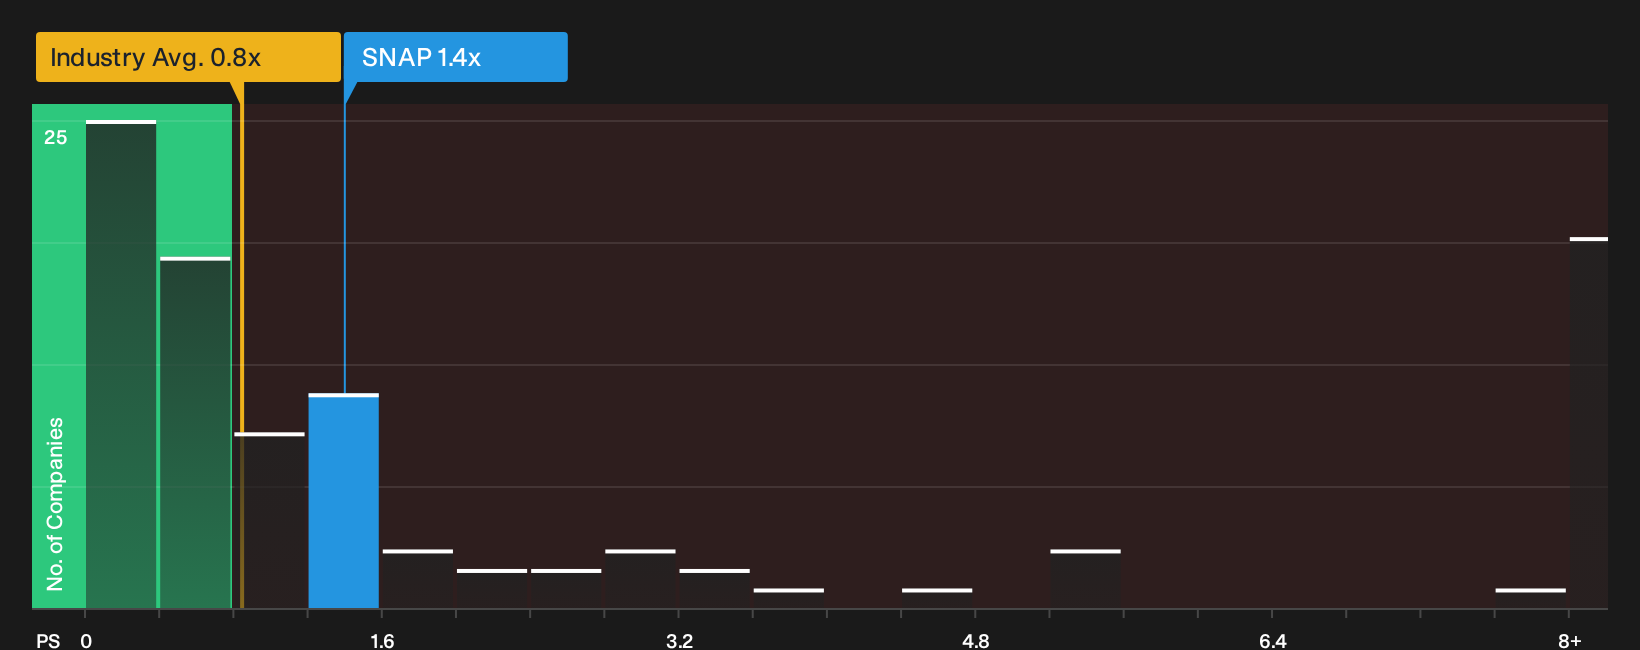
P/S is a useful lens for Snap because the business is still heavily focused on scaling its revenue base rather than producing steady earnings. On this measure, Snap trades at about 1.4x trailing sales, which is below the broader Interactive Media and Services sector average of around 0.8x and well under the peer group near 8.3x. That mix of a modest premium to the sector but a steep discount to closer peers gives a very different message depending on which yardstick you care about.
The Fair Ratio framework, which looks at what multiple might be reasonable given Snap's growth profile, margins, size and risk, points to the current 1.4x P/S as underpriced on this specific model. Because the SPECS Intelligence and AR glasses push has so far met with a cautious share price reaction, the market is not treating the new products as enough to close that gap yet. For anyone weighing Snap stock today, the question is whether the revenue the company is generating and targeting justifies even a partial move toward that implied fair multiple. Explore the numbers behind Snap's P/S valuation.
The Snap Narrative: What Would Justify Today's Price?
Snap Narratives pick up where the valuation puzzle leaves off and explain which combinations of future growth, profitability and earnings power would need to occur for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Each scenario links its number to a clear view on how Snap's revenue trajectory, margin profile and risk picture might evolve, giving you a reference point you can revisit as new information becomes available.
Community views on Snap split between those who see more upside in its AR and subscription push and those who are more cautious on the earnings multiple attached to that story.
Bull case: 29% undervalued
"Monetization progress in subscription products such as Snapchat+ and Lens+, alongside growing engagement with Spotlight and creator-driven content, is diversifying Snap's revenue base..."
Discover why this Narrative puts Snap at 29% undervalued.
Bear case: roughly fairly valued
"Snap faces the risk of long-term user stagnation or decline as younger generations shift their attention to emerging niche or decentralized platforms..."
Explore why this Narrative puts Snap at roughly fairly valued.
Snap's price is only one piece of the story
Valuation tells you what the market is paying for Snap today. However, the analyst roadmaps for revenue, margins and cash generation over the next few years show where expectations really cluster. Explore where analysts expect Snap to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com