
Entegris (ENTG) Is Back In The Spotlight, What Is Driving Attention?
Recent attention on Entegris (ENTG) follows a Zacks update that assigned the stock a Rank #2 and raised full year earnings estimates by 8.7% over the past quarter.
That ranking shift comes at a time when Entegris shares have climbed strongly this year, with a year-to-date share price return of 68.19% and a 1-year total shareholder return of 61.65%. However, the 90-day share price return has declined 16.25%, suggesting that longer-term momentum has cooled in recent months.
Scan beyond Entegris and see how it stacks up against other potential breakout candidates with the 32 high quality undervalued stocks screen.
Entegris has surged this year, then cooled sharply in the last quarter. For investors watching that pullback, the question is whether paying up now makes more sense than waiting for a cheaper shot at the same earnings story.
Most Popular Narrative: 13% Undervalued
On the most followed view of Entegris, the fair value estimate of $173.36 sits above the last close of $150.63. This frames the current pullback as a potential discount to that narrative.
Investments and leadership in advanced materials for next-generation nodes, including CMP slurries, selective etch, and deposition materials, position Entegris to capitalize on upcoming node transitions (e.g., advanced logic, 3D NAND, HBM) and increasing semiconductor complexity, supporting higher ASPs and improved gross margins. Expansion and deepening of regional manufacturing clusters in Asia is enabling customer requalification and quick recovery from trade or tariff disruptions, especially in China, directly reducing volatility in revenues and helping restore growth in these fast-growing markets.
See why 13 investors see Entegris as 13% undervalued.
The narrative builds this value case using a discount rate of 11.89% and assumes earnings growth tracks rising materials content per chip. It also acknowledges high debt levels and Asia heavy exposure as real risks that could challenge those expectations.
Result: Fair Value of $173.36 (UNDERVALUED)
Still, Entegris depends heavily on Asia-based sales and carries sizeable debt, so any trade shock or funding squeeze could quickly challenge this upbeat scenario.
Find out about the key risks to this Entegris narrative.
Another View On Entegris Using Market Ratios
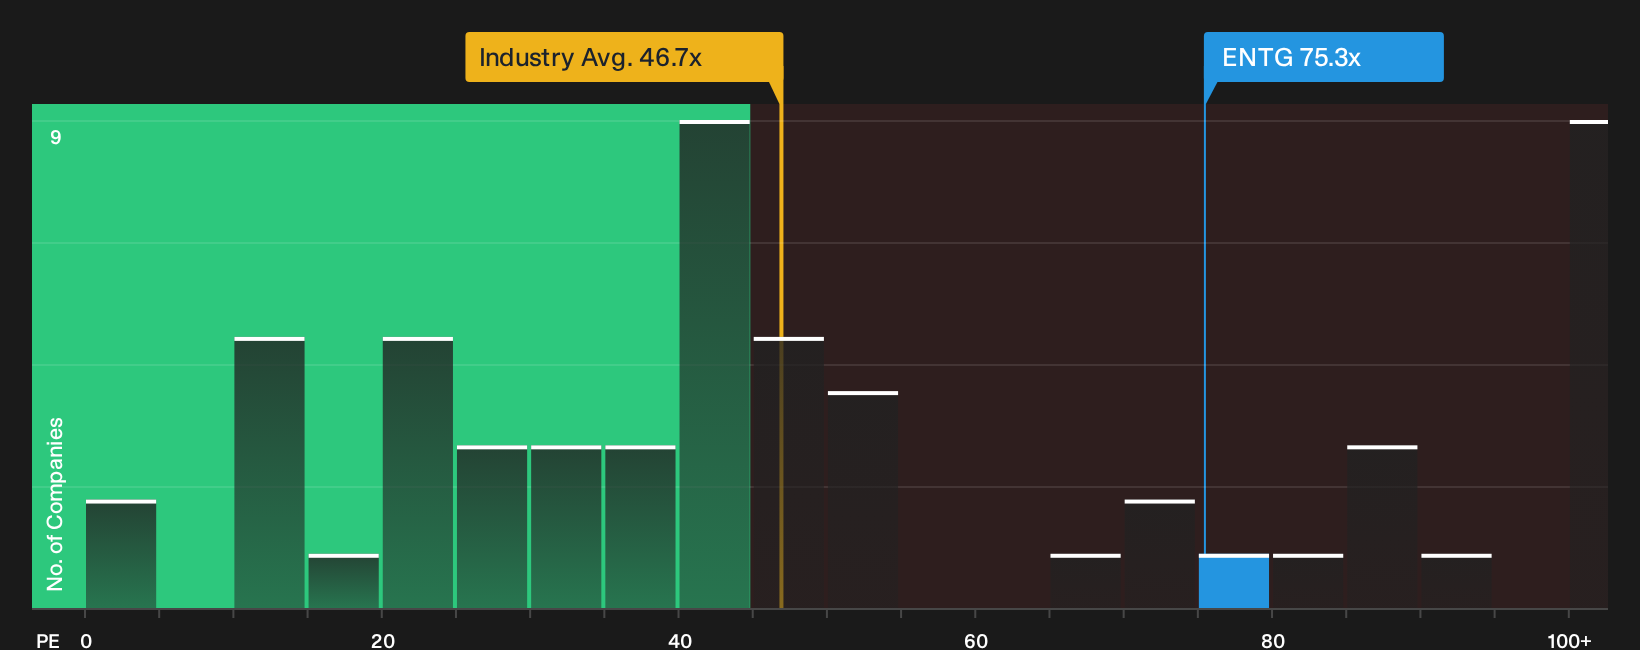
The consensus narrative frames Entegris as about 13% undervalued relative to the $173.36 fair value estimate, but the market ratio picture is tougher. At a P/E of 75.3x, the stock trades well above the US Semiconductor industry at 47.7x and its own fair ratio of 34.4x, which points to meaningful valuation risk if sentiment cools.
For investors comparing Entegris with other high multiple chip suppliers, this kind of gap is the sort of premium that can shrink quickly if growth expectations ease or sector enthusiasm fades. How comfortable are you paying more than double the fair ratio for this earnings profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Entegris is split, with enthusiasm for the growth story sitting right alongside concern about potential pitfalls. If you want to move quickly and build your own view using a balanced snapshot of both sides of the debate, take a look at the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Entegris?
If Entegris has sharpened your focus on valuation, do not stop here. Use the Simply Wall Street screener to explore additional opportunities that align with your approach.
- Target resilient progress by scanning companies with robust finances using our list of solid balance sheet and fundamentals (25 results).
- Look for potential mispriced opportunities by running the 32 high quality undervalued stocks that filters for quality and attractive valuations.
- Support your income objectives by reviewing the 6 dividend fortresses tailored to higher yielding, income focused stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com