
Is Arrowhead Pharmaceuticals (ARWR) Stock Still Reasonable After Trial Results?
Arrowhead Pharmaceuticals has been on a strong multi year run, and after a sharp recent pullback, the central issue for you is whether the current share price still lines up with what its sales can support. With fresh clinical news in cardiometabolic disease on the table, investors are again asking how much of the story is already reflected in the valuation.
- Over the past 3 years, Arrowhead Pharmaceuticals has delivered a share price gain of 149.4%, which raises the question of how much sales power is now assumed in that move.
- The recent interim data for ARO-DIMER-PA in mixed hyperlipidemia may support expectations for future revenue from Arrowhead's RNAi platform and could influence how much investors are willing to pay for each dollar of current sales.
- The analysts covering Arrowhead Pharmaceuticals have run their own numbers. See what analysts think Arrowhead Pharmaceuticals's shares could be worth.
The issue now is whether Arrowhead Pharmaceuticals' current share price is justified by its sales when judged against that Fair Ratio lens.
To put Arrowhead Pharmaceuticals' sales-based valuation in context, it helps to compare it with other businesses through 32 high quality undervalued stocks.
Is Arrowhead Pharmaceuticals Still Cheap on Sales?
P/S suits Arrowhead Pharmaceuticals because the company is still built around future sales potential from its RNAi pipeline rather than current profits.
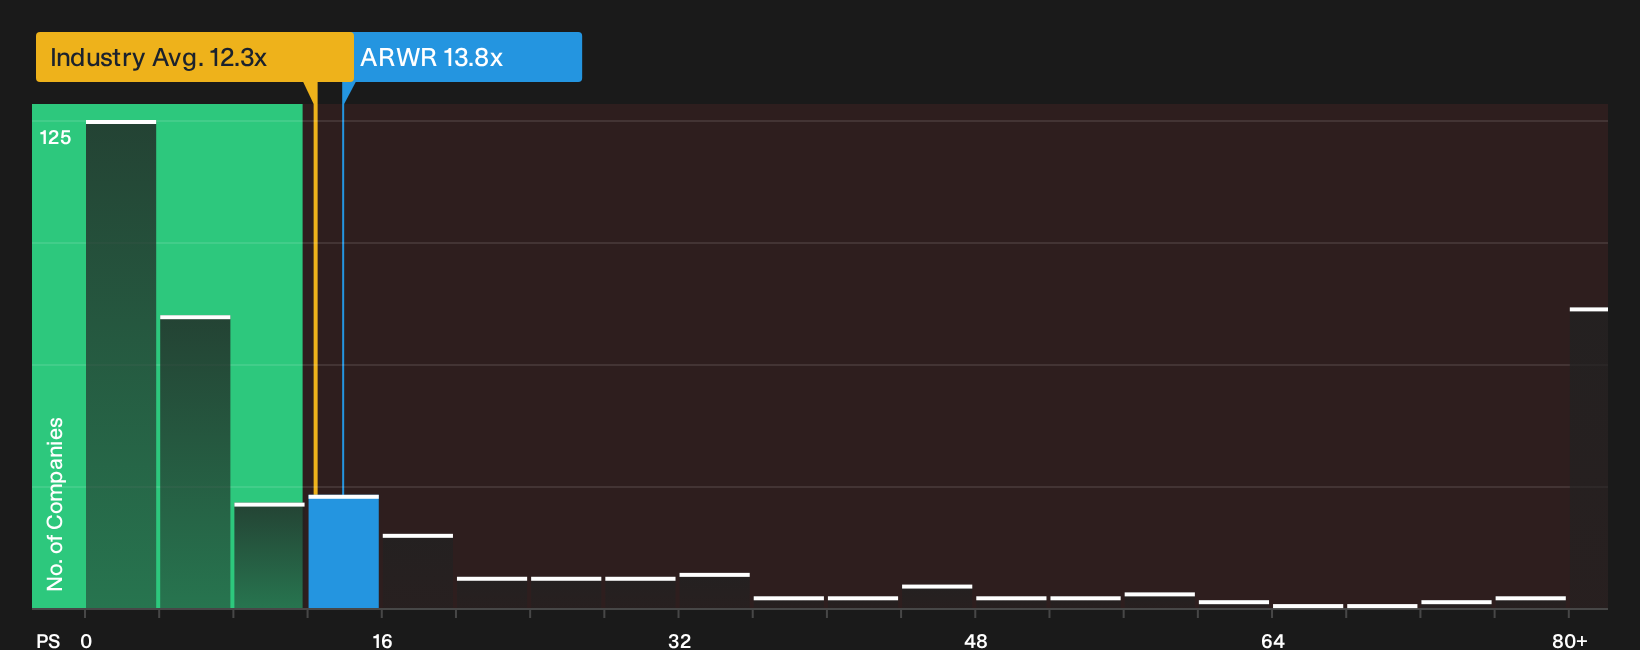
The stock currently trades on a P/S of 13.8x, which is slightly above the biotech industry average of 12.3x and a bit below the 15.9x peer group average. Against the Fair Ratio, which estimates the multiple you might expect given Arrowhead Pharmaceuticals' mix of growth opportunities, margins, size and risk, the present P/S points to the shares trading at a discount on this framework. Because the recent ARO-DIMER-PA data has already sharpened attention on cardiometabolic prospects, that gap suggests the market is not fully charging a premium for the RNAi platform yet. Explore the numbers behind Arrowhead Pharmaceuticals's P/S valuation.
The Arrowhead Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Arrowhead Pharmaceuticals sit on the Community page and pick up where the valuation question leaves off. They spell out which future paths for growth, profitability and earnings would need to play out for the stock to look meaningfully under or overvalued relative to today's price. Each view links its number to a clear stance on how Arrowhead Pharmaceuticals' expansion prospects, margins and risk profile might shift, giving you something concrete to compare as fresh information arrives.
One of the top community narratives on Arrowhead Pharmaceuticals: 41% undervalued
"Multiple large pharma collaborations and milestone generating partnerships provide non dilutive capital, revenue diversity, and stability independent of volatile equity markets..."
Discover why this Narrative puts Arrowhead Pharmaceuticals at 41% undervalued.
One more check on Arrowhead Pharmaceuticals belongs alongside the price tag
The drug pipeline and P/S ratio only tell part of the story, because the people steering Arrowhead Pharmaceuticals and the way they are rewarded can tilt risk and upside in very different ways. See who runs Arrowhead Pharmaceuticals and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com