
New Tier 2 Bond Might Change The Case For Investing In Gjensidige Forsikring (OB:GJF)
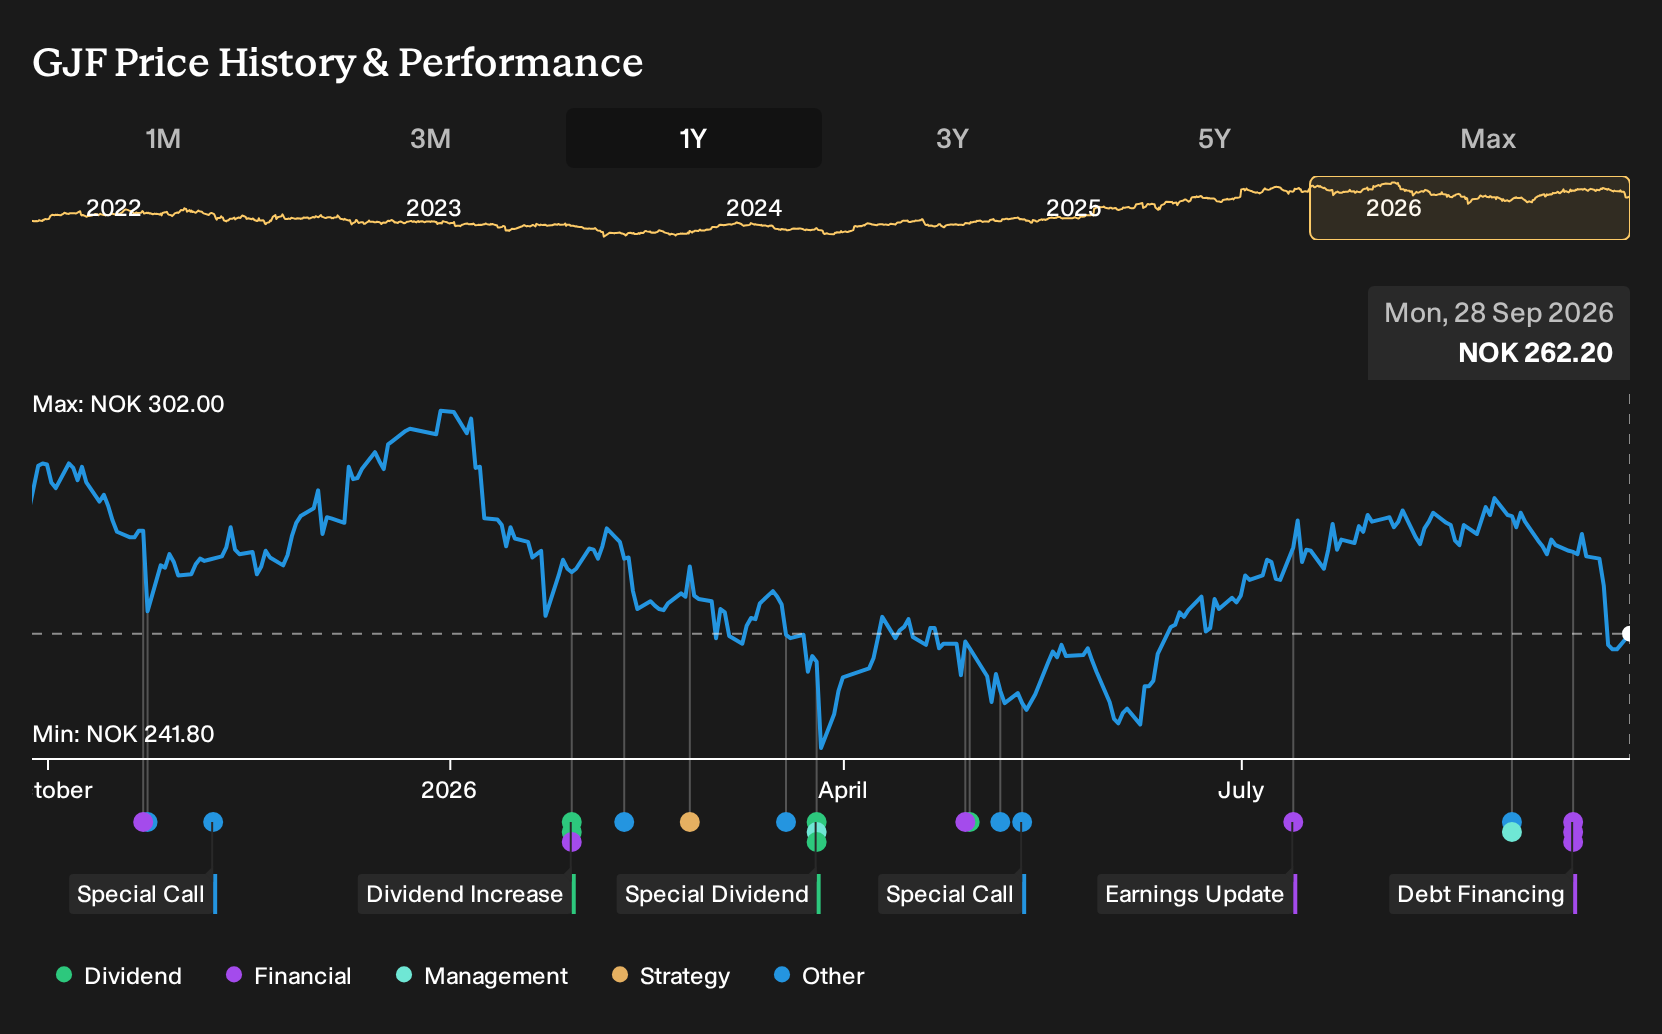
- Gjensidige Forsikring has issued a NOK 1,000 million Solvency II compliant subordinated Tier 2 bond with a 30 year tenor, a floating 3 month NIBOR + 1.10% coupon, an expected BBB+ rating, and plans to list it on Euronext Oslo Børs while redeeming a NOK 1,200 million bond in October 2026.
- The move reshapes Gjensidige Forsikring’s capital mix by swapping one long dated subordinated bond for another. This affects funding costs, regulatory capital flexibility, and how comfortably the insurer can support its broader insurance and digital investment plans.
- We will look at how Gjensidige Forsikring’s investment narrative is affected by this new Tier 2 issuance and the planned redemption of the existing bond.
Gjensidige Forsikring Investment Narrative Recap
To own Gjensidige Forsikring, you need to be comfortable with a fairly mature insurer that leans on pricing discipline, cost control, and digitalisation rather than explosive top line expansion. The short term story still hinges on whether pricing in Norwegian property and motor, plus fixes in Denmark, can show up cleanly in earnings despite weather volatility and large loss risk.
The new Solvency II compliant Tier 2 bond and 2026 redemption do not look like game changers for that operating story. They sit more in the background. The bigger near term risk remains pressure on margins from storms, regulatory scrutiny on pricing, and any wobble in customer retention after recent premium increases.
The standout announcement around this event is the NOK 1,000 million subordinated Tier 2 issue with a 30 year tenor and first call after 5.5 years. For a holder of Gjensidige Forsikring, this matters because it underpins regulatory capital while the group pushes pricing measures, digital claims tools, and integration of assets such as BuySure.
Swapping into this new Tier 2 while calling the NOK 1,200 million bond in October 2026 keeps subordinated funding available as the insurer reshapes its footprint, including the pending Baltic exit and focus on Nordic lines. Execution risk sits in how well management balances funding costs, a relatively high P/E, and a dividend that is not fully covered by free cash flow.
Gjensidige Forsikring's current earnings are NOK 6.5b and analysts project revenues of NOK 51.3b and earnings of NOK 9.3b by 2029, which implies 3.1% yearly revenue growth and an earnings increase of NOK 2.8b from today.
Uncover how Gjensidige Forsikring's fair value indicates a 10% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate angle on Gjensidige Forsikring focuses on digital automation as the real swing factor. The most optimistic analysts were already modelling revenues of NOK 54.6b and earnings of NOK 10.2b by 2029 before this Tier 2 move. You can treat those pre news forecasts as a ceiling that might shift again once funding costs and capital flexibility are reassessed.
Explore 3 other Gjensidige Forsikring fair value estimates, including an estimate that indicates up to 73% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Gjensidige Forsikring research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Gjensidige Forsikring. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gjensidige Forsikring's overall financial health at a glance.
Looking for more Gjensidige Forsikring style investment ideas?
If you like how Gjensidige Forsikring is working to keep its capital structure steady while still funding long term projects, it can be useful to scan for other businesses that balance resilience with growth plans using the Simply Wall St Screener.
- For investors who want a defensive tilt with an income angle, check out opportunities offering reliable yield profiles through the 165 dividend fortresses.
- If capital preservation and balance sheet strength sit at the top of your checklist, start with the list of solid balance sheet and fundamentals (203 results) to focus on companies with sturdier financial foundations.
- Those aiming to uncover future leaders before they become widely followed can begin with the 618 high quality undiscovered gems to see which smaller stocks already show strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com