
Are Tesla (TSLA) Deliveries And AI Spending Raising Fresh Investor Concerns?
- Tesla (NasdaqGS:TSLA) faces investor focus ahead of its upcoming Q3 delivery update, with expectations now pointing to a year-over-year decline.
- Delayed high profile launches, including the long discussed Roadster relaunch, are drawing fresh attention to Tesla's product rollout timing.
- Rising bond yields are raising questions over future AI and technology spending plans for Tesla and its large cap peer group.
- The shift toward weaker Q3 deliveries and tighter financing conditions sits against broader pressures our research has identified for Tesla. We have also flagged 1 other big win for Tesla.
Rising funding costs and AI investment demands now shape a wider story that points directly to 87 AI infrastructure stocks.
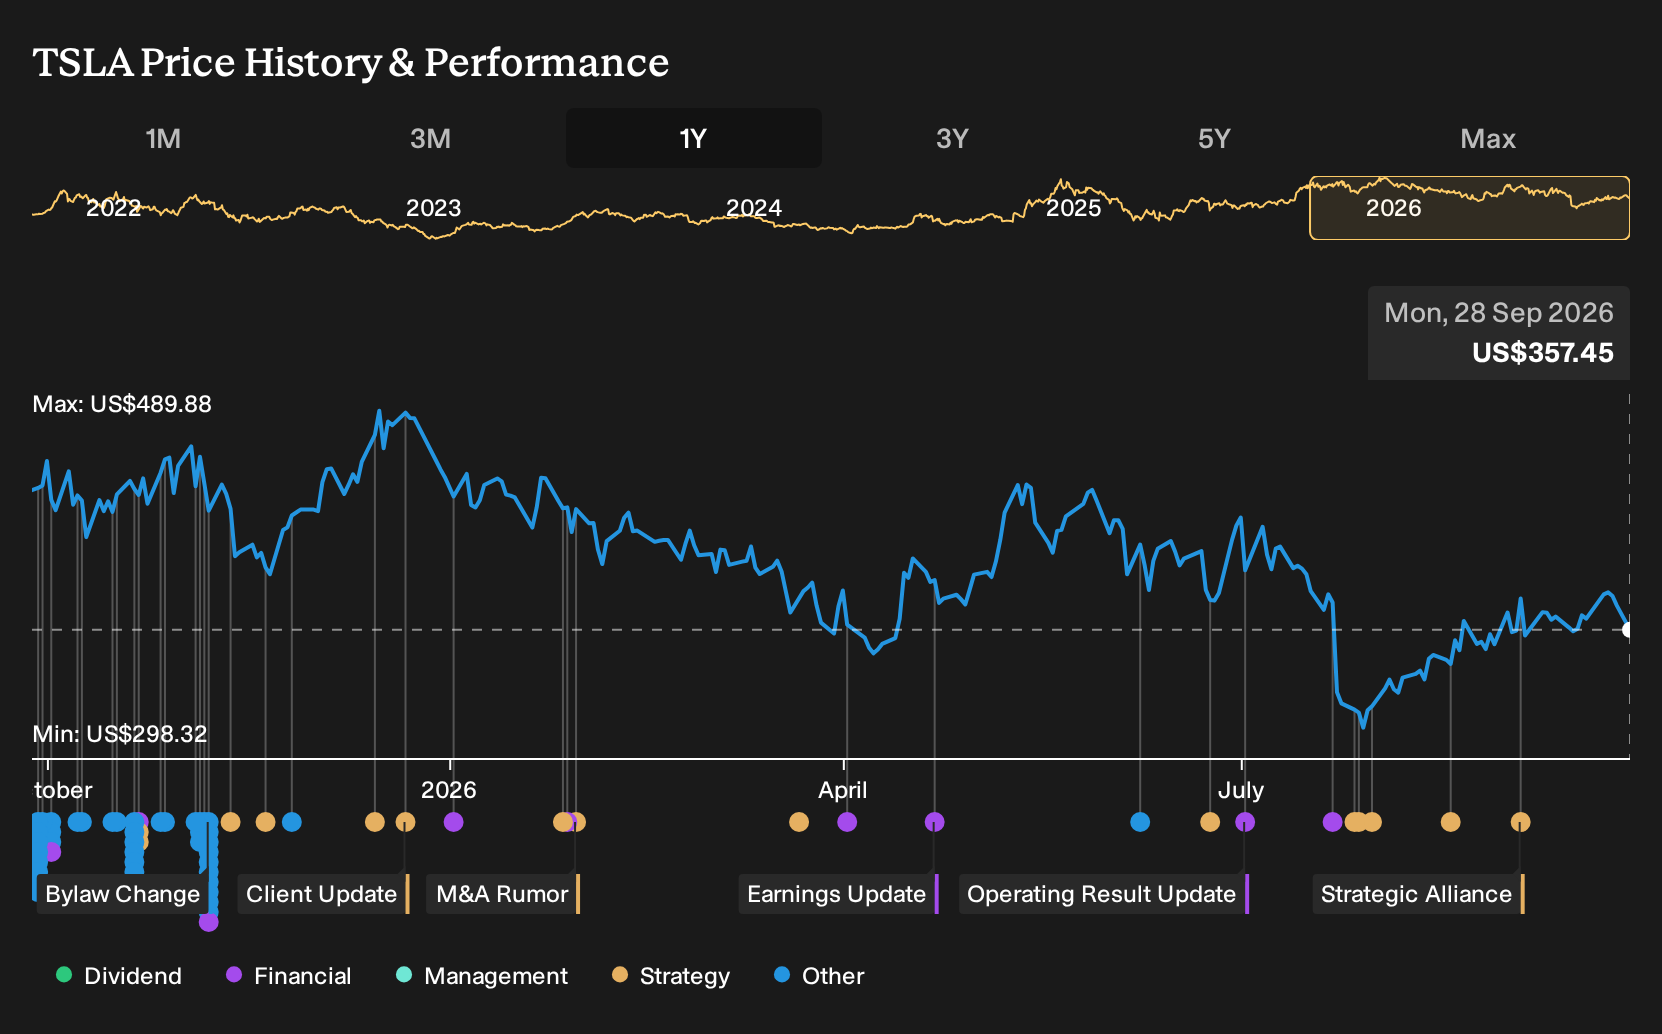
Tesla designs and sells electric vehicles as well as energy generation and storage systems across the US, China, and other markets. As a result, any pressure on funding and executive focus filters directly into how aggressively it can pursue new models and AI heavy capabilities in those segments.
See which insiders are buying and selling Tesla following this latest news.
For Tesla investors, weaker deliveries question the timing of the autonomy and energy story
This delivery wobble does not rewrite Tesla’s long term Narrative, but it does shift the emphasis. Softer Q3 volume and high profile launch delays put more weight on the execution risks already flagged around slow product ramps and elevated spending, rather than on the bullish catalyst of faster FSD and robotaxi monetisation. Rising bond yields also speak directly to the Narrative’s concern about high capex and AI investment dampening free cash flow, even as analysts still model earnings growing strongly and margins improving over time.
See how these catalysts shape Tesla's path to a $390 fair value.
The key tell from here is simple. Watch the upcoming Q3 delivery report and subsequent commentary on 2027 capex and AI outlays, especially whether management reins in planned US$9b plus annual spending or doubles down. A clear shift either way would go a long way to confirming whether this is a temporary delivery air pocket or early evidence that funding costs are starting to bite into Tesla’s autonomy and energy expansion plans.
Add Tesla to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com