
Pennant Group (PNTG), Why Is This Fresh Development Drawing Attention?
Pennant Group’s real estate move at Mainplace
Pennant Group (PNTG) has shifted from tenant to owner at Mainplace Senior Living in Orange, California, buying the property it has operated under a triple net lease since 2019.
The Mainplace acquisition comes at a time when Pennant Group’s recent momentum has been strong, with a 30 day share price return of 10.30% and a year to date share price return of 46.96%, contributing to a 1 year total shareholder return of 62.43%.
Scan for other healthcare operators pursuing real estate ownership strategies similar to Pennant Group’s recent move by running the curated list of solid balance sheet and fundamentals (25 results).
Pennant Group now owns a real asset it previously rented, and the share price has already moved significantly on that development. The key question for investors is whether the current valuation fully reflects this change or still leaves meaningful upside potential.
Most Popular Narrative: 11.7% Undervalued
Pennant Group’s most followed valuation narrative pegs fair value at $46.33 per share, above the latest close of $40.90. This frames the Mainplace real estate move within a broader upside case built on operations, acquisitions and efficiency.
The accelerating demographic shift of an aging U.S. population is leading to rising demand for home health, hospice, and senior living services, as evidenced by Pennant's strong organic and acquisition-driven volume growth and robust occupancy/pricing trends in senior living. This ongoing demographic wave is likely to continue expanding Pennant's addressable market, supporting durable, long-term revenue growth.
See why 6 investors see Pennant Group as 12% undervalued.
The narrative uses a 7.35% discount rate and assumes Pennant Group reaches about $1.4b of revenue and $79.2m of earnings by 2029, supported by an expected profit margin of roughly 5.6% and a future P/E of around 26x. Those inputs, together with analyst expectations for earnings growth of 28.2% per year over the next few years, underpin the view that the current share price trades at an 11.7% discount to the fair value estimate.
Investors weighing the Mainplace acquisition alongside this framework can compare their own assumptions on Medicare reimbursement risk, labor costs and integration of recent hospice and home health deals with the narrative’s projections to decide whether that 11.7% gap feels sufficient given Pennant Group’s capital intensity, high debt level and reliance on higher risk borrowing.
Result: Fair Value of $46.33 (UNDERVALUED)
Still, that upside story leans heavily on Medicare and Medicaid reimbursement remaining supportive and on Pennant Group successfully absorbing recent acquisitions without costly integration missteps.
Find out about the key risks to this Pennant Group narrative.
Another View: Pennant Group On A Richer Earnings Multiple
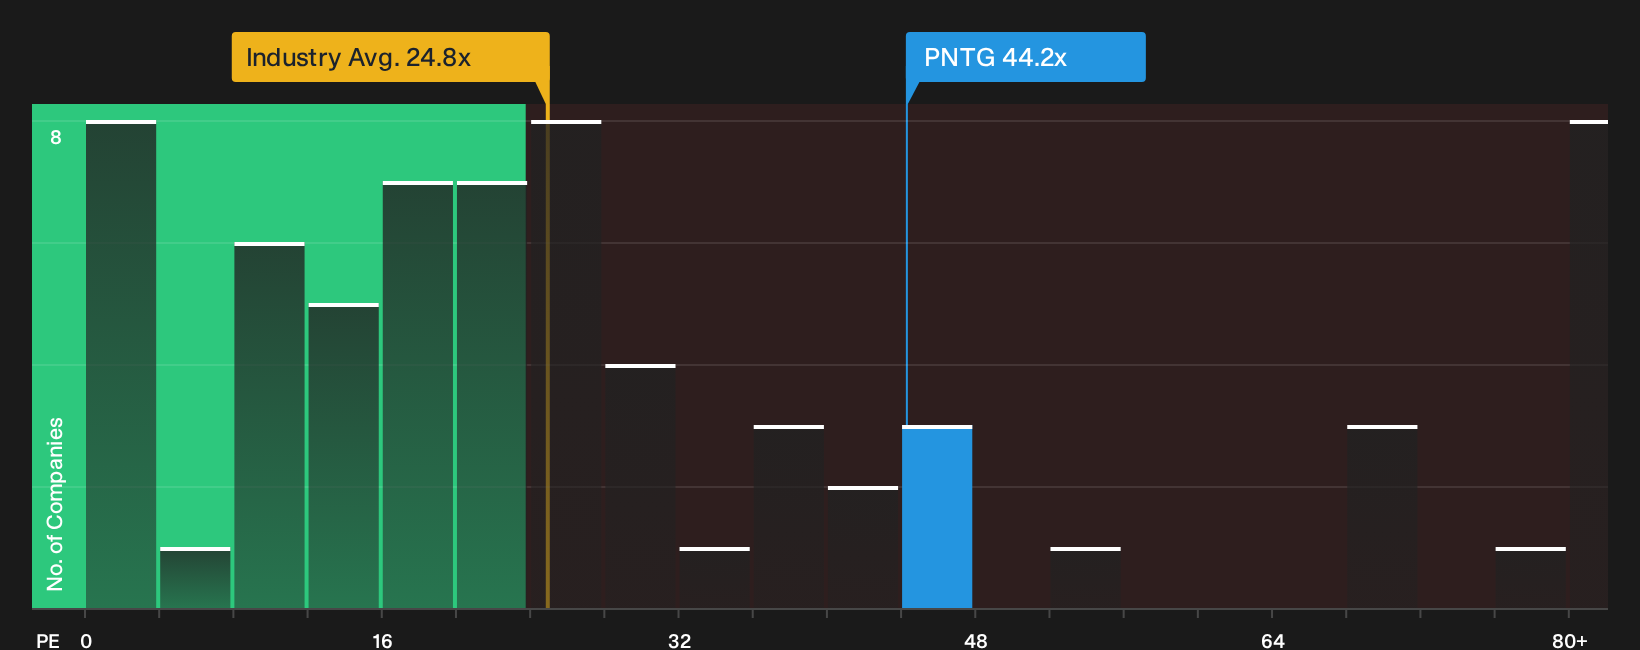
Pennant Group might appear undervalued based on a narrative fair value of $46.33, but the current P/E of 44.2x tells a different story. That is well above the US Healthcare sector at 24.3x and ahead of the 29.9x fair ratio that the market could eventually trend toward.
If the share price drifted closer to that fair ratio, investors would be paying a lower earnings multiple for the same business, which would ease valuation risk. The open question is whether Pennant Group’s growth and execution justify staying on this higher rung of the P/E ladder.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Pennant Group’s valuation and risk-reward profile call for your own judgment. Move quickly and weigh both sides by reviewing the 3 key rewards and 1 important warning sign.
Looking for more Pennant Group style investment ideas?
Do not stop with Pennant Group. Use the Simply Wall Street Screener to quickly surface other opportunities that might suit your risk tolerance and return goals.
- Spot underpriced potential by scanning a curated set of quality opportunities through the 32 high quality undervalued stocks.
- Strengthen your income stream by focusing on resilient payers using the 6 dividend fortresses.
- Prioritize resilience over drama by filtering for steadier candidates with the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com