
Omnicom Group (OMC) Could Be 26% Undervalued Following Gartner Recognition
Gartner recognition puts Omnicom Group stock back in focus
Omnicom Group (OMC) just secured top rankings across all categories in Gartner’s 2026 Critical Capabilities report and was named a Leader in the latest Magic Quadrant for global digital marketing agencies.
The research firm highlighted Omnicom’s AI powered Omni platform, which connects data, identity, activation and measurement, a setup that may influence how investors think about the company’s positioning in large scale digital marketing work.
Despite the Gartner recognition, Omnicom Group’s 1 month share price return is down about 15%, even though the 3 month move is still up just over 3%. The 1 year total shareholder return is roughly 1% lower, which keeps the longer track record modest rather than weak.
Scan how Omnicom Group’s AI driven marketing focus compares with other listed players by checking hand picked 37 profitable AI stocks that aren't just burning cash in the same broad theme.
Omnicom Group just paired fresh Gartner praise with a share price that dropped about 15% over the past month. Is that slide about business risk, or did sentiment simply swing too far?
Most Popular Narrative: 26% Undervalued
On Simply Wall St’s most followed narrative, Omnicom Group screens as undervalued, with a fair value of $102 against a last close of $75.10. This puts the recent sell off in tension with a thesis built around integration, margins and capital returns.
The expanded cost reduction and portfolio pruning program, which now targets disposals of about US$3.5b to US$3.6b of largely lower growth revenue and gross cost synergies of US$1.5b by mid 2028, is designed to support higher Core Operations margins and EBITA growth as remaining businesses scale.
See why 43 investors see Omnicom Group as 26% undervalued.
Result: Fair Value of $102 (UNDERVALUED)
Still, the Omnicom Group story could be knocked off course if higher interest costs bite harder than expected or if weak regions fail to recover.
Find out about the key risks to this Omnicom Group narrative.
Another View: Omnicom Group looks pricey on earnings
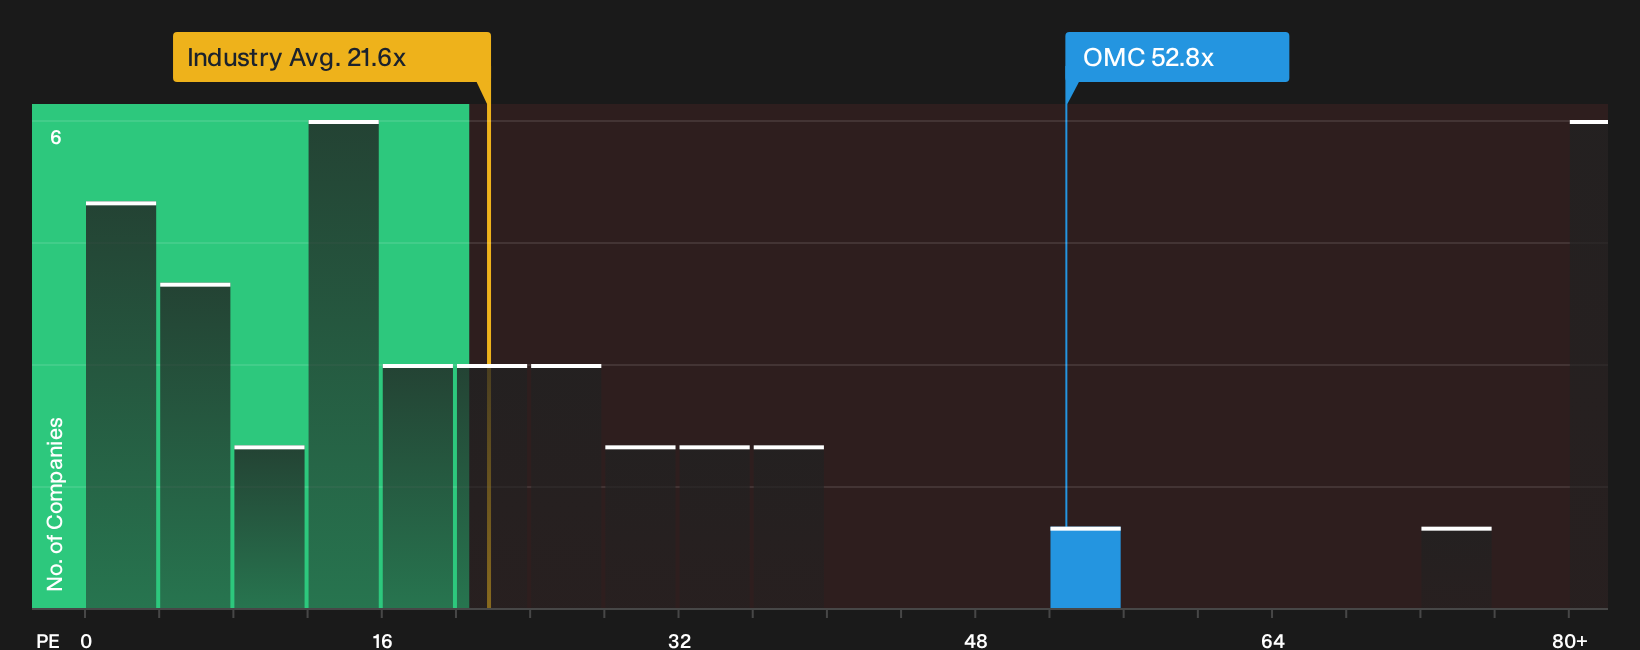
The fair value story for Omnicom Group leans on future cash flows, yet the current P/E of 52.8x is far above the US Media industry at 21.9x, peers at 33x and even its own fair ratio of 28.3x. That kind of gap can matter. Is the market simply paying up too early?
See what the numbers say about this price in more depth with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can be uncomfortable, which is exactly why Omnicom Group deserves a closer look before the next move gets away from you. Weigh the upside against the risks yourself by reviewing the 2 key rewards and 5 important warning signs
Looking for more investment ideas beyond Omnicom Group?
If Omnicom Group has you rethinking your watchlist, do not stop there. Fresh ideas often come from comparing it with completely different opportunities.
- Spot potential mispricings early by scanning a curated pool of companies that look cheap relative to their fundamentals with the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused set of higher yielding payers through the 6 dividend fortresses.
- Reduce portfolio stress by filtering for businesses with healthier debt profiles and sturdier finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com