
High Insider Ownership Growth Companies To Watch In September 2026
In the last week, the United States market has experienced a 1.5% decline, although it has risen by 13% over the past year with earnings forecasted to grow by 18% annually. In this context of fluctuating performance and optimistic growth projections, companies with high insider ownership can be particularly compelling as they often indicate strong alignment between management and shareholder interests.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Uxin (UXIN) | 34.3% | 72.9% |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 14.4% | 56.4% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Dave (DAVE) | 16.7% | 23.6% |
| Carlyle Group (CG) | 27.4% | 22% |
| Almonty Industries (ALM) | 10.8% | 37.4% |
Here's a peek at a few of the choices from the screener.
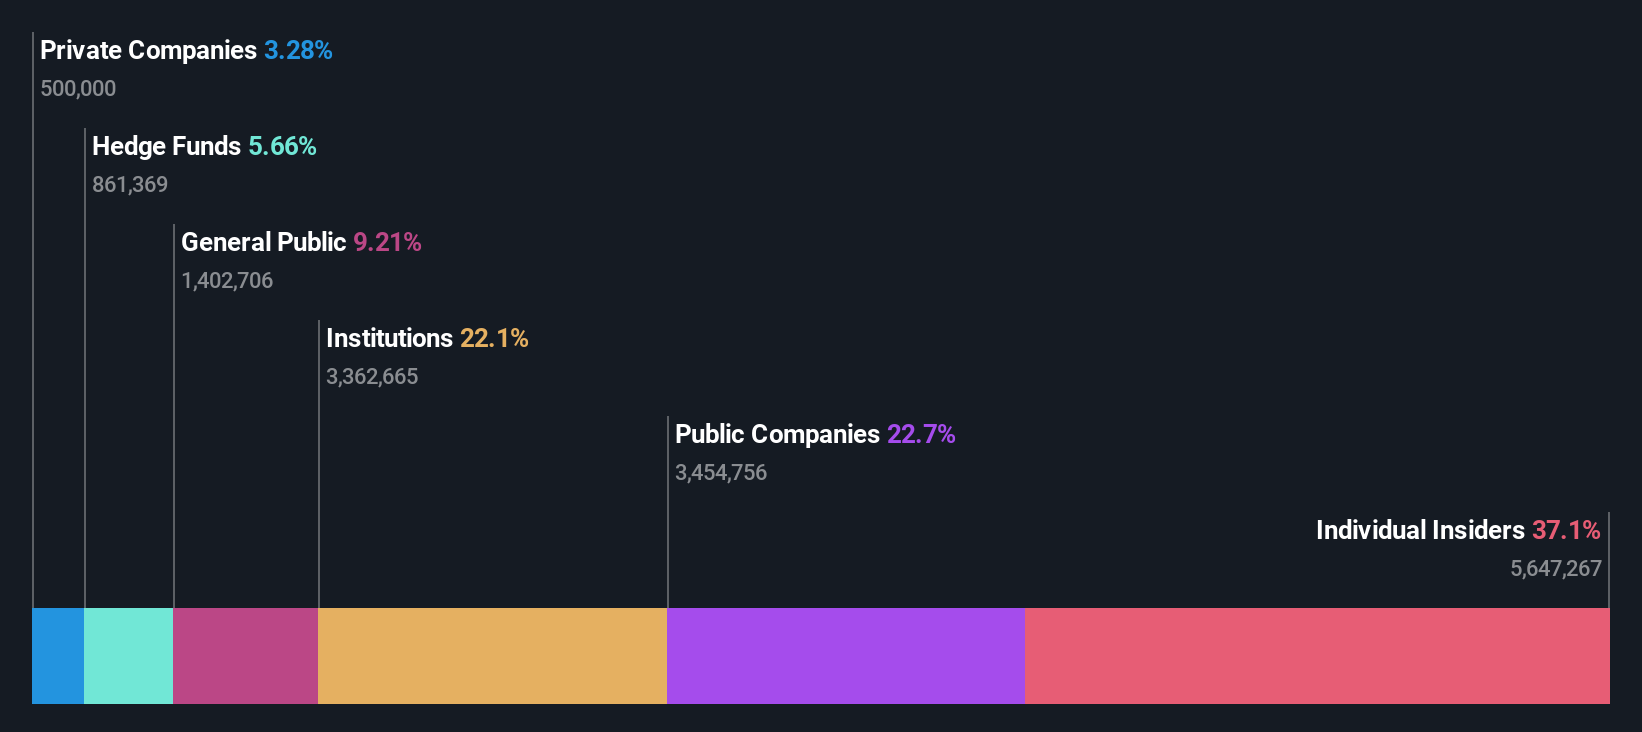
Lifeway Foods (LWAY)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Lifeway Foods, Inc. produces and markets probiotic-based products in North America, with a market cap of $328.42 million.
Operations: The company's revenue primarily comes from its cultured dairy products segment, which generated $242.41 million.
Insider Ownership: 32%
Earnings Growth Forecast: 34.5% p.a.
Lifeway Foods demonstrates strong insider ownership and is trading significantly below fair value, suggesting potential for price appreciation. Despite recent earnings showing a decline in net income to US$0.127 million from US$4.25 million year-over-year, analysts forecast substantial annual profit growth of 34.5%, outpacing the broader U.S. market's 17.6%. However, revenue growth is expected to lag behind the market average, and recent insider activity indicates significant selling over buying within the past quarter.
- Click to explore a detailed breakdown of our findings in Lifeway Foods' earnings growth report.
- Our comprehensive valuation report raises the possibility that Lifeway Foods is priced lower than what may be justified by its financials.
Ramaco Resources (METC)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Ramaco Resources, Inc. is involved in the development, operation, and sale of metallurgical coal with a market cap of $521.05 million.
Operations: The company generates revenue primarily through its metallurgical coal segment, which accounts for $515.42 million.
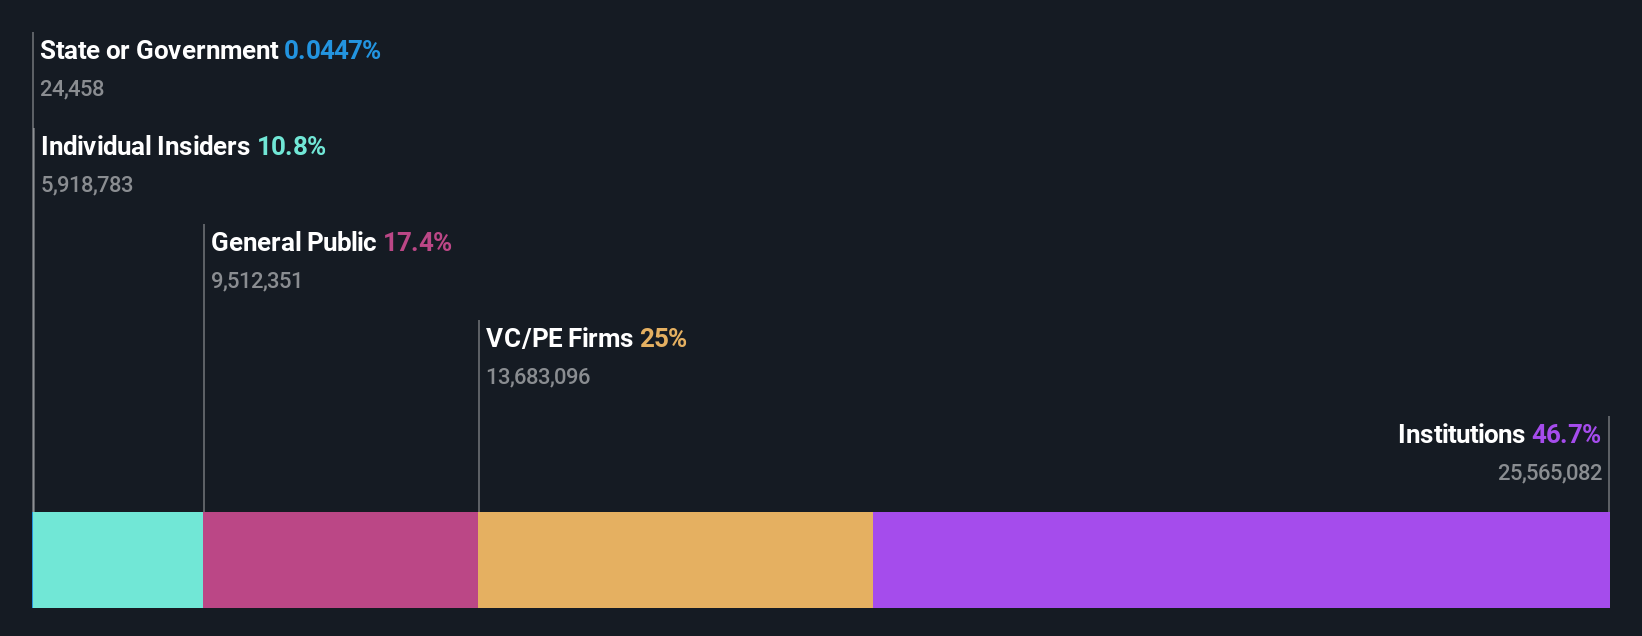
Insider Ownership: 11.3%
Earnings Growth Forecast: 109.4% p.a.
Ramaco Resources, with significant insider ownership, is trading at a substantial discount to its estimated fair value. Despite recent losses and reduced sales guidance due to market conditions, the company is expected to achieve profitability within three years. Revenue growth is projected to exceed 20% annually, surpassing market averages. However, the company's debt coverage remains a concern. Recent strategic alliances in rare earth minerals and e-waste processing highlight potential future growth avenues despite current financial challenges.
- Click here and access our complete growth analysis report to understand the dynamics of Ramaco Resources.
- In light of our recent valuation report, it seems possible that Ramaco Resources is trading behind its estimated value.
HomeTrust Bancshares (HTB)
Simply Wall St Growth Rating: ★★★★★☆
Overview: HomeTrust Bancshares, Inc. is the bank holding company for HomeTrust Bank, offering a variety of retail and commercial banking products and services in the United States, with a market cap of approximately $764 million.
Operations: The primary revenue segment for HomeTrust Bancshares is its banking operations, which generate $210.07 million.
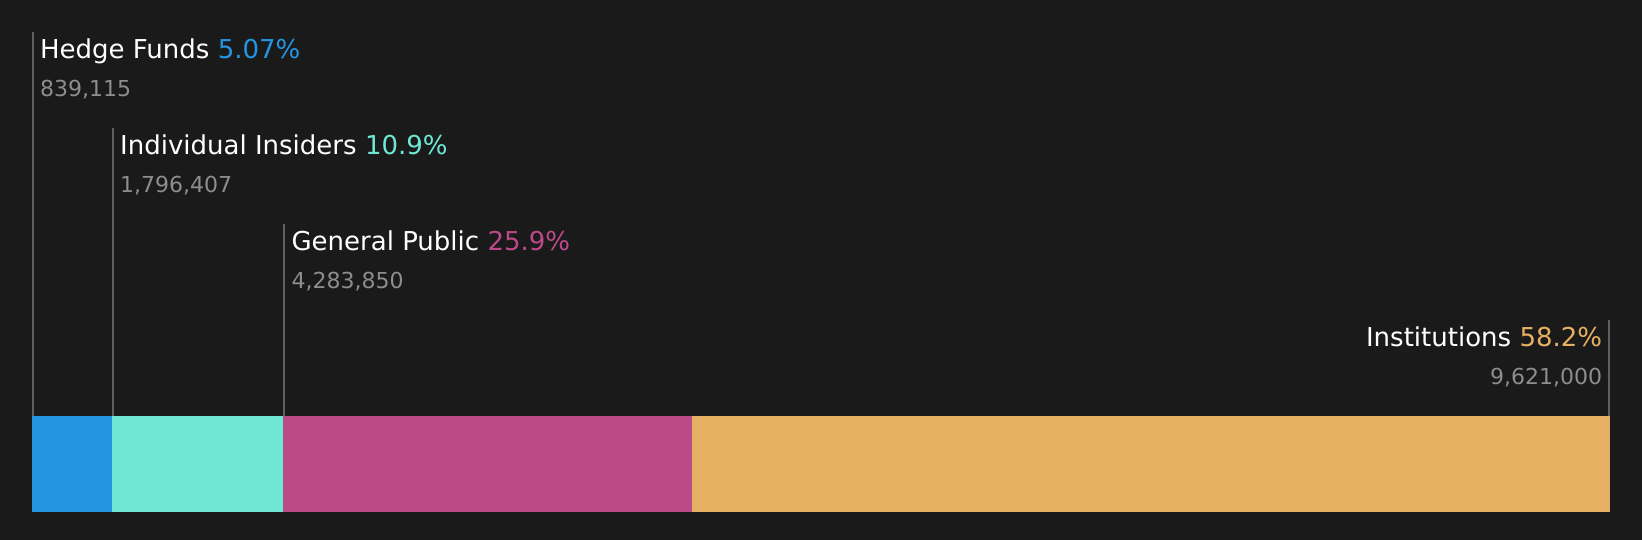
Insider Ownership: 10.9%
Earnings Growth Forecast: 25.9% p.a.
HomeTrust Bancshares demonstrates strong growth potential with earnings and revenue forecasted to grow significantly above market averages. The company is trading below its estimated fair value, suggesting potential upside. Despite a low return on equity forecast, recent strategic moves like the establishment of a Healthcare Banking Division and share buyback programs underscore management's commitment to enhancing shareholder value. Insider ownership remains substantial, aligning interests with shareholders amid these growth initiatives.
- Dive into the specifics of HomeTrust Bancshares here with our thorough growth forecast report.
- Upon reviewing our latest valuation report, HomeTrust Bancshares' share price might be too pessimistic.
Seize The Opportunity
- Click through to start exploring the rest of the 180 Fast Growing US Companies With High Insider Ownership now.
- Searching for a Fresh Perspective? Uncover 26 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com