
Cactus (WHD) After The Baker Hughes Deal, Is The Undervalued Case Still Intact?
Cactus (WHD) is back in focus after agreeing to acquire a majority stake in Baker Hughes' Surface Pressure Control unit, a move that extends its reach and customer list across the Middle East.
The stock has cooled off in the past month, with a 30-day share price return down 7.8%, following a strong 90-day share price gain of 25.4% and a 1-year total shareholder return of 61.6%, which signals that momentum has been building over a longer stretch.
Scan for other energy equipment stocks riding similar expansion stories by checking our curated list of solid balance sheet and fundamentals (25 results) alongside Cactus.
Cactus has been busy expanding while the share price has cooled, which raises a simple tension. Are you looking at a business catching up to sentiment, or sentiment now pulling ahead of the business as it stands?
Most Popular Narrative: 5% Undervalued
Cactus closed at $64.24 compared with a widely followed fair value estimate of $67.56, so the narrative still leans toward a modest discount while incorporating both expansion plans and execution risks.
The acquisition of a majority interest in Baker Hughes' Surface Pressure Control business will significantly expand Cactus' geographic footprint and customer base into the Middle East, an area poised for long-term energy infrastructure investment and supply security, which is likely to support sustained revenue growth and higher earnings resiliency.
See why 9 investors see Cactus as 5% undervalued.
Result: Fair Value of $67.56 (UNDERVALUED)
Still, tariffs that lift steel costs and any slowdown in U.S. drilling activity could pressure Cactus margins and unsettle the current undervaluation narrative.
Find out about the key risks to this Cactus narrative.
Another View On Cactus Valuation
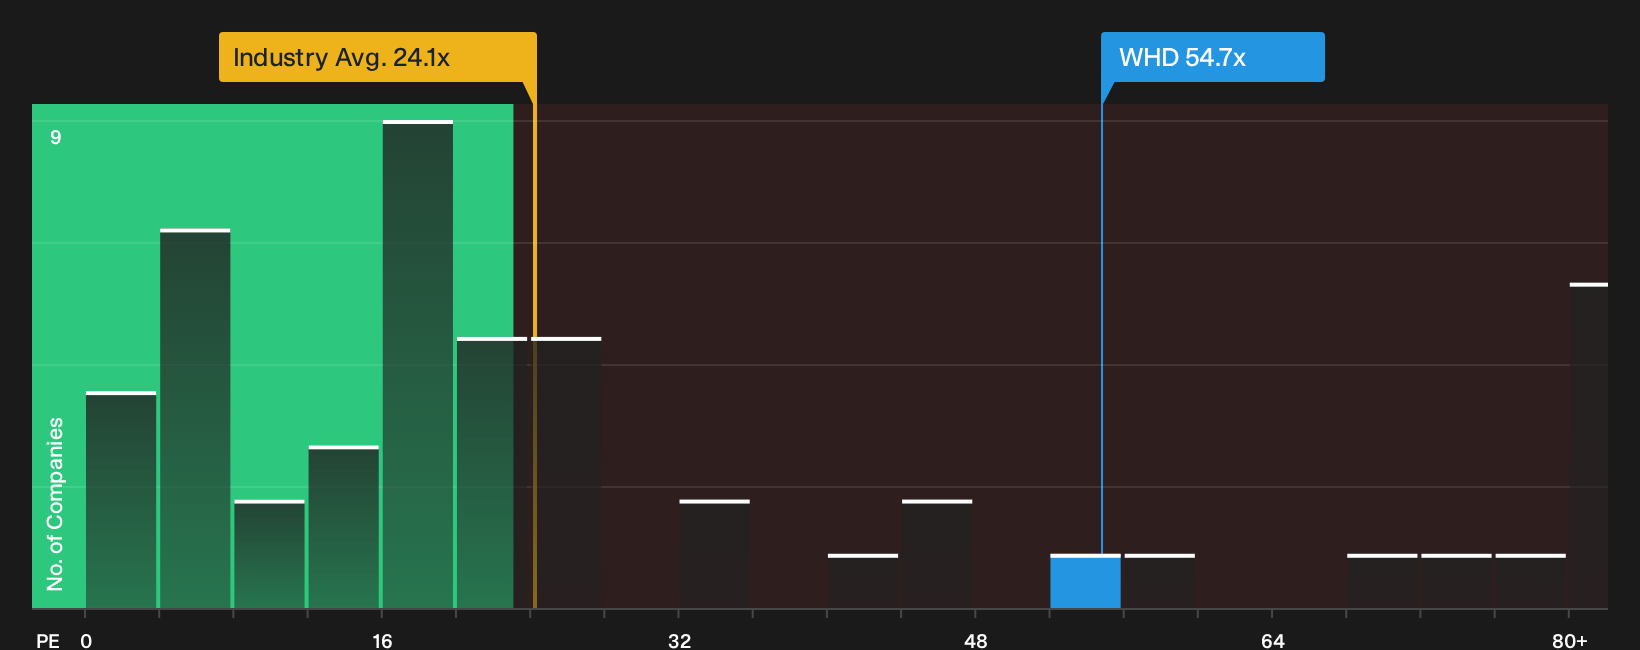
The earlier fair value story leans on future cash flows and points to Cactus as undervalued, yet the P/E picture looks very different. At 54.7x earnings versus a peer average of 28.4x and a fair ratio of 43.4x, the stock trades at a steep premium. Is the market simply paying up for growth, or stretching too far on expectations?
For a closer look at what this richer P/E might mean for upside and downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Cactus so far or leaning one way? Either way, move quickly, review the full picture yourself, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cactus?
If Cactus has you thinking more broadly about your portfolio, use this moment to widen your search before the next wave of opportunities moves on.
- Pinpoint potential bargains early by scanning the 16 high quality undiscovered gems that the market might not be paying full attention to yet.
- Fortify your income stream by zeroing in on 6 dividend fortresses that combine yield with balance sheet support.
- Dial down portfolio risk by tracking 30 resilient stocks with low risk scores designed to keep volatility and financial stress in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com