
3 UK Grid Stocks To Watch As Great British Grid Spending Builds
The Great British Grid plan has turned the UK power system into a live investment story. A new state-backed rival in transmission is arriving just as £70–80b of grid spending is mapped out for the late 2020s, shifting pressure and potential in different directions. This article picks out 3 stocks exposed to that news and explains where the risk, and the opportunity, might sit for your portfolio.
The three UK-listed stocks in this article are only a starter set from the grid upgrade story, and the full screen surfaced 7 more companies with equally compelling narratives that are not covered below. To see the complete picture, head straight to the UK Power Grid Infrastructure & Equipment Suppliers screener to filter, analyze and identify the highest conviction power grid infrastructure plays for your watchlist.
SSE (LSE:SSE)
Overview: SSE is a UK-focused utility that generates electricity and runs high voltage transmission and local distribution networks linking power stations to homes and businesses.
Operations: SSE records around £7.5b from SSE Energy Markets, £5.1b from SSE Thermal, £4.9b from Energy Customer Solutions, and £1.2b each from SSEN Transmission and SSEN Distribution, with most income earned in the United Kingdom.
Market Cap: £29.7b
SSE matters for the Great British Grid story because it already owns key transmission lines and local networks that must handle the coming wave of new pylons, substations and connections.
"UK requires £100bn+ grid investment • SSE is a key transmission player. RAV growth can support higher regulated returns over time."
What happens when one unseen funding pressure meets this build out will be crucial for how much of that grid spend reaches shareholders.
That funding squeeze is exactly what the full narrative for SSE unpacks, showing how SSE’s regulated assets, cash flows, and policy trade offs could be decoupling from headline grid headlines.

Morgan Sindall Group (LSE:MGNS)
Overview: Morgan Sindall Group is a UK construction and regeneration specialist whose infrastructure arm works on energy and grid-related civil engineering projects.
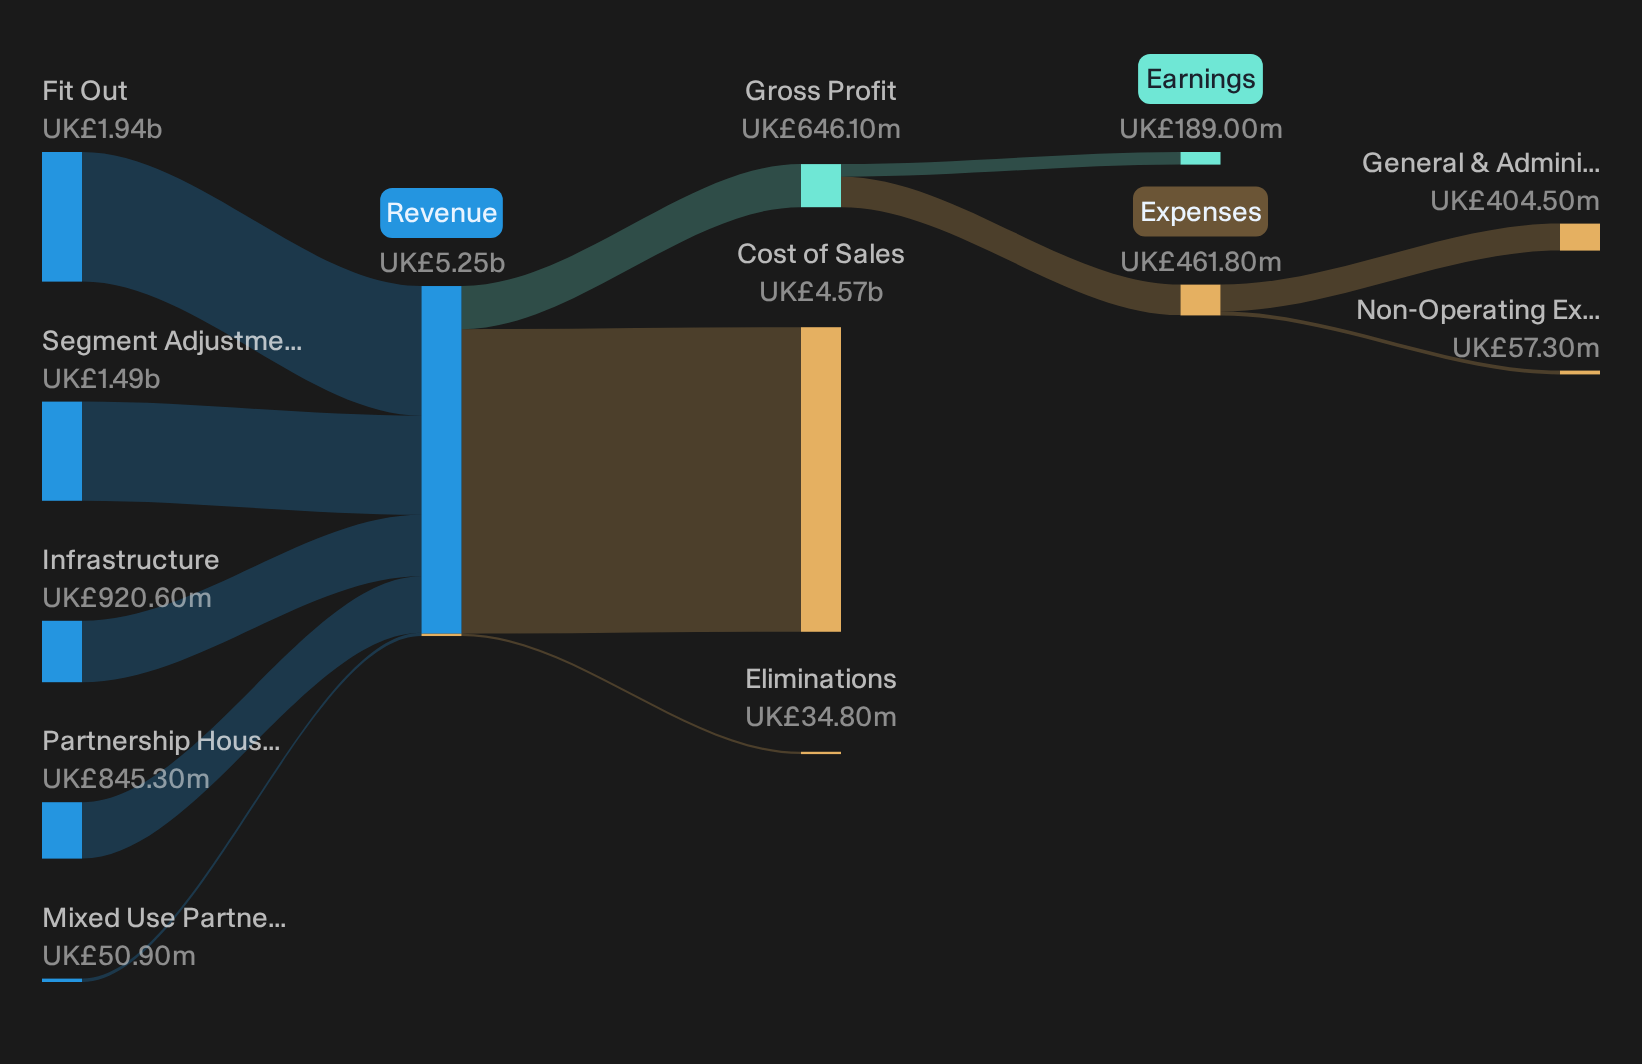
Operations: Morgan Sindall Group generates most revenue from Fit Out at £1.9b, Infrastructure at £921m and Partnership Housing at £845m, almost entirely in the UK.
Market Cap: £2.0b
Where SSE owns and operates large parts of the grid, Morgan Sindall Group is one of the contractors likely to pour the concrete, lay the access roads and deliver the complex civil works that turn new substations and grid connections from policy into physical assets.
"The Group's record-high, rapidly expanding secured order book (up 39% to £12bn) and strong pipeline in both Partnership Housing and Mixed Use suggest robust forward visibility. However, reliance on these large, long-duration projects also increases exposure to risks of regulatory delays, planning bottlenecks and changes in government policy."
For investors, what happens to those long-dated margins if one key policy assumption shifts could be the real swing factor.
That swing factor is exactly what the full narrative for Morgan Sindall Group unpacks. It reveals how Morgan Sindall Group’s order book, risk exposure and upside potential could be shifting under the surface.
discoverIE Group (LSE:DSCV)
Overview: discoverIE Group designs and manufactures custom electronic components used in industrial equipment, including control and sensing systems that can sit inside substation and grid hardware.
Operations: discoverIE generates £267 million from Magnetics & Controls and £176 million from Sensing & Connectivity, with revenue largely coming from Europe and wider international markets.
Market Cap: £779 million
discoverIE Group matters to this grid theme because its specialist power, sensing and control electronics often end up embedded inside transformers, switchgear and substation equipment that grid operators need to upgrade.
"Global supply chain shifts, tariffs, and local manufacturing trends threaten consistent growth and increase volatility, especially in major Western markets."
This raises the question of what happens if one key assumption about how easily those high value components can move around the world quietly breaks.
If that assumption about frictionless component flows is starting to feel shaky, read the full narrative for discoverIE Group to see whether supply chain risk is masking discoverIE Group’s bigger opportunity.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, strong momentum and quietly declining risks tend to be identified early, while it still matters and remains under the radar for now. Act while the window is still open.
- Spot early trend shifts by scanning the 4 resilient stocks with low risk scores that aim to keep drawdowns in check while momentum quietly builds under the surface.
- Hunt for stronger profit engines with the curated list of solid balance sheet and fundamentals (10 results) to see which businesses pair sturdy finances with room for sentiment to improve.
- Target potential inflection points through the hand picked 6 high quality undiscovered gems before improving fundamentals and fresh newsflow pull more investors in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com