
Top 3 British Undervalued Stocks To Watch In September 2026
US Treasury yields near 25-year highs are pulling money toward safer bonds and away from equities, which can leave some solid British businesses priced for pessimism. When sentiment swings this hard, cash rich companies that already generate dependable cash flows can quietly slip to discounted levels. This article highlights three UK stocks that screen as undervalued on future cash flows and explains why they may appeal to patient value hunters.
The three UK stocks below are just a starting sample, since the full screen also surfaced 10 more businesses with equally interesting cash flow stories that are not covered here. To identify and analyze the highest conviction ideas from that wider group, head straight into the Undervalued Stocks Based On Cash Flows screener.
A.G. BARR (LSE:BAG)
Overview: A.G. BARR manufactures and sells branded soft drinks and cocktail solutions like IRN-BRU, Rubicon and Snapple across the UK and internationally.
Operations: A.G. BARR generates £382 million from Soft Drinks, £35.8 million from Cocktail Solutions and £19.5 million from Others, with £418.8 million from the UK and £18.5 million from the Rest of the World.
Market Cap: £665 million
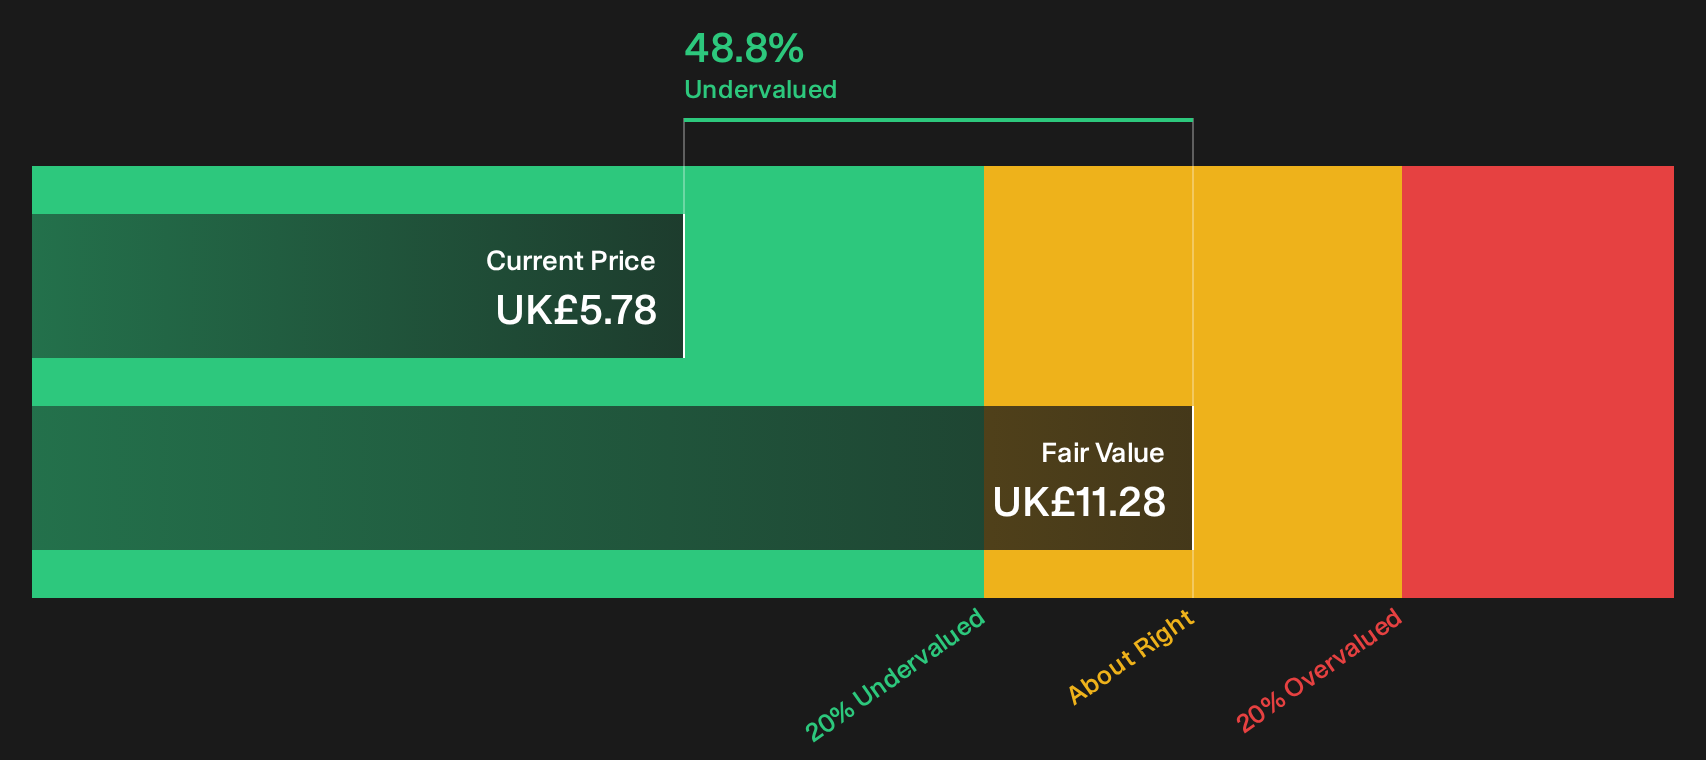
A.G. BARR lines up neatly with this cash flow focused screen, with a P/E of 13.6x versus a European Beverage industry 17x and a DCF estimate that sits well above the current share price. The focus is on the branded soft drink cash generation, which investors pay a clear discount for today, contingent on a single pressure point on that cash flow path behaving as expected.
That single hinge point on A.G. BARR’s cash engine is exactly what you can stress test in the DCF valuation analysis for A.G. BARR, where the valuation tension becomes clear.
AltynGold (LSE:ALTN)
Overview: AltynGold plc explores, develops and operates the Sekisovskoye gold mine and nearby Teren-Sai projects in northeast Kazakhstan, generating gold and silver focused cash flows.
Operations: AltynGold generates its entire reported $175 million in revenue from exploration and development at the Sekisovskoye gold operation in Kazakhstan.
Market Cap: £272 million
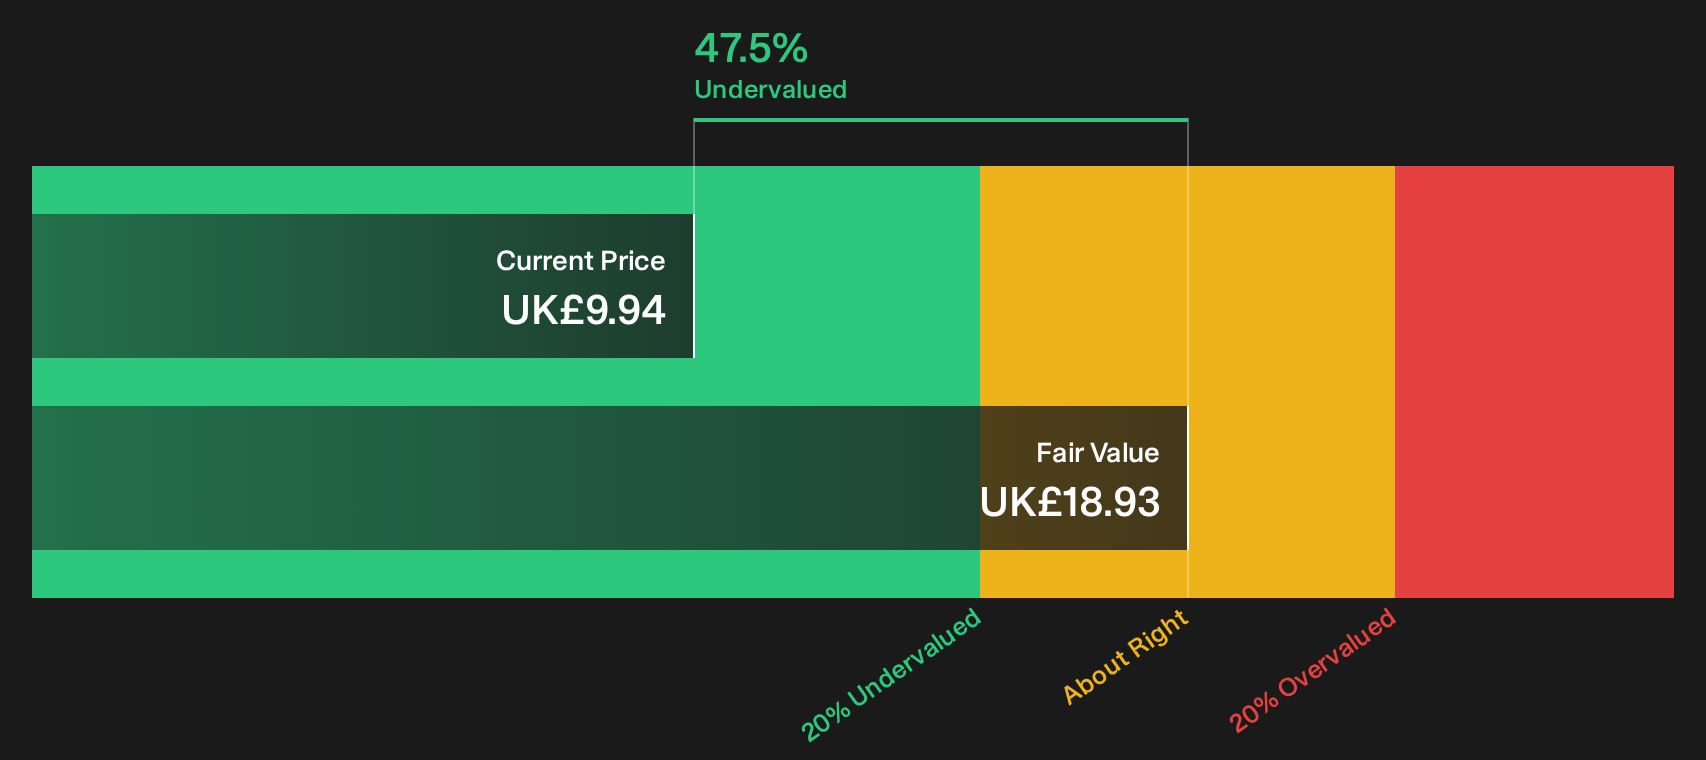
AltynGold fits into this cash flow focused screen because its Sekisovskoye and Teren-Sai assets support a P/E of 5.8x and a share price that is below an SWS DCF value of £18.93. The wide discount, 35.4% profit margin and 41.3% ROE all indicate cash generation that may not be fully reflected in today’s valuation, depending on how one key funding pressure develops.
That funding hinge is exactly what you can pressure test in the analysis report for AltynGold to see how AltynGold’s valuation could react if conditions shift.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages renewable energy infrastructure and private equity funds, aiming to turn long-term contracted assets into fee based cash flows.
Operations: The group generates £114.8 million from Real Assets and £50.1 million from Private Equity, with £126.4 million coming from the United Kingdom.
Market Cap: £480 million
Foresight Group Holdings matters for this cash flow focused screen because its renewable infrastructure platforms are built around long term, contract backed income streams that can feed directly into DCF style valuations.
"Foresight is rapidly evolving new product strategies such as standalone private credit-focused business relief, with early demand signaling the potential to become a flagship offering, accessing sizeable, untapped wealth and institutional flows and elevating recurring revenue growth rates as financial advisors and pension funds shift allocations for long-term yield."
The real test for investors is how one less visible cost pressure shapes the gap between those growing fee streams and future profit margins.
That cost pressure is exactly what could be masking the full story behind Foresight Group Holdings’ fee engine. This is unpacked in the full narrative for Foresight Group Holdings, which reveals how those economics might evolve.

Curious About What You Might Be Missing?
Fresh ideas keep moving. Breakout stories gain momentum, quiet compounders stop flying under the radar for now, and fallen leaders risk getting caught dropping before the crowd reacts. Consider your options carefully.
- Identify cash generative outliers before momentum headlines catch up by scanning the 6 high quality undiscovered gems curated to surface businesses that quietly pair solid balance sheets with robust underlying performance.
- Explore potential income pillars while yields still look compelling by reviewing the 1 dividend fortresses built to highlight payout strength alongside balance sheet resilience.
- Follow structural demand in critical materials by tracking the 17 top copper producer stocks that focuses on producers connected to long term electrification and infrastructure trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com