
3 Consumer Staples Stocks For Steady Dividends As Rate Pressure Builds
Consumers are turning cautious, inflation is still biting, and borrowing costs keep climbing, yet some companies are built to ride out that kind of stress. Defensive, dividend-paying consumer staples and utilities can sometimes offer investors a way to stay invested without leaning on high-octane growth stories. This article examines how the recent data shock affects market sentiment and highlights 3 stocks from our screener that look relatively well positioned.
The three companies below are just a starting sample from this idea, and the full screen surfaced 13 more large, income-focused businesses with similarly compelling stories that are not covered here. To go straight to the full list, analyze dividend strength, and identify your own highest conviction picks, head into the Defensive, Dividend-Paying Consumer Staples and Utilities screener.
Tyson Foods (TSN)
Overview: Tyson Foods is a global protein producer that supplies beef, pork, chicken, and prepared foods to retailers, restaurants, and foodservice customers.
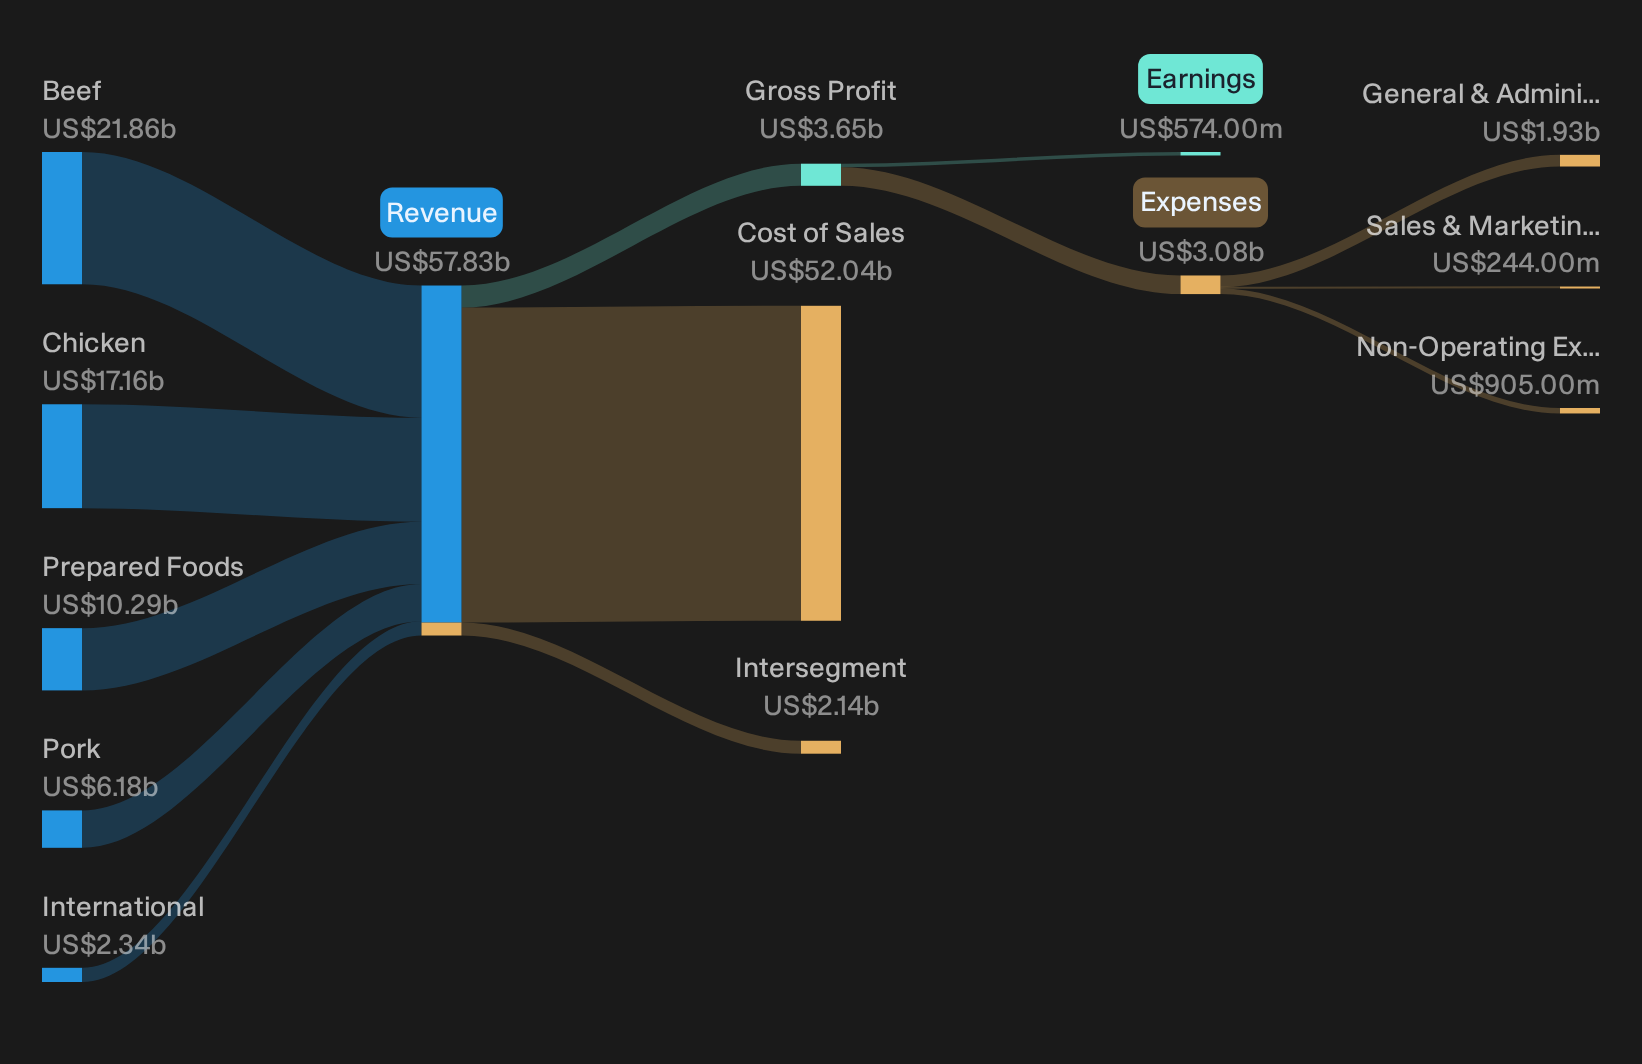
Operations: Tyson Foods generates revenue primarily from beef at about US$21.9b, chicken at roughly US$17.2b, and prepared foods at around US$10.3b.
Market Cap: US$17.9b
Tyson Foods fits this defensive, dividend-paying staples theme because protein tends to stay in household baskets even when confidence falls and budgets tighten, which gives this large processor a practical way to keep cash coming in while it works on improving profitability.
"Momentum in prepared and value-added foods, driven by a robust innovation pipeline and product launches targeting convenience and protein-oriented lifestyles, is shifting the product mix toward higher-margin categories and is expected to improve net margins and top-line growth."
What happens to those improving economics will depend heavily on how one unresolved pressure in its protein supply chain ultimately plays out.
That supply chain wildcard is exactly what the full narrative for Tyson Foods unpacks, revealing how margin pressure, pricing power and dividend resilience could be quietly decoupling for Tyson Foods.
Coca-Cola FEMSA. de (KOF)
Overview: Coca-Cola FEMSA is a major Latin American bottler that produces, sells, and distributes Coca-Cola beverages and related drinks across everyday retail channels.
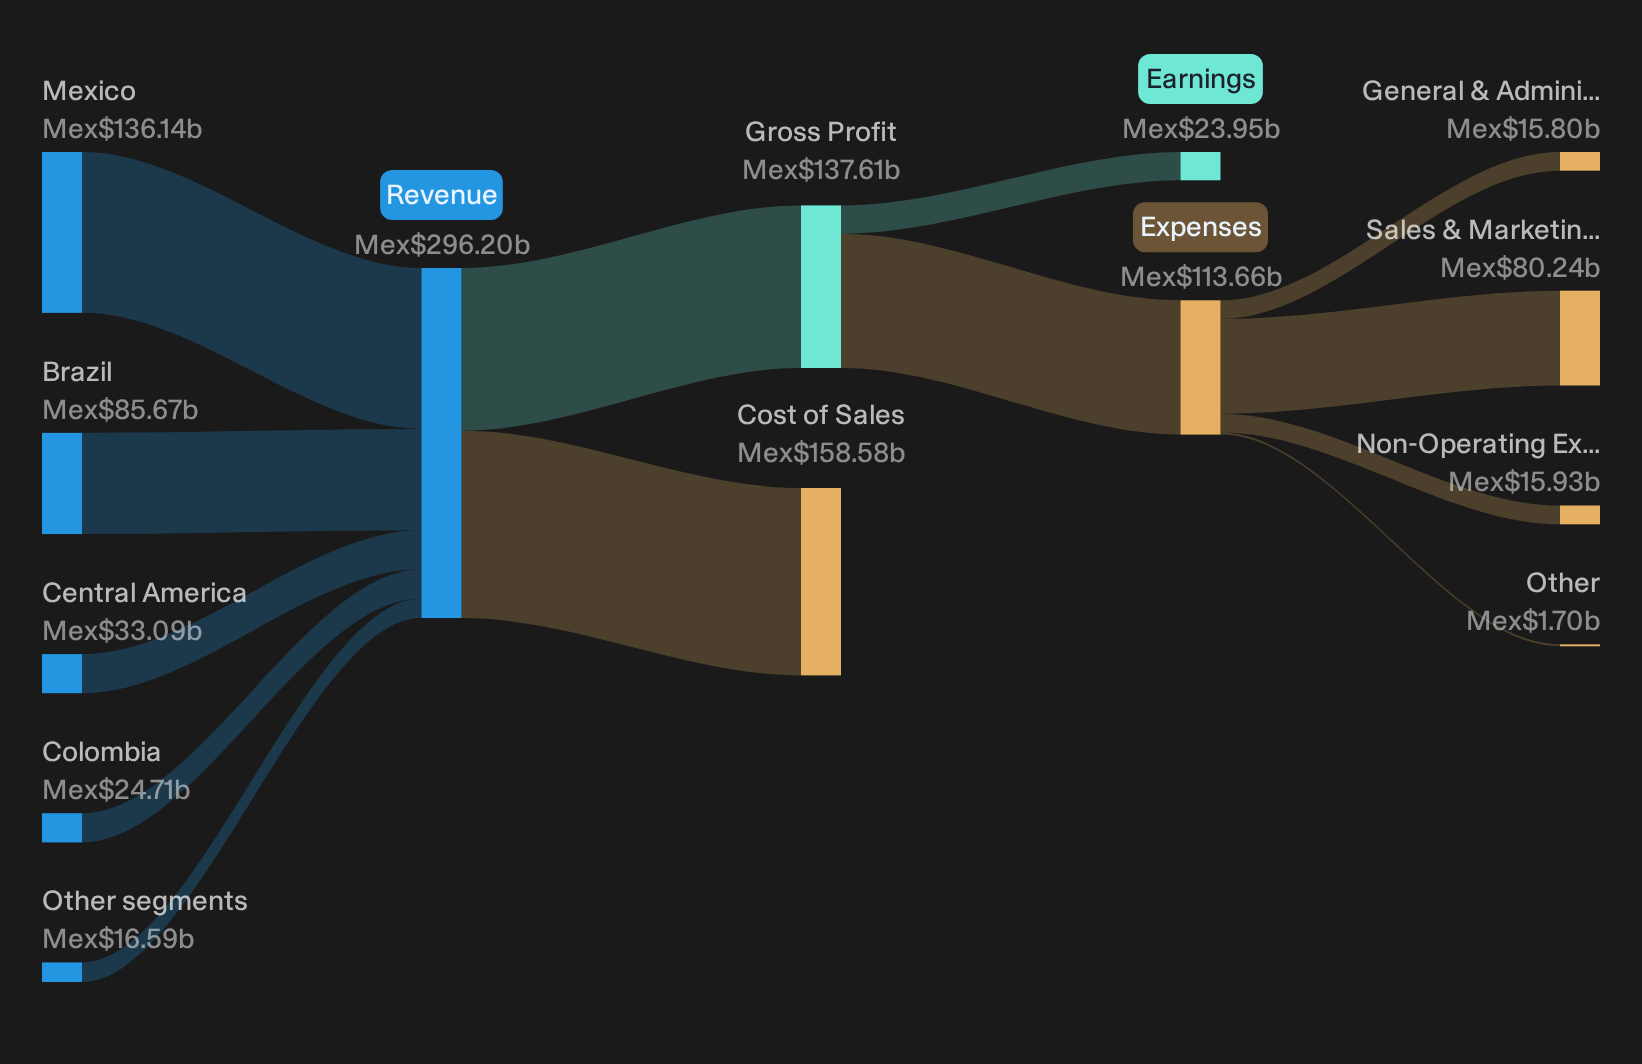
Operations: Coca-Cola FEMSA generates about MX$296.2b from non-alcoholic beverages, led by Mexico at MX$136.1b and Brazil at MX$85.7b, with additional sales across Central and South America.
Market Cap: US$23.2b
Coca-Cola FEMSA fits this defensive, dividend-focused staples theme because it sells affordable, habitual drinks that tend to stay in shopping baskets even when consumer confidence weakens and interest rates rise. The real story is how its digital toolkit could influence the quality of those recurring pesos.
"Further rollout of Coca-Cola FEMSA’s Juntos+ digital ordering and Juntos+ Advisor tools into additional territories beyond Mexico and Brazil could extend the uplift in purchase frequency, average ticket and cooler coverage already seen in these markets."
What that means for future cash generation hinges on how one subtle shift in product mix and cost discipline plays through to margins.
That margin question is where the story gets interesting, and the full narrative for Coca-Cola FEMSA. de lays out how pricing power, mix and digital execution could quietly reshape Coca-Cola FEMSA’s earnings quality.
Hershey (HSY)
Overview: Hershey is a global confectionery and snacks group that sells branded chocolate, sweets, and pantry items across retailers worldwide.
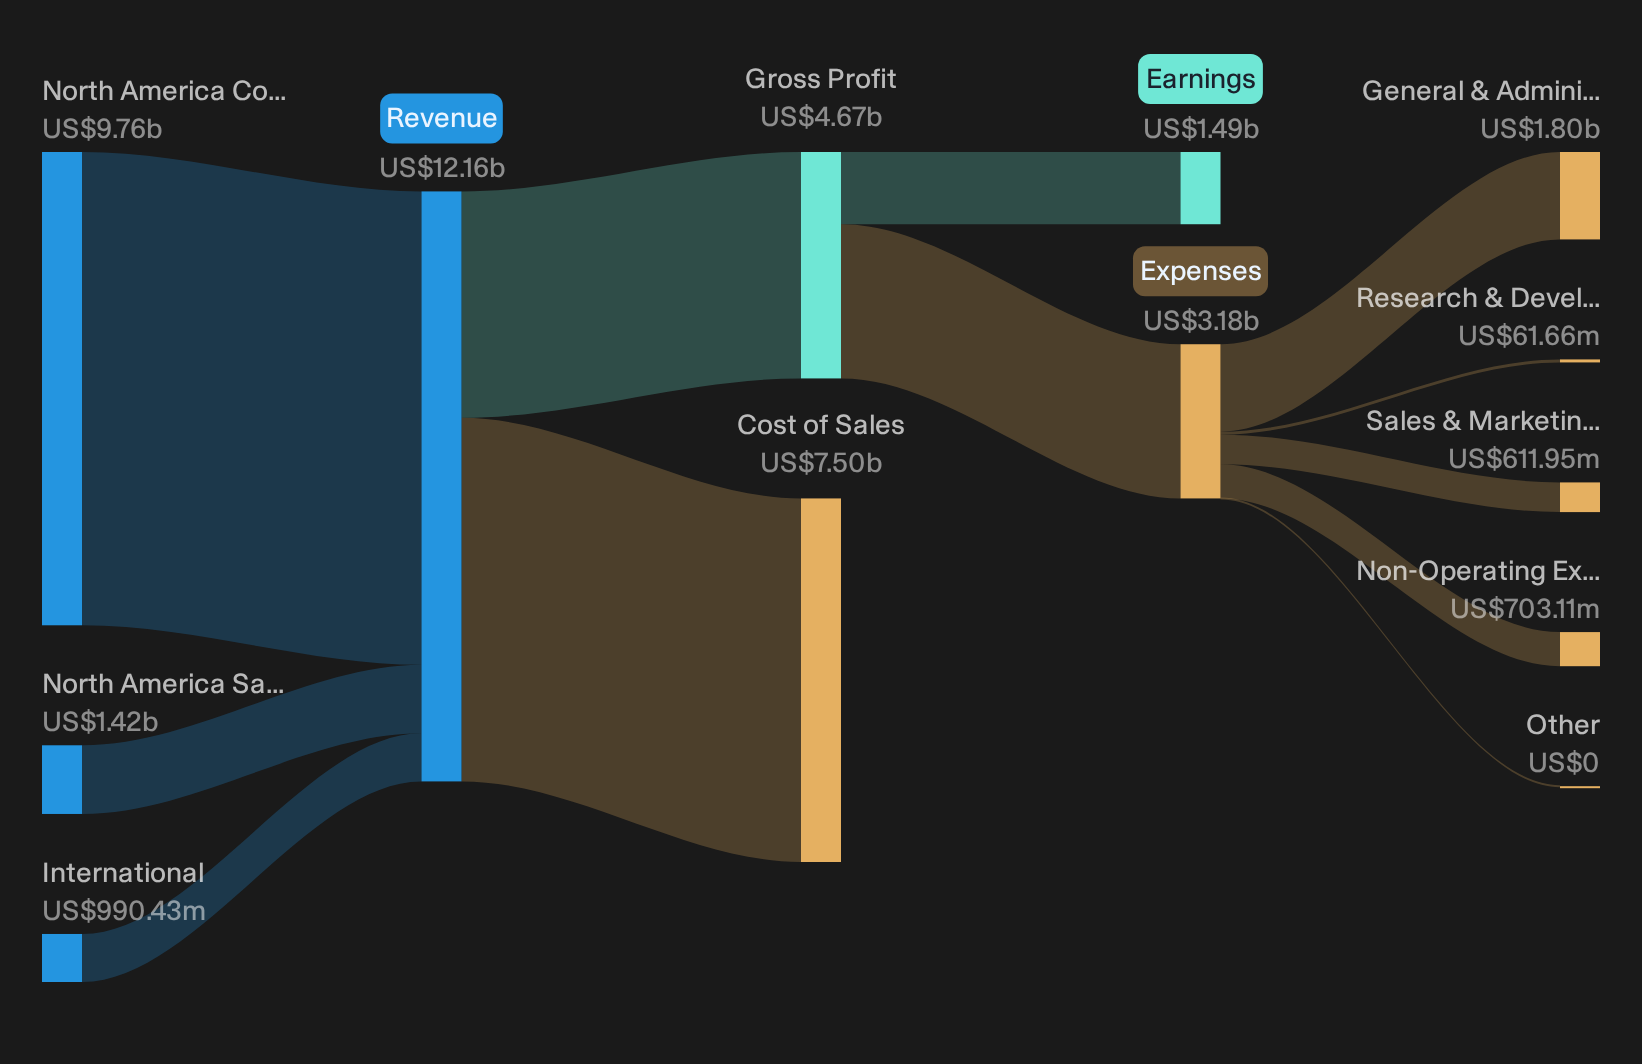
Operations: Hershey generates about US$9.8b from North America Confectionery, US$1.4b from North America Salty Snacks, and US$1.0b from International markets, with most sales in the United States.
Market Cap: US$33.4b
Hershey fits neatly into this defensive, dividend-paying staples theme because its everyday treats and pantry products often remain in baskets even when confidence slides and budgets come under strain.
"The forward thesis rests on three assumptions: that cocoa is structurally elevated but normalizing, allowing operating margin to recover toward a ~24% ceiling over the decade; that the One Hershey strategy extends the moat into salty, functional, and international adjacencies to sustain mid-single-digit (~3.5%) revenue growth."
What ultimately happens to that income-friendly profile depends heavily on how one silent cost pressure shapes margins over the next few years.
That quiet cost squeeze is exactly what the full narrative for Hershey unpacks, showing how cocoa, pricing and One Hershey execution could influence its long term earnings.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, prices can rise before you have even spotted them. Scan these curated shortlists while they are still under the radar for now and consider them early.
- Target reliable cash generators by scanning a curated list of solid balance sheet and fundamentals (25 results) that can help you focus on sturdier businesses before the crowd catches on.
- Look for early upside by reviewing 32 high quality undervalued stocks that blend quality fundamentals with compressed expectations while that valuation gap still matters.
- Track potential candidates for the next energy buildout by following 39 power grid technology and infrastructure stocks that could benefit if infrastructure spending shifts toward grid resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com