
Sandoz Group (SWX:SDZ) Has Investors Looking Twice Again
Why Sandoz Group Stock Is Back on Investor Radars
Sandoz Group (SWX:SDZ) has been added to the Swiss SMI Index, a move that can reshape how large institutional investors and index funds treat the stock in diversified Swiss portfolios.
Recent catalysts have arrived in quick succession for Sandoz Group, from Health Canada’s approval of its generic semaglutide injection to a fresh biosimilar collaboration with mAbxience and now inclusion in the Swiss SMI Index. Against that backdrop, the share price has moved to CHF72.0, with a 1-month share price return of 4.5% and a year-to-date share price return of 25.83%. The 1-year total shareholder return of 54.49% indicates that momentum has been building rather than fading over the past year.
Scan beyond Sandoz Group and see how other healthcare players are responding to similar catalysts by reviewing our curated list of 133 healthcare AI stocks in the sector.
Sandoz Group has already put up a 1-year total return of 54.49%, yet the stock still trades at what our intrinsic value work suggests is a 37.63% discount. How much of the upside is actually gone?
Most Popular Narrative: 4% Undervalued
On the most followed view of Sandoz Group, a fair value of CHF74.95 sits modestly above the last close at CHF72.00, which frames today’s upside as incremental rather than dramatic based on that model.
Regulatory streamlining and investments in advanced in-house manufacturing (notably Slovenia expansion and Just-Evotec acquisition) are expected to lower production costs and speed up time-to-market for new biosimilars, driving margin expansion and higher net earnings. Strong commercial execution and leading market share in biosimilars, now 30%+ of net sales and growing, improves Sandoz's revenue mix towards higher-margin products, supporting overall profitability and long-term earnings leverage.
See why 39 investors see Sandoz Group as 4% undervalued.
Result: Fair Value of CHF74.95 (UNDERVALUED)
Still, price pressure in generics and biosimilars, along with Sandoz Group’s heavy reliance on partnerships and Europe, could challenge the margin story investors are watching.
Find out about the key risks to this Sandoz Group narrative.
Another View on Sandoz Group Valuation
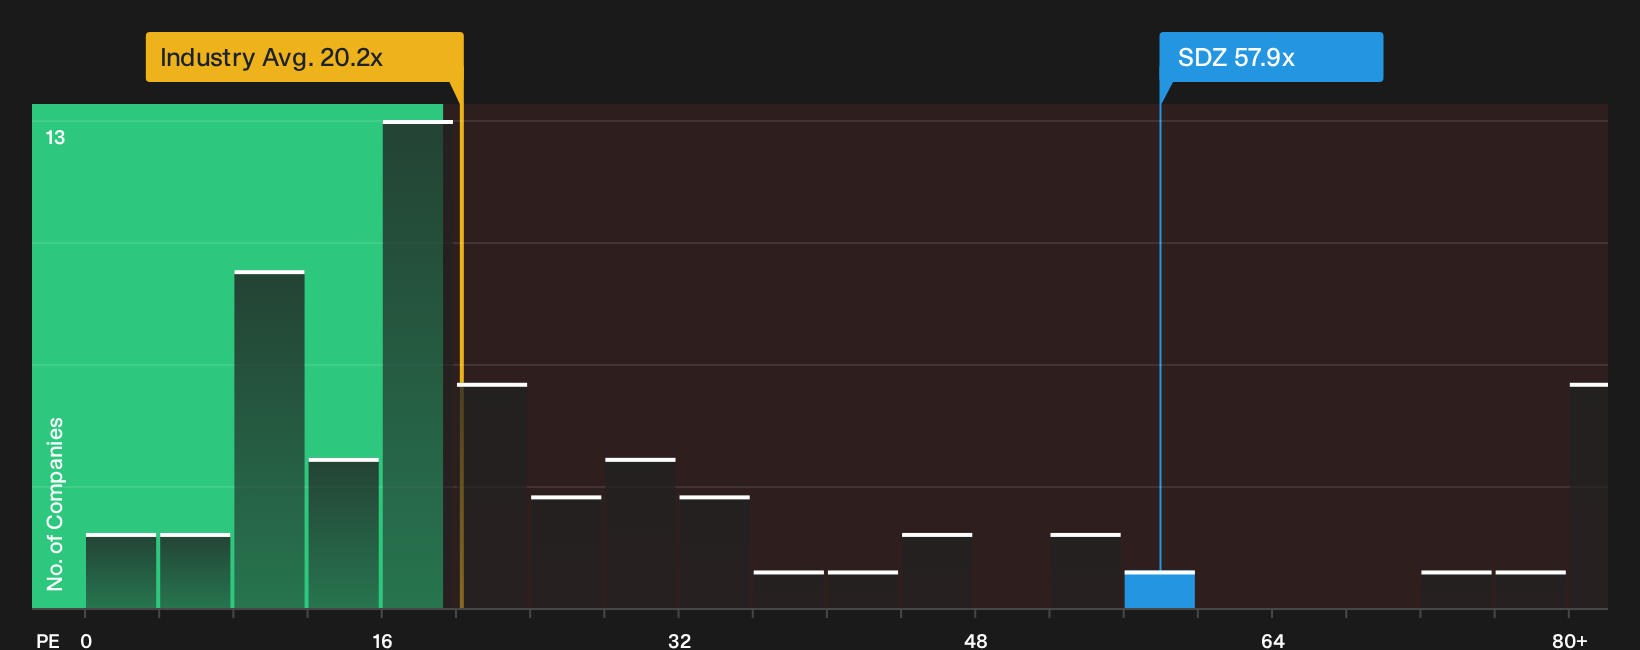
On a simple earnings multiple, Sandoz Group looks expensive. The stock trades on a P/E of 57.9x compared with 20.2x for the European pharmaceuticals industry and 33.1x for its peer group. The fair ratio sits lower again at 38.8x.
That gap suggests investors are paying a high price today for future growth. This raises the question of how much execution risk you are comfortable taking on.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around Sandoz Group feels mixed, that is the signal to go straight to the source data and pressure test the thesis yourself before momentum shifts. To understand why some investors still see upside potential, start with its 3 key rewards
Looking for more Sandoz Group sized ideas?
Do not stop with Sandoz Group. Fresh ideas are where future returns often start, so give yourself more options before the next catalyst hits.
- Target quality at a discount by scanning companies that pass strict value and fundamentals checks using our 202 high quality undervalued stocks.
- Strengthen the income side of your portfolio by reviewing a focused set of high-yield opportunities through our 164 dividend fortresses.
- Upgrade your defensive holdings by checking companies with robust finances using the list of solid balance sheet and fundamentals (204 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com