
How Cash Reserves And Lumilens Deal At POET Technologies (POET) Have Changed Its Investment Story
- POET Technologies is emphasizing its Optical Interposer platform for AI data centers, supported by a sizable cash reserve and a Lumilens partnership that includes a significant order and a planned ramp up of optical engine production in the second half of 2026.
- The focus on cash on hand and contracted demand from Lumilens shows how POET Technologies is attempting to fund heavy development and manufacturing plans without relying solely on new equity raises.
- We will now look at how POET Technologies' investment narrative could change as its strong cash position supports AI focused optical engine plans.
Scan other AI focused hardware plays that pair strong balance sheets with real data center exposure by zeroing in on 88 AI infrastructure stocks as potential peers to POET Technologies.
POET Technologies Investment Narrative Recap
For POET Technologies, the core belief is that its Optical Interposer platform and AI focused optical engines can convert today’s contracts and customer interest into material shipment volumes from 2026 onward. The current news around cash on hand and Lumilens demand supports that thesis, since it suggests the firm has funding visibility to keep building capacity.
The near term catalyst still sits in execution on the planned ramp to high volume 800G production and turning the Lumilens contract into recurring product revenue. The biggest near term risk remains cash burn and potential further dilution, together with legal costs and any new customer setbacks similar to the Celestial AI cancellation.
The Lumilens partnership matters most here. Management has highlighted an initial US$50 million purchase order and the possibility of total orders above US$500 million over five years, tied directly to POET Technologies’ plan to supply optical engines for AI data centers. That agreement provides contracted demand that helps support the capital plan.
For you as a shareholder, the key questions are whether POET Technologies can install the planned US$50 million of equipment, move from small batch output to large scale production in the second half of 2026, and manage the industry wide laser shortage. Progress on Lumilens milestones will likely be a key reference point for assessing how realistic those future volumes appear.
POET Technologies’ current loss of $75.7 million is set against analyst forecasts for earnings of $36.8 million and revenues of $333.2 million by 2029, which implies revenue growth each year that is described as very large, as well as a roughly $112.5 million swing in earnings from today’s loss to the 2029 consensus profit.
Uncover why POET Technologies' fair value indicates a 92% potential upside to its current price that could narrow quickly.
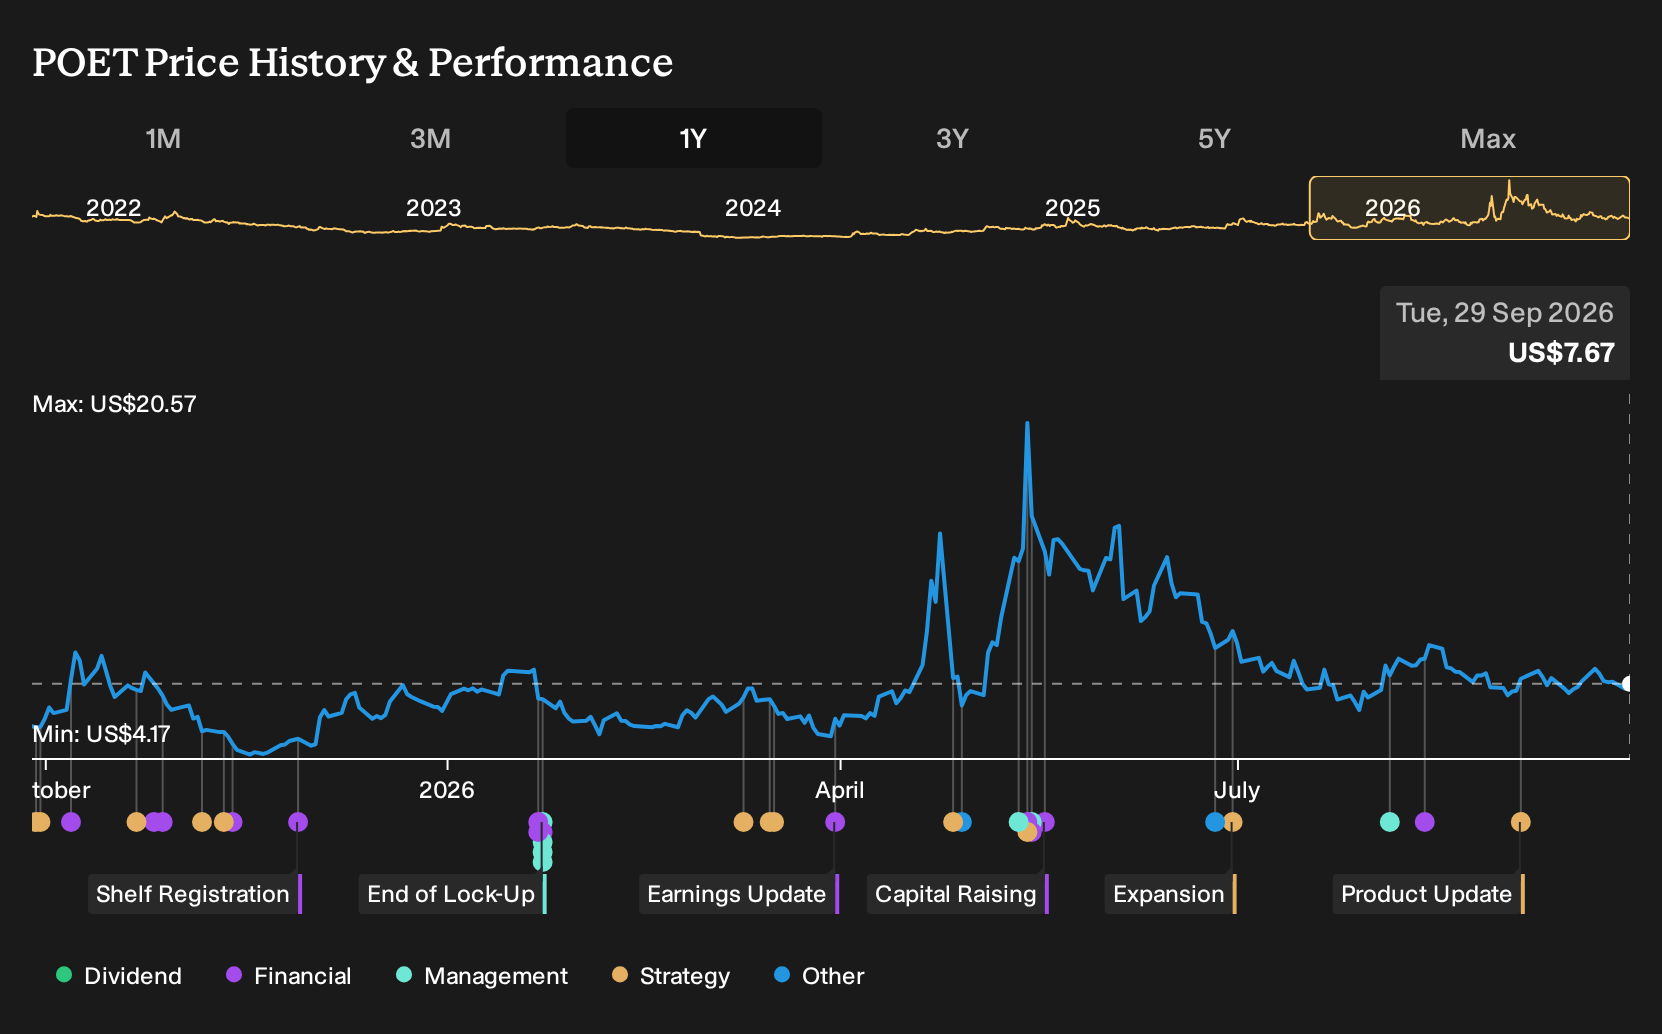
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community cluster between US$4.80 and US$17.37, which shows how far opinions on POET Technologies can stretch. Some users focus on Lumilens volume potential and AI optics demand, while others anchor on cash burn, lawsuits, and customer losses, so you should weigh these contrasting views directly.
Explore 4 other POET Technologies fair value estimates, including one that suggests as much as 126% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your POET Technologies research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for POET Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate POET Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond POET Technologies?
If the POET Technologies story has your attention, it can help to compare it with other opportunities that match your preferred mix of quality, risk, and income potential. The Simply Wall St Screener lets you quickly filter for stocks that line up with the kind of balance sheet strength, value profile, or yield you want to research next.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tough conditions and still fund growth plans.
- If you prefer to focus on valuation first, scan a 31 high quality undervalued stocks that combine strong fundamentals with prices that analysts view as attractive.
- Income focused portfolios might begin with a 6 dividend fortresses that pair 5%+ yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com