
Silicom (SILC) Stock Revenue Surge Clashes With Ongoing Losses
Silicom stock barely flinched after earnings, inching up about 0.5% to US$51.37, yet the numbers told a far more charged story. This was a quarter defined by a single tension point: the business is pushing hard on growth while still sitting in the red.
Revenue reached US$23.8m, and for a networking hardware player that scale now matters because the earnings call spotlighted a clear theme. Losses narrowed on a net basis, and management talked openly about a path back to non GAAP profitability in the second half of 2026. The market reaction looked calm compared with that shift in tone.
Is Silicom's 3.9x P/S multiple signaling justified growth optimism or overstretched expectations given ongoing losses and recent volatility? Compare current pricing against the underlying fundamentals through our valuation analysis for Silicom.Q2 2026 Earnings Summary
- Revenue (Q2 2026 vs. Q2 2025): US$23.8m vs. US$15.0m (up 59%)
- Net Loss (Q2 2026 vs. Q2 2025): US$2.1m loss vs. US$3.3m loss (loss narrowed 37%)
- Basic EPS (Q2 2026 vs. Q2 2025): US$0.37 loss per share vs. US$0.59 loss per share (loss per share improved 37%)
- Gross Margin (Q2 2026 vs. Q2 2025): 30.4% vs. a prior-year level implied to be below the current range, with Q2 2026 at the upper end of the 27% to 32% guidance band
Prefer clean charts over another wall of numbers? See Silicom's full financial picture, including a visual view of its valuation, in our company report for Silicom.
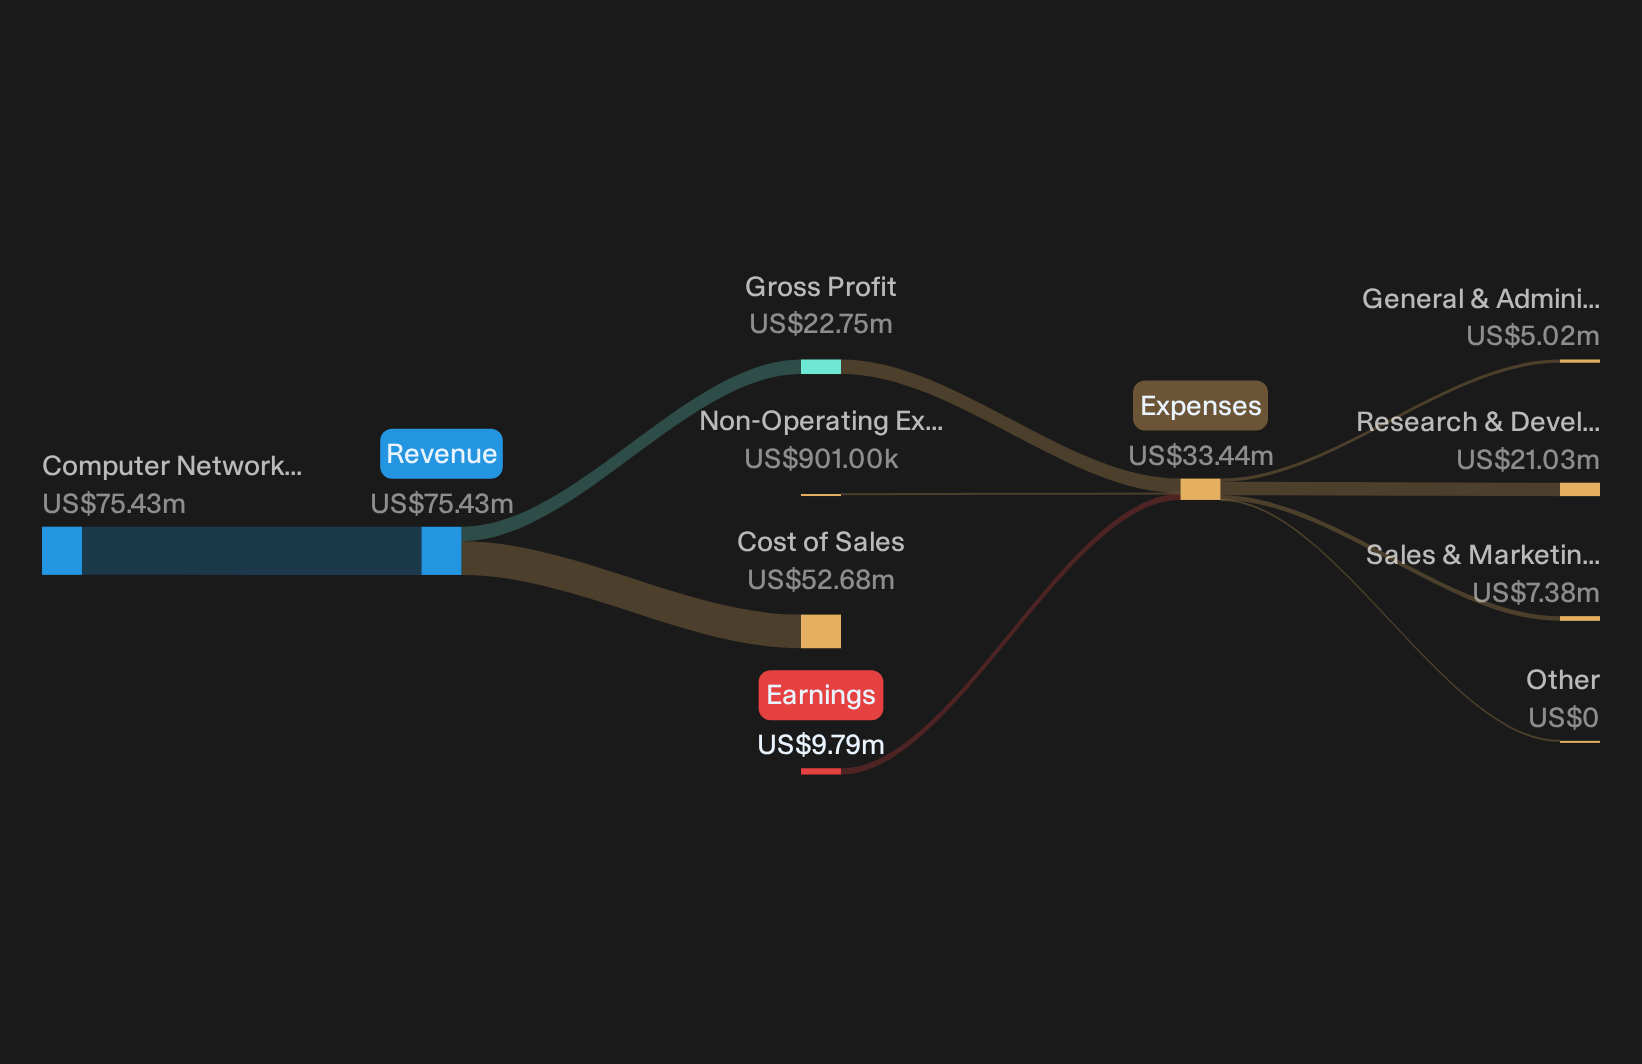
Silicom bull case leans on growth momentum
For a bullish lens on Silicom, the story starts with pace. Revenue of US$23.8m is well ahead of last year and management lifted full year sales guidance to US$93m to US$95m. Losses are shrinking as operating expenses rise far slower than the top line. Gross margin at 30.4% sits at the top of the guided band, which helps the path back to non GAAP profit in the second half of 2026 look directionally consistent with the recent run rate.
Bear case focuses on losses and concentration risks
The cautious view on Silicom still has plenty to hold on to. The business is loss making, with a US$0.9m net loss and EPS in the red. Two customers provide about 23% of revenue, which keeps customer risk front and center even as design wins broaden. Inventory has climbed to US$71m to support future ramps, which ties up cash and brings obsolescence risk if demand timing slips or product specs change.
After inventory growth, volatile trading and recent insider selling, it is fair to ask whether these are isolated issues or early signals of deeper structural problems. Review Silicom’s full risk scoring and hidden pressure points in our risk analysis for Silicom which shows 3 important warning signs.Stay Ahead With Simply Wall St
Silicom's mix of revenue growth, ongoing losses, and concentrated customers makes timing especially important, so register for free with Simply Wall St and add it to a Watchlist to track price against fair value and watch for your preferred entry zone. After you decide to buy or sell, keep your decisions grounded with the Portfolio Command Center that cuts through day to day noise and flags the updates that matter. For longer term conviction, use the Community to see how other investors are thinking about similar risks and potential catalysts. That way you can surface emerging opportunities and pressures early and give yourself a better chance of staying ahead of the market.
Seeking Alternatives Beyond Silicom?
Fresh ideas move first. Stocks can be flying one month and dropping the next, so scan under the radar for now, before the crowd, and get in early.
- Spot resilient income plays that keep cash coming in while prices move around by scanning the curated 6 dividend fortresses before yields get caught in a frenzy.
- Track future tech infrastructure where real capital is flowing and momentum quietly builds by reviewing the hand picked 39 power grid technology and infrastructure stocks while it still flies under the radar.
- Hunt for companies building tomorrow's automation backbone by zeroing in on the focused 92 robotics and automation stocks before valuations start breaking out on rising demand stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com