
J. M. Smucker (SJM) Stock Could Be Above Fair Value Following New Coffee Launch
J. M. Smucker has delivered a solid run in 2026, yet its recent pullback leaves a clear question for investors who focus on earnings. After a strong year to date move and fresh product news, the issue is whether the current US$120.70 share price is adequately supported by the profits the business is generating.
- The stock is up 24.9% year to date, which puts real weight on the question of how firmly its earnings can underpin that gain.
- Folgers' new functional coffee range aimed at health focused consumers can influence how investors think about J. M. Smucker's future revenue mix and profit quality.
- There is a second opinion on J. M. Smucker worth weighing. See what analysts think J. M. Smucker's shares could be worth.
The stock's next move may depend on whether that recent share price level lines up with what J. M. Smucker is currently earning.
If you want more ideas built around earnings power and product news like J. M. Smucker's, a focused stock screen is a useful second starting point for research in the form of 31 high quality undervalued stocks.
Does J. M. Smucker Look Pricey on Earnings?
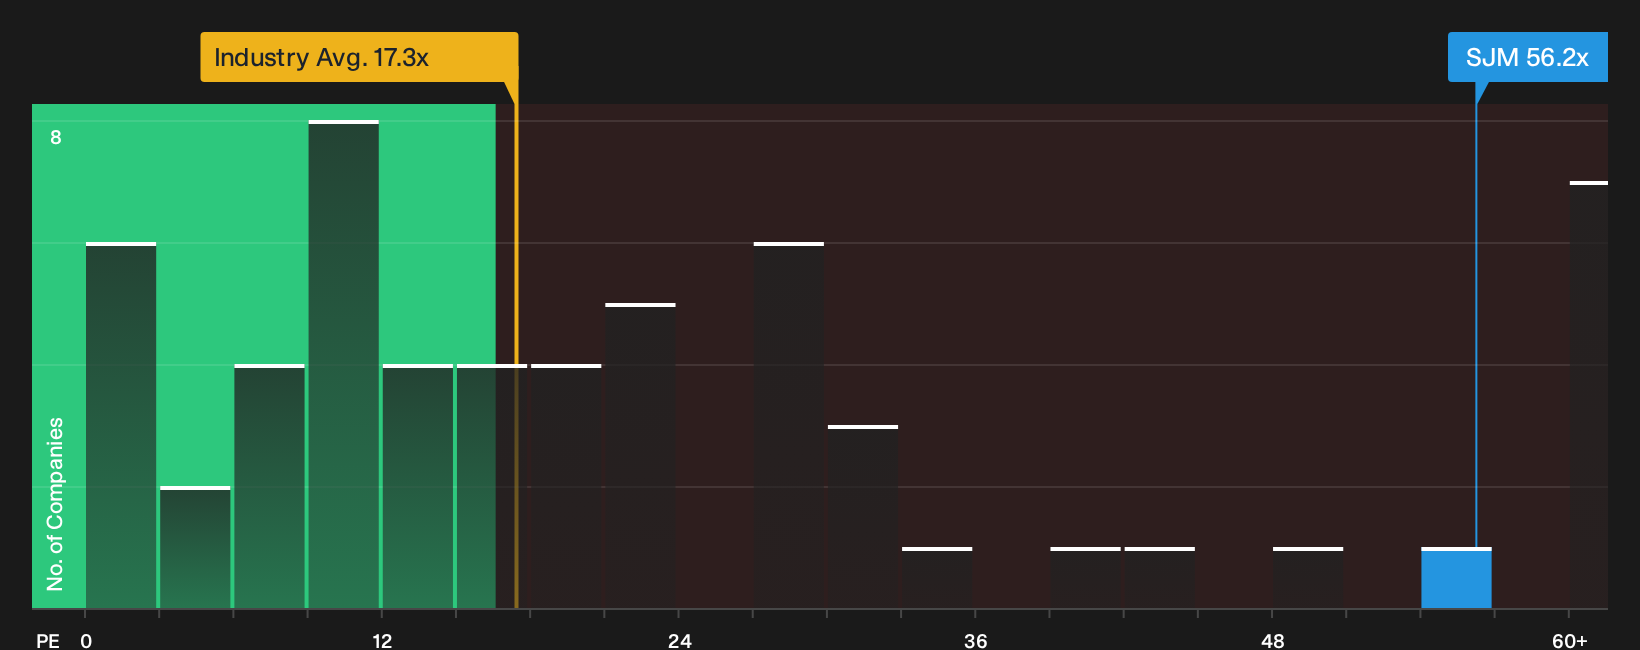
The P/E ratio suits J. M. Smucker because earnings are still the main anchor for how investors judge a branded food business. On this yardstick, the stock trades on about 56.2x earnings, which is much higher than the Food industry average of roughly 17.3x and well above the peer group near 20.5x. That scale of gap signals investors are paying a steep premium for each dollar of profit today.
The tailored fair P/E that blends J. M. Smucker's sector, margins, size and risk profile points to a meaningfully lower level than the current multiple. This tilts this framework toward an overvalued reading. Because the new Folgers functional coffee range has sharpened interest in the brand portfolio, the strong product story now comes with a P/E that already bakes in a lot of optimism compared with the modelled fair range. Explore the numbers behind J. M. Smucker's P/E valuation.
The J. M. Smucker Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for J. M. Smucker pick up where the P/E puzzle leaves off and explain what combination of future growth, margins and earnings power would need to occur for the shares to be worth materially more or materially less than today’s price on a reasoned view. Each narrative clearly sets out the assumptions behind its fair value so you can track those inputs against J. M. Smucker's reported results as they are released over time on the Community page.
Community narratives on J. M. Smucker split between investors who see more upside left and others who think expectations already look full.
Bull case: 15% undervalued
"Continued investments in advertising, innovation (e.g., new Milk-Bone PB Bites), and category expansion, especially in growing urban, convenience, and pet segments, are positioning the portfolio…"
Discover why this Narrative puts J. M. Smucker at 15% undervalued.
Bear case: roughly fairly valued
"Growth in at home coffee consumption and the expansion of Cafe Bustelo into new roast profiles and younger demographics support higher branded volume over time, however, the pass through nature of coffee pricing and recent tariffs can limit sustained margin expansion…"
Explore why this Narrative puts J. M. Smucker at roughly fairly valued.
One more J. M. Smucker factor that could change the story
Shareholders have pulled apart J. M. Smucker's earnings and product mix, but the people steering those decisions and how their paychecks are structured can tilt long term outcomes in ways the numbers alone will not show. See who runs J. M. Smucker and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com