
SM Energy (SM) Stock May Be Undervalued Following Rising Oil Prices
SM Energy has posted a sharp year to date gain, and the recent pullback leaves investors asking whether the current share price is still justified by what the business earns.
- With the stock up 73.1% year to date, every move in SM Energy now leans heavily on whether its earnings power can support this step up in market value.
- Recent sector strength linked to higher crude prices has lifted profit margins and free cash flow for producers like SM Energy, which can change how much investors are willing to pay for each dollar of earnings.
- Your read on SM Energy is one view; the desks covering it have another. See what analysts think SM Energy's shares could be worth.
The issue now is whether SM Energy's current valuation can be explained by its earnings profile after this strong run.
If you want to test the same earnings question that is now hanging over SM Energy across a wider field of opportunities, scan through 31 high quality undervalued stocks.
Is SM Energy a Bargain on Earnings?
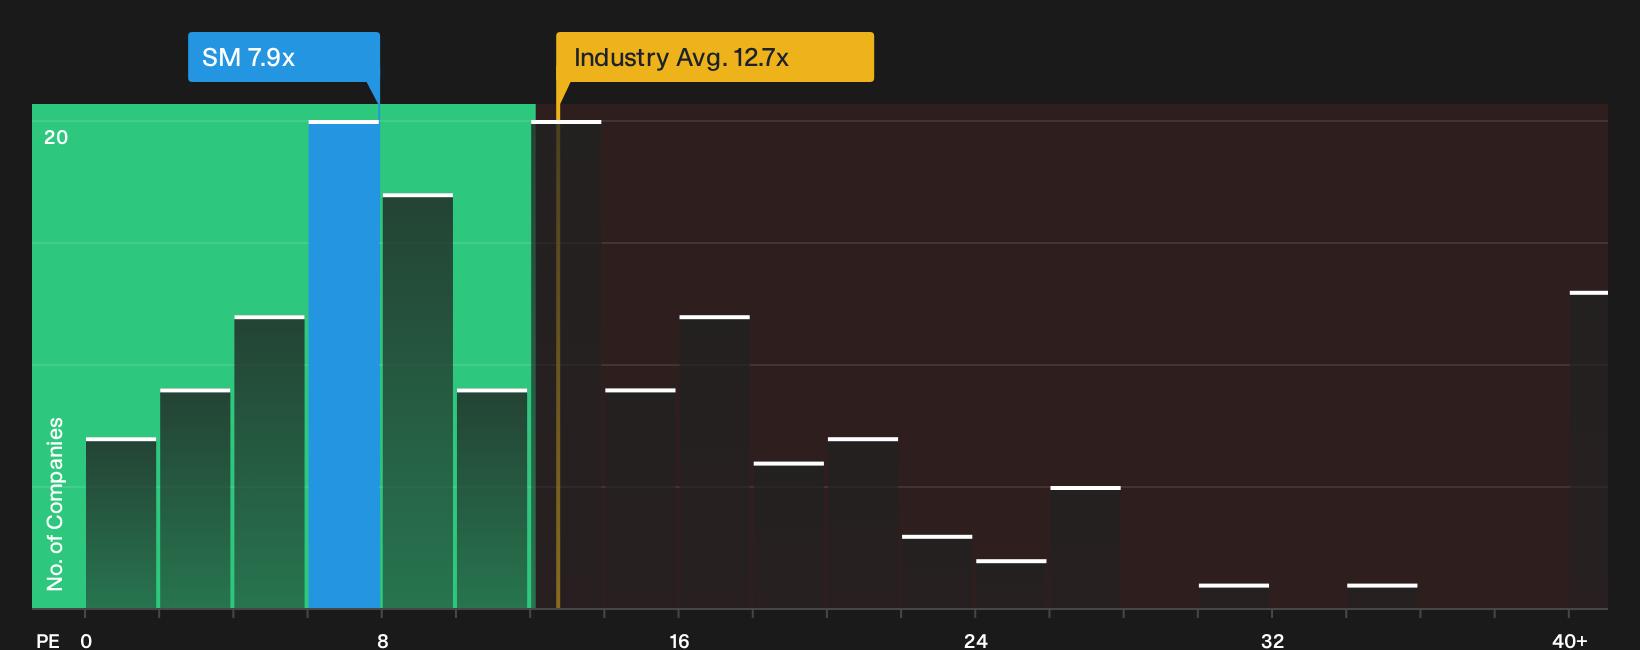
P/E fits SM Energy because earnings sit at the center of how investors usually value oil and gas producers. On this yardstick, the stock trades on a P/E of 7.9x, which is below both the Oil and Gas industry average of 12.7x and the broader peer group figure of 26.3x. The fair-value framework that looks at SM Energy's own growth profile, margins, size and risk suggests a higher multiple would be consistent with those fundamentals, so the current P/E points to an undervalued setup on this measure.
Because the recent sector rally and rising crude prices have already pushed SM Energy to a fresh high, this gap between the share price and the earnings-based benchmark matters even more. It suggests that, despite the strong run and improved sentiment, the market is still paying less for each dollar of earnings than those reference points imply. Explore the numbers behind SM Energy's P/E valuation.
The SM Energy Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle for SM Energy leaves off. They spell out which paths for SM Energy's future growth, profitability and earnings would line up with a meaningfully higher or lower share price than today. Each narrative ties its number to a specific view on how trends in growth, margins and risk could evolve, giving you something concrete to compare against as fresh results and sector data come through.
Community views on SM Energy are split between those who see more upside left and those who think expectations already look full.
Bull case: 20% undervalued
"Prudent balance sheet management with leverage near 1x, combined with a clear commitment to opportunistic share buybacks and capital discipline, enhances the outlook for EPS growth and shareholder returns…"
Discover why this Narrative puts SM Energy at 20% undervalued.
Bear case: roughly fairly valued
"While SM Energy has reduced net debt by about US$1.1b and targets low 1x leverage, it still carries one of the larger absolute debt loads among peers…"
Explore why this Narrative puts SM Energy at roughly fairly valued.
Before you focus on SM Energy's valuation, check what the red flags are saying
Price and earnings only tell part of the story for SM Energy, because internal checks have also picked up potential concerns that could influence how comfortable you feel owning the stock. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com