
Willis Lease Finance (WLFC) Stock Looks To Trade At A Discount On Earnings
Willis Lease Finance has delivered very strong multi year gains, yet the stock has recently pulled back and now trades around US$50.75. With that kind of history and a fresh round of capital coming in, the question for investors is whether the current share price still lines up with what its earnings can support.
- Over the past 5 years the stock has returned about 310%, which puts a lot of weight on whether the underlying earnings profile is strong enough to back up that performance.
- New preferred equity from the Development Bank of Japan and the planned engine repair center in Malaysia can influence future profitability and funding costs, which both feed directly into how investors value Willis Lease Finance on its earnings.
- There is a second opinion on Willis Lease Finance worth weighing. See what analysts think Willis Lease Finance's shares could be worth.
The issue now is whether those earnings, viewed through a simple Fair Ratio lens, are enough to justify where Willis Lease Finance is trading today.
If you want a wider watchlist of ideas built around similar earnings-focused questions, a good next step is to scan companies in the 31 high quality undervalued stocks.
Is Willis Lease Finance a Bargain on Earnings?
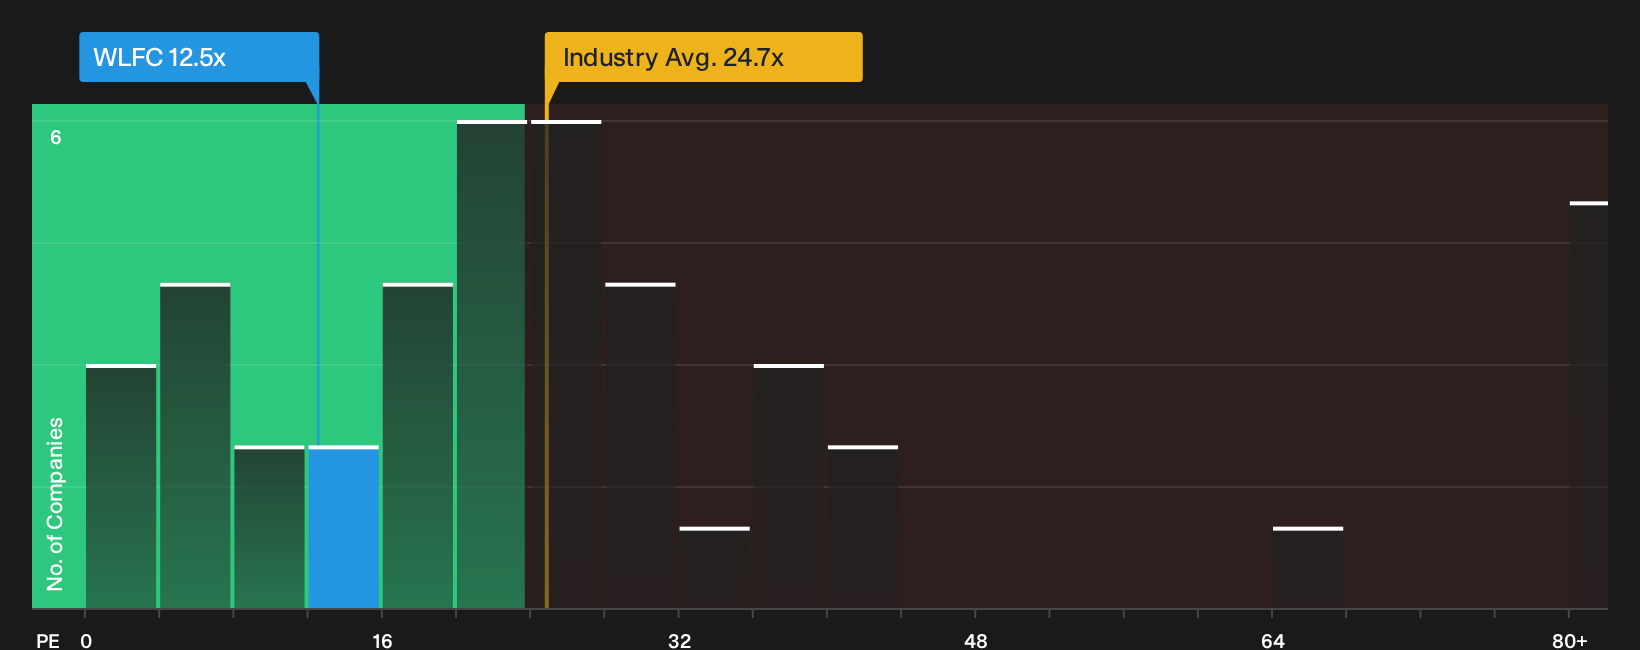
The P/E ratio is a useful way to frame Willis Lease Finance because earnings sit at the center of how investors typically value leasing and service businesses. At around 12.5x, the stock trades at roughly half the Trade Distributors industry average P/E of about 24.7x and far below the broader peer group near 61.3x. That is a wide gap for a company that reports positive earnings, and it raises the question of whether the current quote is baking in more risk or weaker staying power than the sector as a whole.
On a Fair Ratio view, which adjusts the P/E you might expect for Willis Lease Finance based on its growth profile, margins, size and risk mix, the present multiple screens below what that framework would suggest. Because the fresh preferred equity from the Development Bank of Japan strengthens the funding side of the business, the discount on this earnings multiple persists even after factoring in that extra capital support. For investors, the key judgment is whether that gap reflects genuine structural risk or a potential valuation opportunity on the current earnings power. Explore the numbers behind Willis Lease Finance's P/E valuation.
The Willis Lease Finance Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Willis Lease Finance pick up where the valuation puzzle leaves off by explaining in plain terms which paths for Willis Lease Finance's growth, margins and earnings would need to occur for the shares to be worth substantially more or less than they are today. Instead of providing a single output from a ratio or model, these scenarios describe the future that figure depends on so you can track how reality compares over time. They are available on Simply Wall St's Community page for you to explore alongside your own work.
A written, number driven view on Willis Lease Finance gives you a clear set of earnings and capital allocation assumptions to track as the new preferred stock investment, Malaysia repair center and recent fleet additions play through the financials. It turns the current share price into a set of testable expectations so you can see over time whether Willis Lease Finance's growth, margins and funding costs are moving in line with what the valuation implies.
Share your own Narrative for Willis Lease Finance and set out the assumptions behind your valuation.
One last check for Willis Lease Finance before you move on
Price and earnings only tell part of the story for Willis Lease Finance, because the people allocating capital and how they are rewarded can tilt shareholder outcomes in subtle ways that are easy to miss. See who runs Willis Lease Finance and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com