
Capital Southwest (CSWC) After SBA Leverage Approval, Does The Valuation Case Still Hold?
Capital Southwest (CSWC) just received U.S. Small Business Administration approval to lift SBIC II’s leverage commitment from $175 million to $250 million, thereby expanding available funding for its lower middle market lending approach.
Recent trading has been choppy for Capital Southwest, with the share price down 8.44% over the past month and 3% over 90 days. However, the year-to-date share price return of 4.62% and 1-year total shareholder return of 19.35% suggest longer term momentum remains positive as investors weigh this fresh SBA leverage approval against earlier gains.
Scan other business development companies deploying fresh capital into niche lending opportunities with the hand picked 17 high quality undiscovered gems.
So after a choppy few months and fresh SBA capacity in hand, is Capital Southwest still pricing in more room for upside, or have most of the easy gains already been claimed as it trades near analysts’ targets and intrinsic estimates?
Most Popular Narrative: 6% Undervalued
Capital Southwest’s most followed narrative pegs fair value at $24.90, a touch above the last close of $23.32, which points to modest upside being priced into the story.
Recent approval of the second SBIC license and expanded credit facility provide low-cost, flexible capital, enabling disciplined portfolio expansion and scale benefits that should enhance earnings and net margins.
Conservative leverage, disciplined first-lien senior-secured underwriting, and broad portfolio diversification reduce credit risk and earnings volatility, improving the sustainability of margins and regular/supplemental dividends.
See why 35 investors see Capital Southwest as 6% undervalued.
Result: Fair Value of $24.90 (UNDERVALUED)
Still, the Capital Southwest story carries pressure points, including tighter loan pricing and regular equity issuance. These factors could squeeze returns and weaken the current undervaluation case.
Find out about the key risks to this Capital Southwest narrative.
Another View: Capital Southwest Through Market Multiples
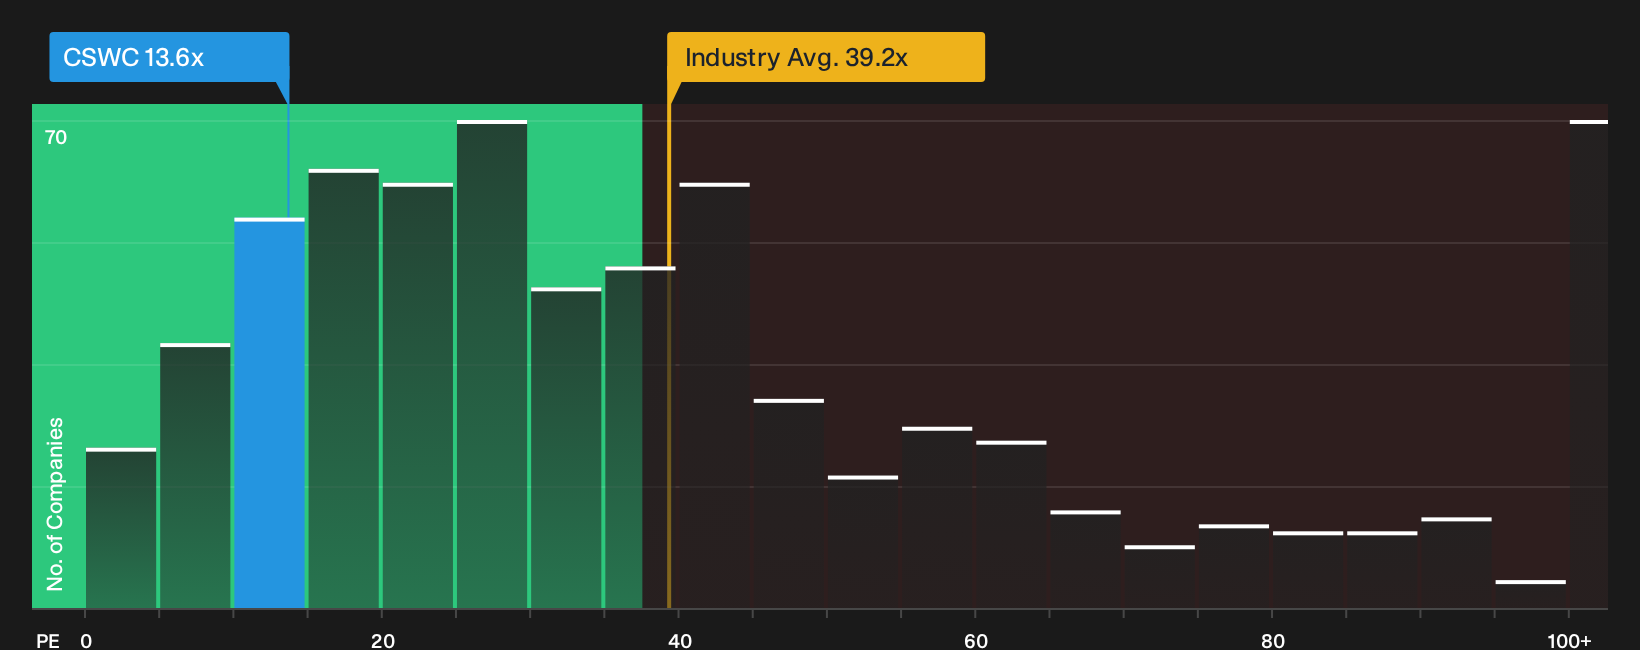
While the SWS DCF model points to Capital Southwest trading below an estimated future cash flow value of $29.42, the market is sending a more cautious signal. At a P/E of 13.6x, the stock trades above its peer average of 11.7x and also above a fair ratio of 12.9x, which implies some valuation premium is already built in. If sentiment swings back toward that fair ratio, how much margin of safety do you really have at today’s price?
For a closer look at how this valuation gap could matter for future returns, see what the numbers say in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Capital Southwest’s valuation and risk profile on your mind today. Act quickly, examine the bullish and bearish angles yourself, then weigh up the 3 key rewards and 3 important warning signs.
Looking for more Capital Southwest investment ideas?
Do not stop with Capital Southwest. Broaden your watchlist now, or you risk missing practical opportunities that better fit your risk, income, or value goals.
- Target resilient balance sheets and steadier fundamentals by scanning companies on the list of solid balance sheet and fundamentals (25 results).
- Hunt for pricing gaps where quality might outshine expectations using the 31 high quality undervalued stocks.
- Prioritise stability and income potential by reviewing companies across the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com