
Genesis Energy (GEL) Could Be 71% Below Fair Value On Mixed Valuation Signals
Genesis Energy (GEL) has slipped over the past month and the past three months, leaving the stock down about 13% over the past year despite a higher three-year return.
Recent trading has leaned weaker for Genesis Energy, with a 7 day share price return of down 5.6% and a 30 day share price return of down 14%. However, the 3 year total shareholder return of about 60% signals that longer term momentum is still positive.
Scan how Genesis Energy stacks up against other income and infrastructure plays by reviewing our hand picked list of 6 dividend fortresses.
Bulls see Genesis Energy’s pullback as a discount on a business with solid multi year returns. Bears point to recent price weakness and revenue contraction. Which side do the current valuation markers support?
Price-to-Earnings of 68.7x: Is it justified?
Valuation gets tricky for Genesis Energy because the units trade on a P/E of 68.7x, which is far richer than many investors would expect for a midstream partnership.
The P/E multiple compares the current unit price to earnings per unit. It reflects how much the market is paying today for each dollar of recent profit. For a business like Genesis Energy that has only recently moved into profitability and carries meaningful debt, a high P/E can say more about accounting noise and one off gains than about a stable earnings base.
Genesis Energy’s P/E of 68.7x sits well above the peer average of 16.3x and is also far above the broader US Oil and Gas industry on 12.7x. That is a strong signal that the units are expensive when measured against both close comparables and the wider sector on this metric, even before factoring in the large one off gain flagged in recent results.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 68.7x (OVERVALUED)
Still, the recent revenue contraction and high P/E leave Genesis Energy exposed if earnings normalise at a lower level or if debt costs limit flexibility.
Find out about the key risks to this Genesis Energy narrative.
Another View on Genesis Energy’s Value
The first lens flags Genesis Energy as expensive on a 68.7x P/E, yet the SWS DCF model points in the opposite direction. On that cash flow view, units trading at $13.82 are 71.2% below an estimated fair value of $47.93. That is a big gap. Is it a genuine opportunity or a sign the model is too optimistic?
Look into how the SWS DCF model arrives at its fair value.
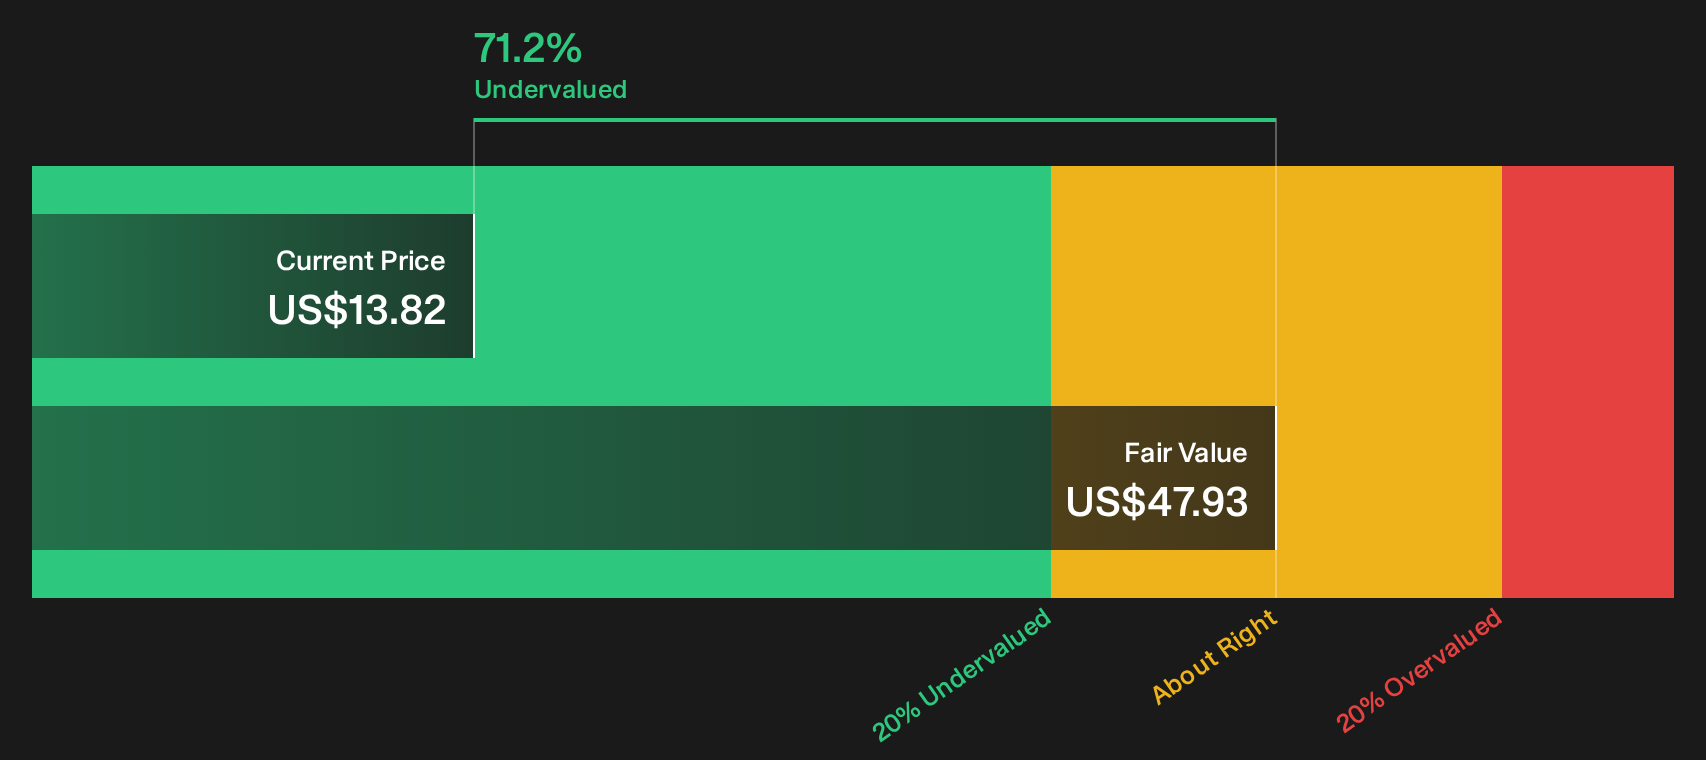
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Genesis Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Genesis Energy can either paralyse you or push you to dig into the numbers yourself and move with conviction. To weigh both sides clearly, start with the 3 key rewards and 3 important warning signs.
Looking for more Genesis Energy investment ideas?
If Genesis Energy has you reassessing your watchlist, now is the moment to widen your search and pressure test your next move with fresh opportunities.
- Target potential mispricing by scanning a 31 high quality undervalued stocks that combine quality fundamentals with pricing that may not fully reflect their underlying strength.
- Prioritise resilience first and sift through a 32 resilient stocks with low risk scores that focus on sturdier balance sheets and more measured risk profiles.
- Hunt for overlooked potential and comb through a 17 high quality undiscovered gems that screens for solid businesses that many investors might still be ignoring.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com