
NVIDIA And 2 Other Undervalued Stocks To Watch
U.S. Treasury yields recently reached a 25 year high, with the 10 year yield now above the S&P 500 earnings yield. When safer government bonds offer equity like returns, many investors shy away from stocks that rely on distant profits. That shift can leave cash rich businesses priced cheaply. This article highlights three such companies where discounted cash flow analysis indicates potential mispricing and patient value hunters may find opportunity.
The three companies below are only a sample set, while the full screen surfaced 208 more businesses with cash flow stories and potential mispricing that this article does not cover. To identify and analyze those candidates in detail, head straight to the Undervalued Stocks Based On Cash Flows screener
NVIDIA (NVDA)
NVIDIA is best known for chips that power AI data centers, gaming PCs, and automotive systems. The Compute & Networking division, at about US$275.4b in revenue, is far larger than the US$27.6b Graphics segment and is a major contributor to the firm’s US$5,526.3b market value.
NVIDIA sits at the center of the cash-flow story in this screener because its AI-focused infrastructure is designed to generate recurring returns from data center clients. This makes any crack in its competitive moat especially important for long term investors to understand.
"Uptake of an open-source/cheaper/better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
Future cash flows rest on whether one quiet shift in the AI software stack leaves NVIDIA’s current pricing power and profitability intact or not.
That hinges on how durable you think Nvidia’s moat really is. Read the full narrative for NVIDIA to see how cash flows could evolve if the AI stack keeps shifting.
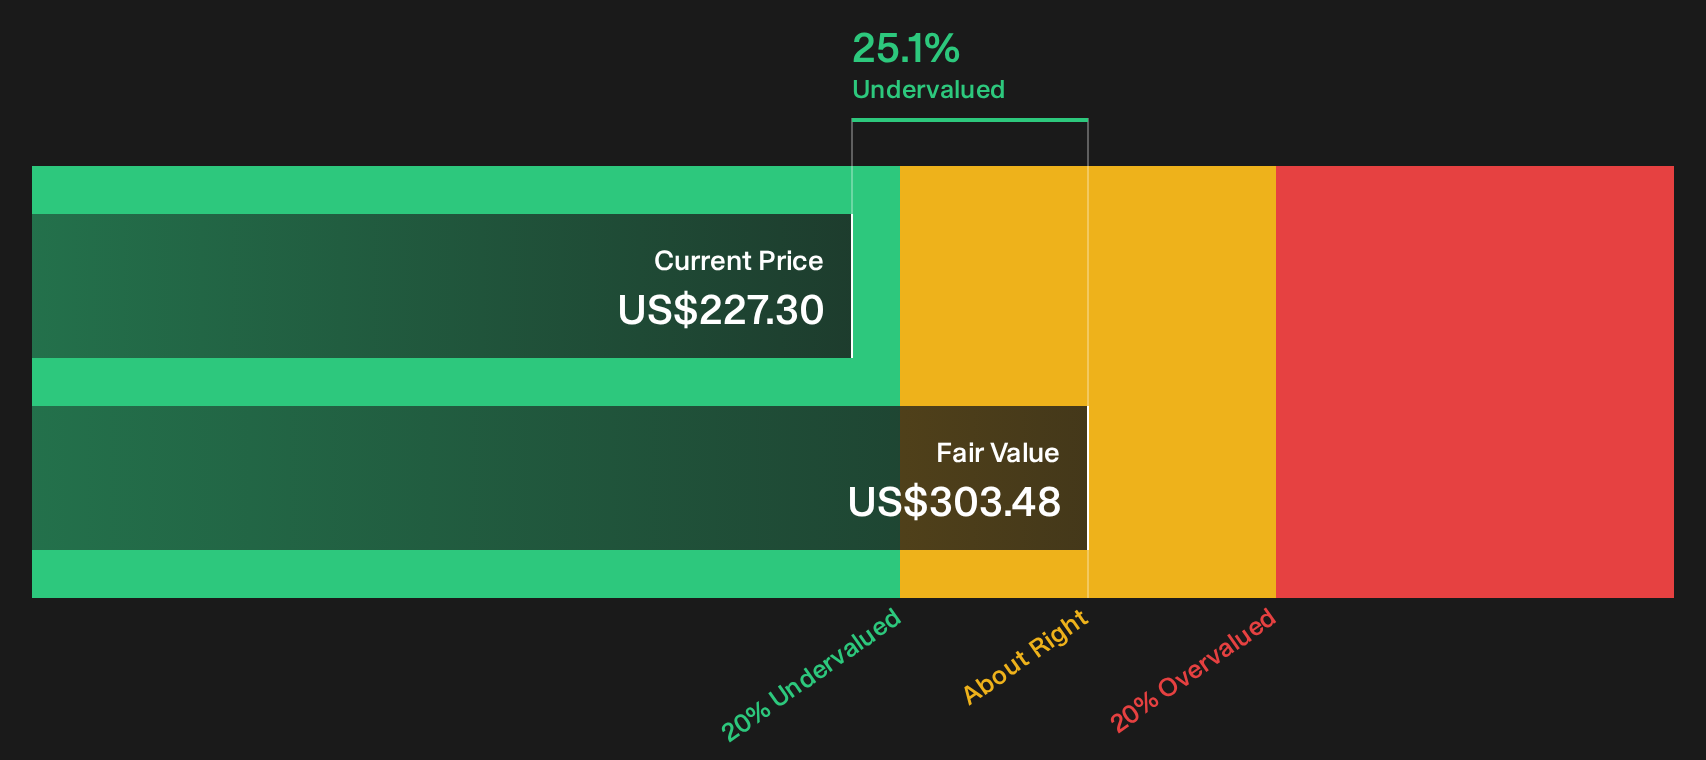
Broadcom (AVGO)
Broadcom ties into this cash-flow screen through its mix of semiconductor hardware and infrastructure software, where VMware, mainframe tools, and cybersecurity subscriptions feed recurring income that can anchor discounted cash flow value for patient investors watching both sides of the business.
Broadcom Inc. runs a large semiconductor hardware arm that generated about US$59.4b in Semiconductor Solutions revenue alongside roughly US$29.7b from Infrastructure Software, and the combined US$1.67t market value reflects how investors view that blend of chips and cash-rich subscriptions.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
What really matters next is how one quiet pressure on those software cash flows shapes the future path of margins and growth.
That pressure point is exactly what the full narrative for Broadcom unpacks, revealing where Broadcom’s cash engine could accelerate, stall, or quietly decouple from expectations.
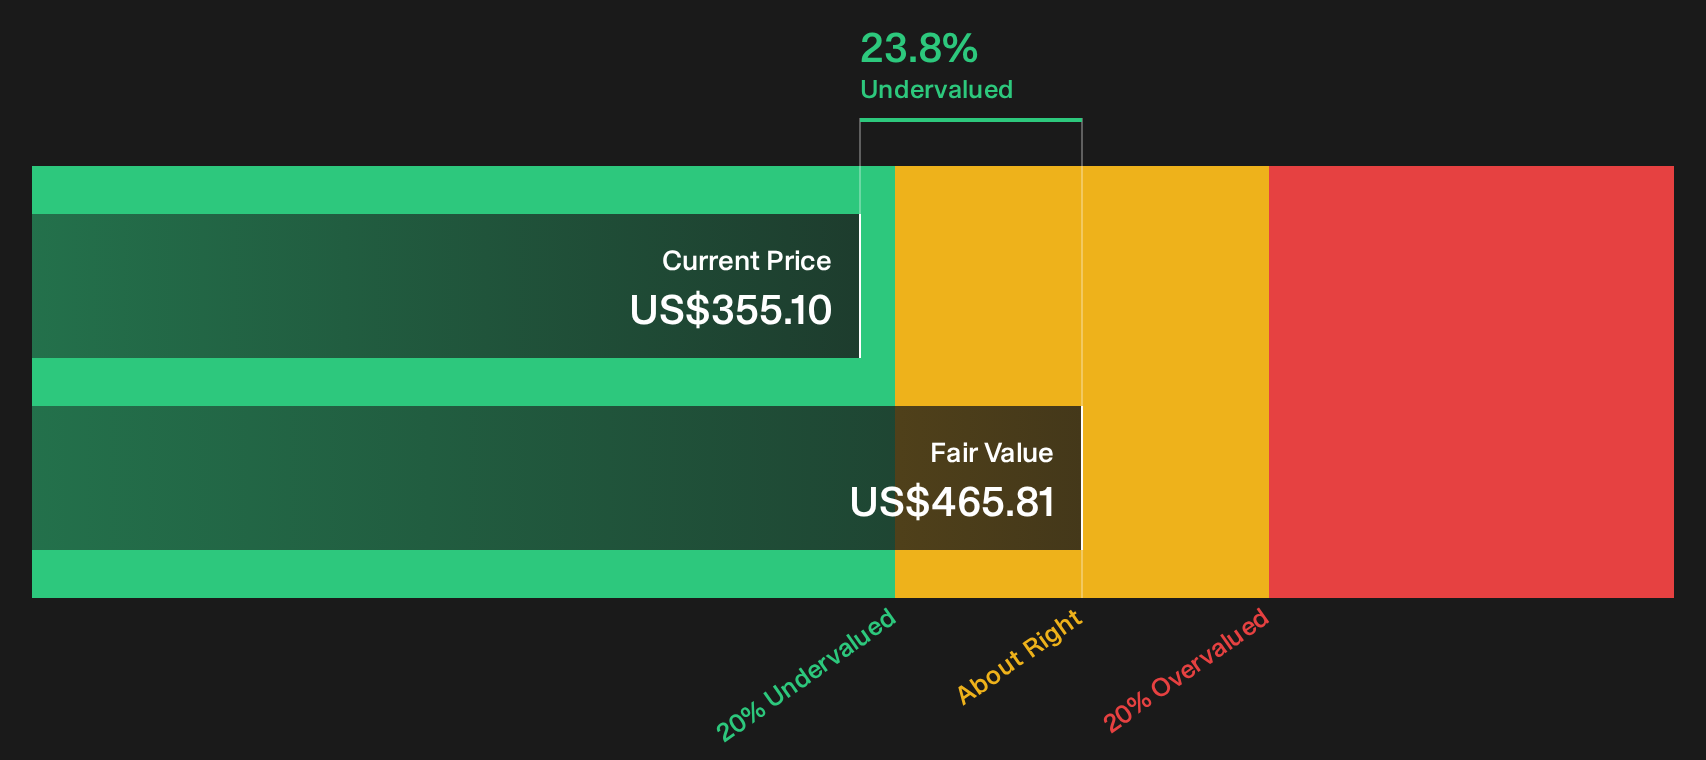
Alphabet (GOOGL)
Alphabet runs the Google Search, YouTube, Android and subscription products most users know, while also operating Google Cloud’s AI infrastructure and Vertex AI platform that tie directly into this cash flow themed screen. Google Services generated about US$367.1b in revenue, Google Cloud US$77.6b and Other Bets US$1.5b, with the group valued at roughly US$4,172.0b.
Alphabet gives this cash-flow screen a different flavor, since its ad empire already throws off large amounts of cash while Google Cloud’s AI subscriptions and usage-based services offer a second, more clearly recurring layer.
"Google Cloud has gone from “meh” to money-maker. • Now #3 globally behind AWS and Azure, with over 11% market share.
What really matters for Alphabet now is how one quiet shift in how customers commit to that AI-heavy cloud backlog ultimately shapes long term cash returns.
If that cloud cash machine really shifts, the full narrative for Alphabet shows how Alphabet’s AI strength, ad engine and capital returns could still accelerate beyond today’s assumptions.
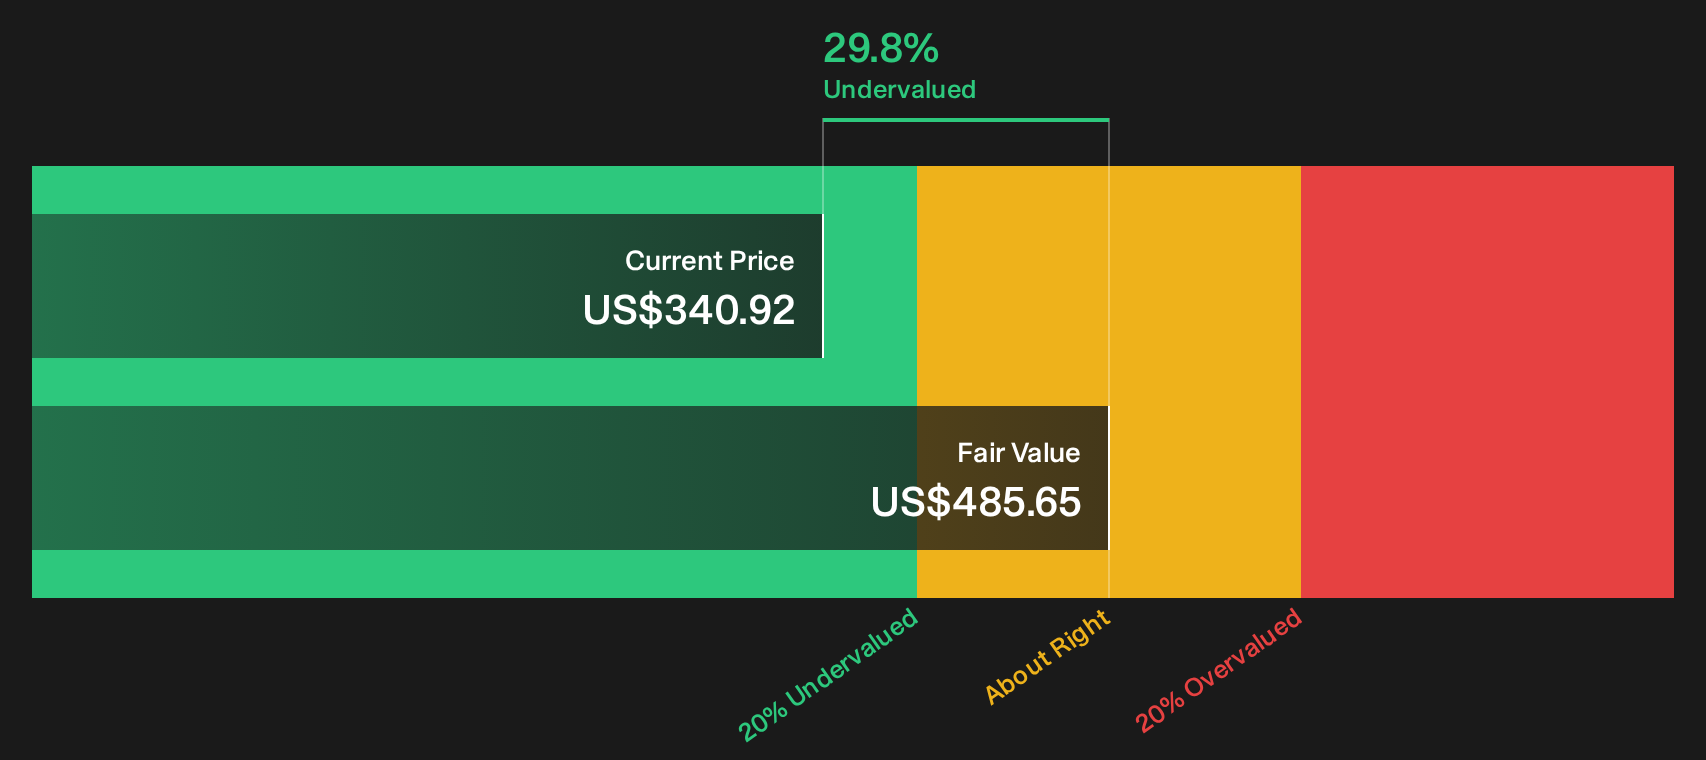
Seeking Fresh Alternatives Before They Fly
Market momentum shifts fast. Breakout stories can get caught by the crowd while prices are still under the radar for now. Scan fresh ideas before they start flying and consider them early.
- Spot resilient cash machines that hold up when others wobble by scanning a curated 32 resilient stocks with low risk scores built to highlight stability-backed return potential.
- Review a focused pool of 37 profitable AI stocks that aren't just burning cash where strong cash generation already supports the AI story.
- Track the infrastructure behind future demand shifts through a targeted set of 39 power grid technology and infrastructure stocks that connect real assets to long term electrification themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com