
Ramelius Resources (ASX:RMS) Could Be 21% Undervalued As 2027 Guidance Lands
Ramelius Resources 2027 production guidance
Ramelius Resources (ASX:RMS) has set production guidance for fiscal 2027 at 205,000 to 225,000 ounces of gold, with all in sustaining costs forecast between A$2,150 and A$2,350 per ounce.
At A$3.86, Ramelius Resources has given investors a 33.56% 90 day share price return, while the year to date share price is down 8.75%. That mix of shorter term momentum and a 3 year total shareholder return of about 19x highlights a stock where expectations and perceived risk can shift quickly around fresh guidance like this.
Scan the gold patch for other producers with similar production stories to Ramelius Resources by sizing up the 36 elite gold producer stocks alongside this new 2027 guidance.
The share price has risen sharply over the past 90 days, yet still trades well below both analyst targets and intrinsic estimates. Where does fair value for Ramelius Resources actually sit within that range, given this new guidance backdrop?
Most Popular Narrative: 21% Undervalued
Ramelius Resources is framed as undervalued in the most followed narrative, with an implied fair value of about A$4.89 against the A$3.86 close. That gap is being tested by this fresh 2027 production guidance.
The aggressive reserve/resource expansion strategy via a doubled exploration budget and integration of new assets (Spartan, Dalgaranga) is stoking expectations of significant long-term production growth and sustained increases in revenue and earnings. These expectations may be viewed as potentially justifying a premium valuation that may not materialize if exploration or integration underdelivers.
Anticipation of strong synergies and cost efficiencies from the large-scale Spartan acquisition and operational optimization at Mt Magnet and Dalgaranga could lead to market projections of structurally higher operating margins, despite potential underappreciation of integration risks and future capital requirements.
See why 45 investors see Ramelius Resources as 21% undervalued.
Result: Fair Value of A$4.89 (UNDERVALUED)
Still, the narrative can unravel quickly if the integration of Spartan and Dalgaranga disappoints, or if expected cost efficiencies and margin expansion prove harder to deliver.
Find out about the key risks to this Ramelius Resources narrative.
Another View on Ramelius Resources Valuation
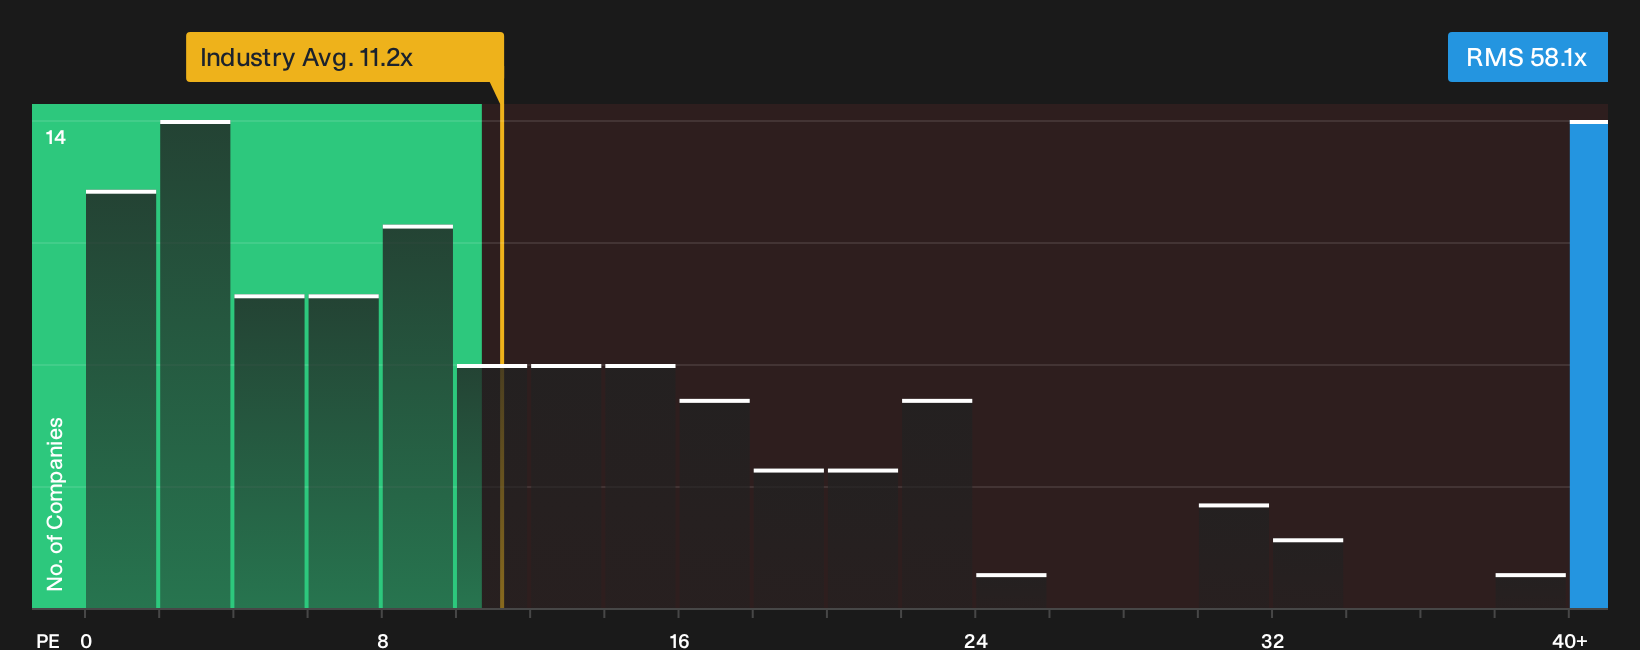
Fair value screens as supportive in the narrative model, yet Ramelius Resources looks expensive on earnings. The stock trades on a 58.1x P/E, compared with 16x for peers and a fair ratio of 29.6x. That kind of gap can reward patience or punish it. Which side do you think it represents?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of risks and upside around Ramelius Resources feels finely balanced, move quickly. Look through the full detail, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ramelius Resources?
Ramelius Resources might be front of mind today, but your next edge could come from widening the search to other high quality opportunities before the crowd spots them.
- Target potential mispricings by scanning companies that score well on quality yet still appear cheap through the 5 high quality undervalued stocks.
- Lock in consistency by focusing on businesses that pair income potential with balance sheet strength using the 3 dividend fortresses.
- Surface fresh opportunities before they hit the spotlight by searching the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com