
Is Interpump Group (BIT:IP) Undervalued On Its FTSE All World Index Exit?
Interpump Group (BIT:IP) was removed from the FTSE All-World Index (USD) on 19 September 2026. This type of index change can affect demand from institutional investors and index-tracking funds.
At around €36.0 per share, Interpump Group has seen its 90 day share price return of 6.32% clash with a weaker year to date share price return. The 1 year total shareholder return has declined 6.68%, suggesting recent momentum is trying to rebuild after a tougher stretch as index removal reshapes who holds the stock.
Compare how Interpump Group’s index exit lines up with other industrial plays by scanning a curated list of list of solid balance sheet and fundamentals (204 results) that may be less exposed to benchmark reshuffles.
Interpump Group now trades around €36 after a forced index exit, which raises a simple tension. Is this price already fair, or does patience offer a better entry before the next stage of the valuation story?
Most Popular Narrative: 21% Undervalued
Interpump Group’s most followed narrative sets fair value at €45.56 per share, above the recent €36 price. This frames the current index-driven weakness against a higher long term valuation anchor built on earnings and margin forecasts.
The company's above-expectation margin improvement (e.g., Water-Jetting EBITDA up 34% on 19% revenue growth) demonstrates success in shifting toward higher-value, technologically advanced product categories, suggesting potential for sustainable margin expansion and improved return on capital. Continued recovery signals in core Hydraulics markets, combined with completed restructuring initiatives (such as at White Drive) and ongoing investment in proprietary innovation, point toward operational normalization and a pathway to improved profitability, reducing earnings drag from underperforming segments.
See why 6 investors see Interpump Group as 21% undervalued.
Result: Fair Value of €45.56 (UNDERVALUED)
Still, parts of the Interpump Group story can break. A fragile Hydraulics recovery and softer North American demand could unsettle margins and challenge that €45.56 anchor.
Find out about the key risks to this Interpump Group narrative.
Another View: Interpump Group Through The Cash Flow Lens
The analyst narrative around Interpump Group leans on earnings and a €45.56 fair value, yet our DCF model tells a different story. On that framework, the share price of about €36 sits above an estimated future cash flow value of €31.87, which tilts the picture toward overvaluation risk instead of a simple bargain. Which yardstick do you trust more when cash and earnings disagree?
Look into how the SWS DCF model arrives at its fair value.
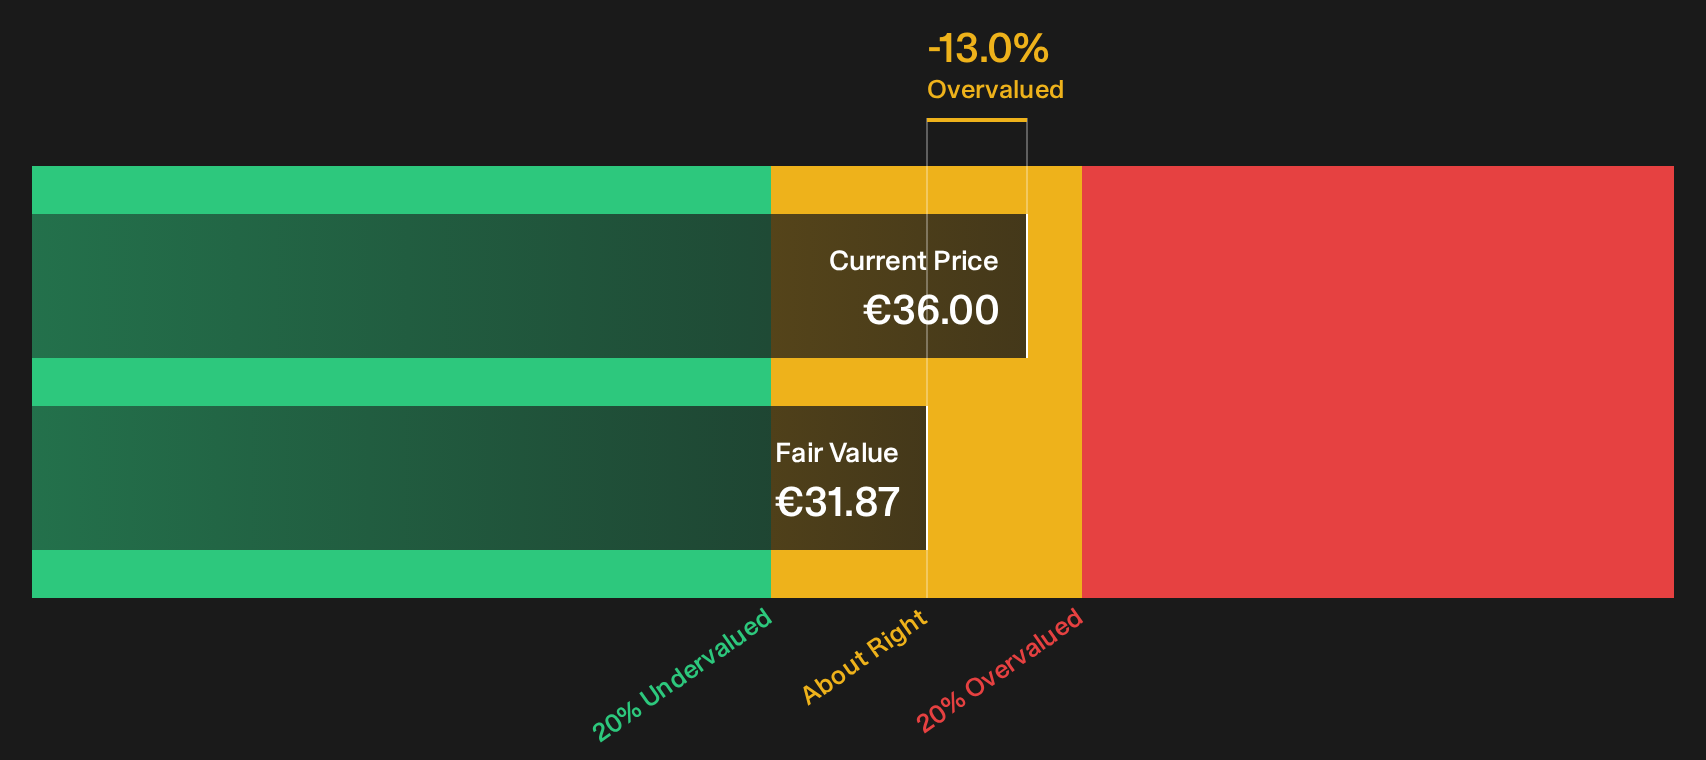
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Interpump Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between Interpump Group’s valuation stories and the recent index exit effect is common. Move quickly and stress test the numbers yourself using 3 key rewards.
Looking For More Interpump Group Investment Ideas?
If Interpump Group has your attention after this index exit and valuation split, do not stop here. Use the Simply Wall Street Screener to line up your next candidates before the market moves without you.
- Target potential upside by scanning for companies that combine strong fundamentals with attractive pricing through our 197 high quality undervalued stocks.
- Protect your downside by filtering for businesses with sturdier financial footing using the 227 resilient stocks with low risk scores.
- Get ahead of the crowd by reviewing a 620 high quality undiscovered gems that the wider market may not be focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com