
Why Amprius Technologies (AMPX) Is Getting Attention Today
Amprius Technologies (AMPX) came into focus after securing a grant of up to $75 million from the U.S. Department of War to convert a domestic battery production line for unmanned aerial systems.
Amprius Technologies shares have recently given back some of the initial grant-driven jump, with a 7 day share price return down 4.51% and a 90 day share price return down 29.87%. However, the year to date share price return is up 9.04% and the 3 year total shareholder return of 89.46% points to longer term momentum that has been much stronger than the latest pullback.
Scan defense-linked battery plays moving on fresh contracts and funding by comparing Amprius Technologies with our curated list of 39 power grid technology and infrastructure stocks
Amprius Technologies now trades at a steep discount to both analyst targets and some fair value estimates, even after the grant news lift. Is that a bargain, or is the market correctly pricing execution risk and losses?
Most Popular Narrative: 57% Undervalued
At a last close of $9.53 versus a narrative fair value of $22.13, Amprius Technologies is framed as heavily discounted, with that gap resting on very optimistic revenue and earnings assumptions.
Ongoing investment in automation and manufacturing capacity (supported by government contracts like the $10.5M Defense Innovation Unit award) positions Amprius to capture a larger share of future high-margin opportunities in defense and critical infrastructure, enhancing both revenue visibility and earnings stability.
First-mover advantage, validated technology, and policy tailwinds for domestic and friendly-nation battery sourcing (NDAA-compliant, U.S. DoD engagement) position the company to secure long-term supply agreements, helping transition to recurring, higher-margin revenue streams and improving forward earnings quality.
See why 105 investors see Amprius Technologies as 57% undervalued.
Under this widely followed view, the gap between price and estimated worth reflects expectations that Amprius Technologies can grow revenue at 66.3% a year, lift margins from a current loss profile toward a 12.9% net profit margin, and support a future P/E multiple around 93x on projected 2029 earnings. That outlook also bakes in ongoing share issuance of roughly 7% a year and applies a 9.21% discount rate, so a lot of the valuation hinges on both strong execution and investors continuing to pay a premium for that growth story.
Result: Fair Value of $22.13 (UNDERVALUED)
Still, Amprius Technologies could see this upbeat narrative crack if scaling silicon anode production proves slower or if equity dilution from fresh capital needs accelerates.
Find out about the key risks to this Amprius Technologies narrative.
Another View: Multiples Put Amprius Technologies In A Different Light
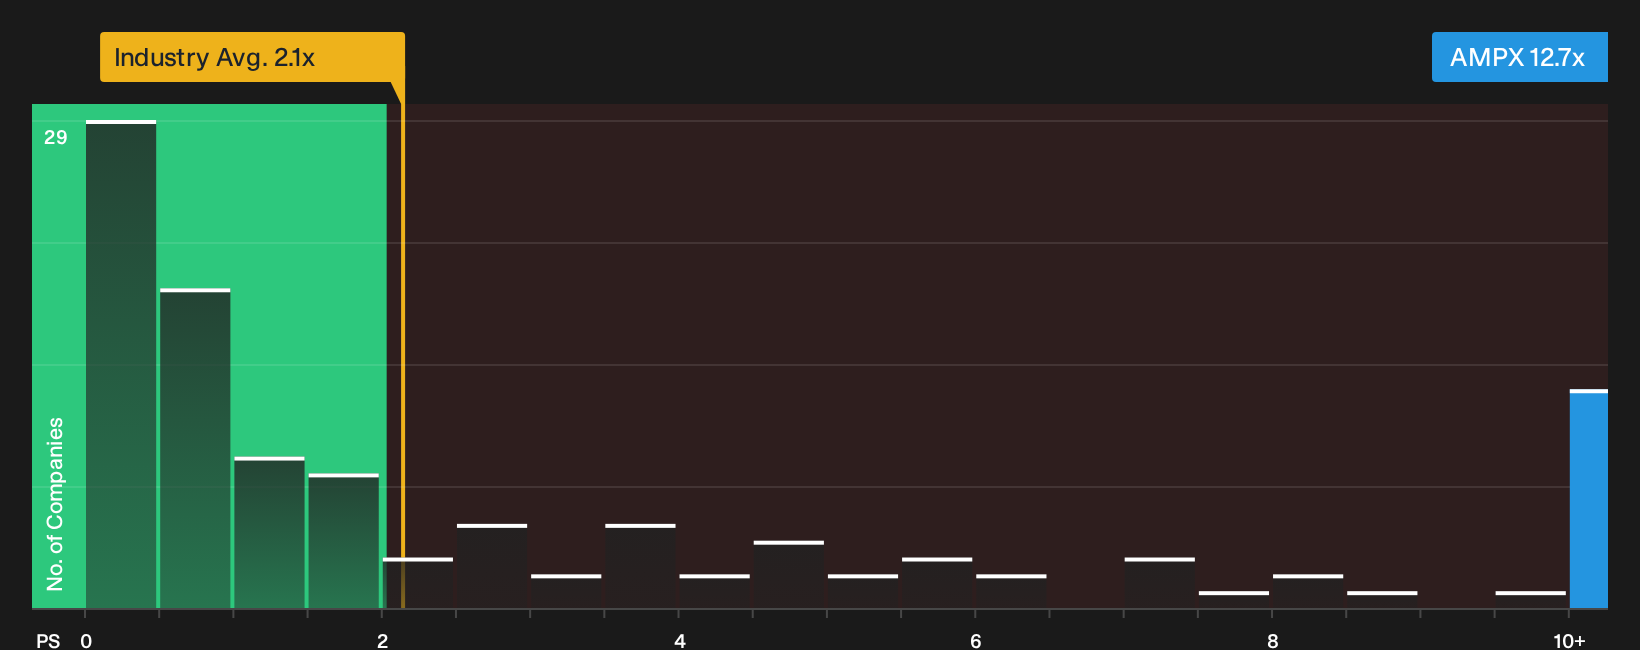
The big fair value gap that paints Amprius Technologies as heavily undervalued on growth assumptions looks very different when you switch to a simple sales multiple. On a P/S ratio of 12.7x versus 8.7x for peers and 2.1x for the wider US Electrical group, the stock screens as expensive, not cheap, and the fair ratio of 4.9x highlights how far sentiment could swing if expectations cool. Which lens do you trust more when real cash results start to matter?
That disconnect is exactly why many investors cross check story-driven targets against hard comparison numbers before committing fresh capital to high growth situations like Amprius Technologies. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Amprius Technologies story so far. Act quickly, review the underlying metrics, and evaluate the balance of 3 key rewards and 3 important warning signs
Looking For More Ideas Beyond Amprius Technologies?
If Amprius Technologies has your attention, do not stop here. Use fresh ideas from the Simply Wall St Screener to keep your opportunity set wide and focused.
- Target potential mispricing by scanning a curated pool of companies that combine quality, cash flow strength and attractive pricing through the 31 high quality undervalued stocks.
- Prioritise resilience by assessing businesses with stronger finances using a focused list of solid balance sheet and fundamentals (25 results) that can help you filter out fragile balance sheets quickly.
- Look for lesser known stocks with strong fundamentals using our hand picked list of 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com