
Is Novanta (NOVT) Above Fair Value After A 41% Run?
Novanta has delivered a strong share price gain over the past year, which naturally puts a spotlight on whether that move is supported by the earnings power of the business. With the stock now trading around recent highs, the core question is how much of its earnings profile is already reflected in the current valuation.
- The share price is up 41.0% over the past year, which raises the stakes on whether today’s valuation is still aligned with the company’s underlying earnings.
- The business leans on specialized technology and components that can support pricing power and margins, so investors are effectively betting that this earnings base can be sustained and potentially expanded over time.
- There is a second opinion on Novanta worth weighing. See what analysts think Novanta's shares could be worth.
The issue now is whether the current US$141.22 share price is appropriately grounded in Novanta’s earnings profile or asking too much of its future profit stream.
If you want to cross check Novanta against other opportunities where earnings are a key filter, a focused stock screen is a useful next step through 31 high quality undervalued stocks
Does Novanta Look Pricey on Earnings?
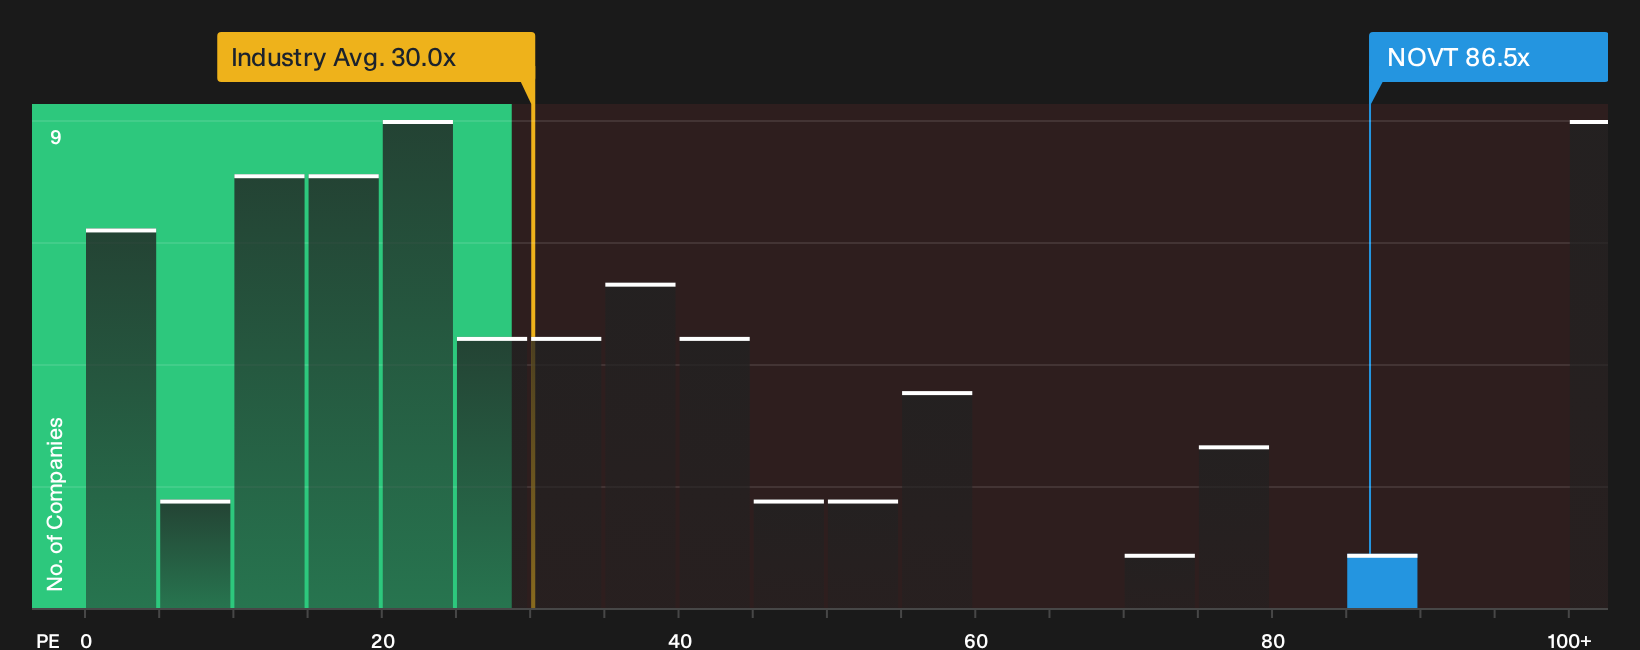
The P/E multiple fits Novanta because earnings are a key reference point for how investors weigh its specialized technology exposure. At around 86.5x earnings, the stock trades well above the wider electronic industry average of roughly 30.0x, which already reflects many established operators in the sector.
Compared with closer peers on about 49.4x, Novanta also carries a clear premium. The Fair Ratio model, which adjusts for the company’s own growth profile, profitability, size and risk, points to a lower P/E than where the shares change hands today, so on this framework the stock screens as overvalued on earnings. For anyone considering Novanta at current levels, the key question is whether the quality and durability of its profit stream are strong enough to keep justifying such a rich headline multiple relative to both peers and the tailored fair range the model suggests. Explore the numbers behind Novanta's P/E valuation.
The Novanta Narrative: What Would Justify Today's Price?
Narratives for Novanta pick up where the valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on Simply Wall St’s Community page. Each scenario links a fair value estimate to a specific mix of potential catalysts and downside risks, so you can track which storyline is unfolding over time.
One of the top community narratives on Novanta: 27% undervalued
"Expansion of minimally invasive and robotic surgery, together with the Riverpoint Medical acquisition, increases Novanta's mix of repeat consumables that can support more resilient revenue..."
Discover why this Narrative puts Novanta at 27% undervalued.
One more angle on Novanta that could change the story
Numbers only tell part of the story for Novanta, because the people steering the business and how their incentives are set can heavily influence what happens next for shareholders. See who runs Novanta and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com