
Does Leadership Shakeup Change The Bull Case For AIG Stock?
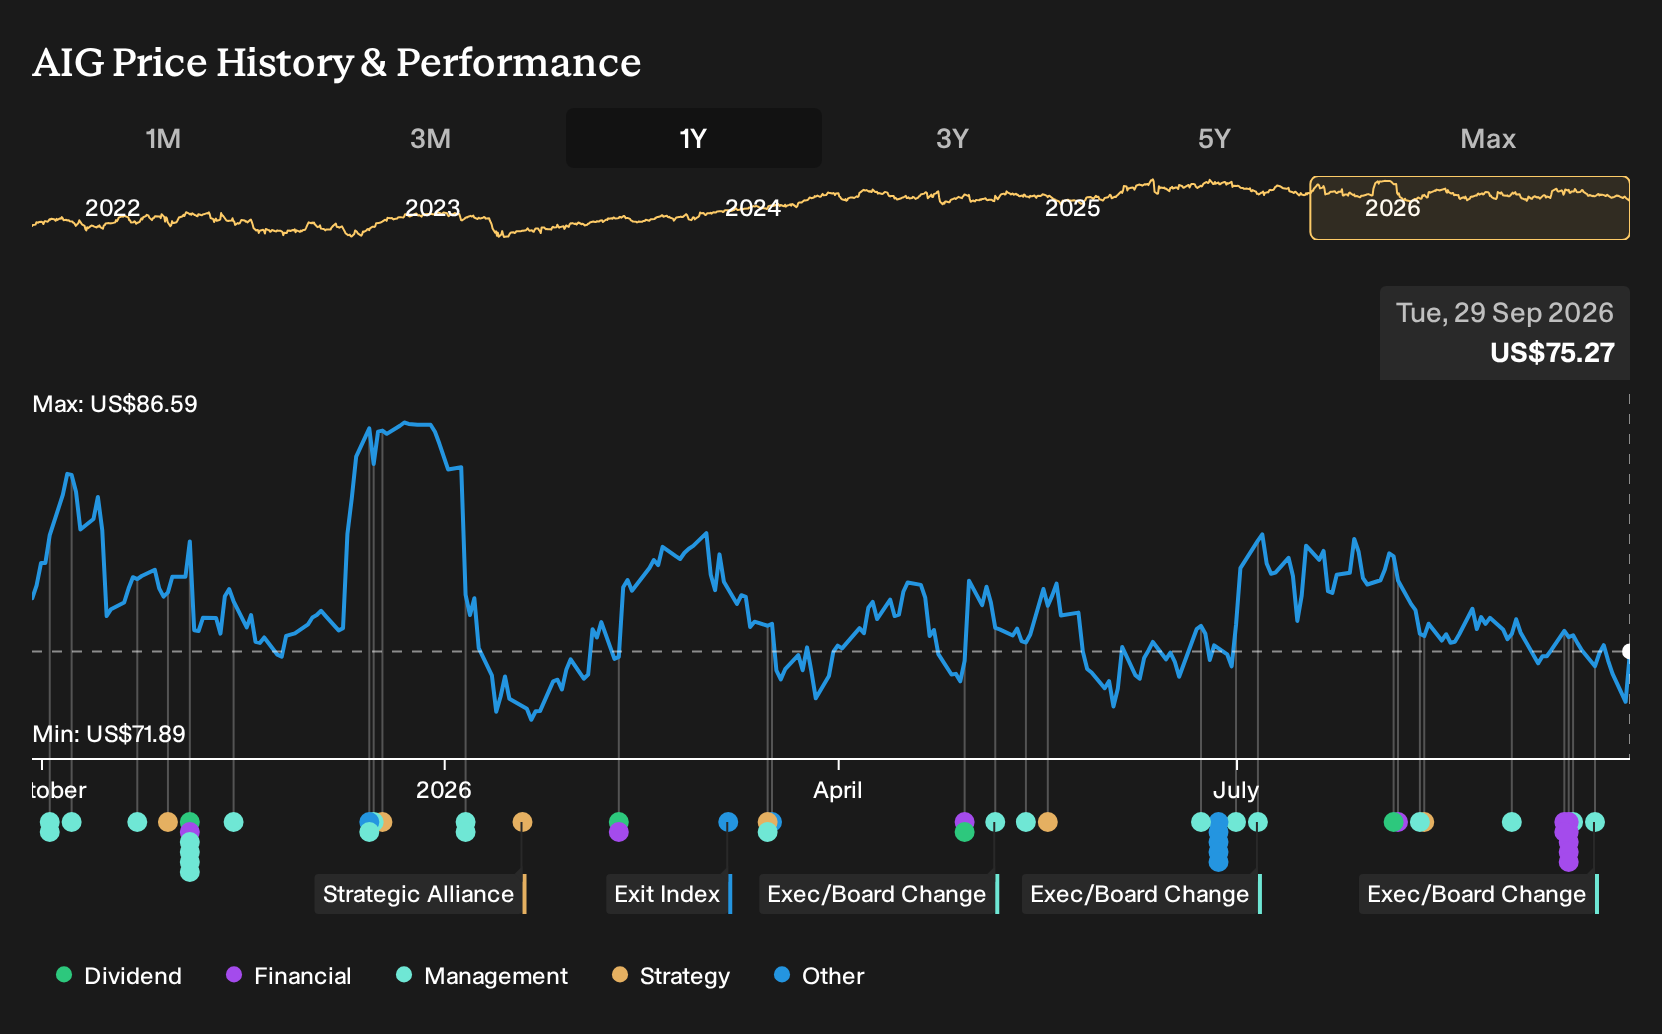
- American International Group appointed Sierra Signorelli as CEO, Americas and Global Personal Insurance, and confirmed Jon Hancock will retire as CEO, General Insurance, at the end of 2026 and move into a Senior Advisor role.
- The leadership reshuffle concentrates accountability for AIG’s commercial and personal lines in the Americas while retaining Hancock’s underwriting expertise to support execution on underwriting discipline and growth initiatives.
- We will look at how AIG's dividend profile intersects with Sierra Signorelli's appointment to reshape the broader investment narrative.
Compare AIG’s leadership shift and dividend profile with a curated group of income-focused companies by scanning the 6 dividend fortresses that could reshape your watchlist.
American International Group Investment Narrative Recap
For a shareholder in American International Group, the core belief is that disciplined underwriting, tighter expenses and focused property and casualty exposure can support steadier earnings and a reliable dividend profile. The main near term swing factor remains underwriting performance, especially as catastrophe events and pricing pressure in areas like North America E and S property can quickly influence margins and capital flexibility.
The leadership changes with Sierra Signorelli and Jon Hancock look more evolutionary than disruptive, so the immediate impact on those underwriting and expense catalysts appears limited. The bigger risk stays the same. A more concentrated portfolio after divestitures could feel sharper hits if specific commercial or personal markets weaken or catastrophe losses stay elevated.
The announcement that Jon Hancock will become Senior Advisor after retiring as CEO, General Insurance, matters most for this leadership shift. His continued focus on underwriting excellence, support for growth initiatives and presence on key subsidiary boards helps maintain continuity in how AIG manages catastrophe exposure, reinsurance, and pricing discipline across both commercial and personal portfolios.
For investors watching catalysts, that advisory role may help AIG execute on digital tools such as Gen AI deployment in underwriting and claims, the expense ratio program, and portfolio reshaping in areas like specialty, casualty and cyber. The question is whether this leadership mix can keep combined ratios and expense trends on track while still supporting AIG’s dividend commitments and measured premium growth.
American International Group's current analyst narrative points to revenues of US$32.0b and earnings of US$3.9b by 2029, built on assumed annual top line growth of 6.2% and an earnings step up of about US$0.9b from US$3.0b today.
Discover how American International Group's fair value indicates an 18% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$88 to US$158 per share for American International Group, which is a wide gap for only a pair of views. That spread meets a business still exposed to catastrophe losses and pricing pressure, so you are seeing sharply different convictions. Use it as a prompt to review multiple viewpoints before acting.
Explore another American International Group fair value estimate, including one that suggests it could be worth just $88.45.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American International Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for American International Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American International Group's overall financial health at a glance.
Looking for more American International Group investment ideas?
Once the story around American International Group feels clear, it can help to widen the lens and compare it with other opportunities that fit your income, quality, or risk preferences. The Simply Wall St Screener is a quick way to do that by filtering for specific traits that match your own brief rather than someone else’s checklist.
- If income is your anchor, start with a focus on higher yielding companies by scanning 6 dividend fortresses that might complement AIG in a dividend-focused portfolio.
- For readers who care most about quality at a reasonable price, narrow the field to financially resilient businesses using a list of solid balance sheet and fundamentals (25 results) as a base universe before you go deeper.
- If you want to cast a wider net for potential outliers, broaden your watchlist with a 17 high quality undiscovered gems that could sit alongside more established holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com