
Smurfit Westrock (SW) Could Be 21% Undervalued Following Its Chile Deal
Smurfit Westrock (SW) has moved back into the headlines after agreeing to buy CMPC’s Chilean containerboard and corrugated packaging operations for US$420 million. The deal expands its Latin American production footprint.
Smurfit Westrock shares have cooled recently, with the 30-day share price return down 8.1% and the 7-day move lower by 4.5%. This comes even though the year-to-date share price return is up 12.1% and the 3-year total shareholder return sits at 57.6%, pointing to longer term momentum but some fading short term enthusiasm around the latest deal and sector narrative.
Scan beyond Smurfit Westrock and see how other packaging and materials players with solid balance sheets stack up using our hand picked list of solid balance sheet and fundamentals (25 results).
Bulls see Smurfit Westrock using the Chile deal and past shareholder returns to argue the recent pullback is an entry point. Bears point to cyclical packaging risk and integration questions. Which case does the valuation math support?
Most Popular Narrative: 21% Undervalued
Smurfit Westrock last closed at $44.38, while the most followed narrative pegs fair value at $56.43 using an 8.09% discount rate. That gap reflects a view that efficiency moves and contract clean-up work are more important than near term share price weakness.
The company's progress in asset rationalization, adopting a disciplined approach to CapEx, and leveraging a decentralized, performance-led culture with plant-level accountability collectively strengthen operational efficiency, reinforcing free cash flow generation and improving net margins over time.
See why 12 investors see Smurfit Westrock as 21% undervalued.
Result: Fair Value of $56.43 (UNDERVALUED)
Still, the bullish Smurfit Westrock story frays quickly if box volumes stay weak in North America and Europe, or if loss-making contracts prove slower to fix than expected.
Find out about the key risks to this Smurfit Westrock narrative.
Another View on Smurfit Westrock’s Valuation
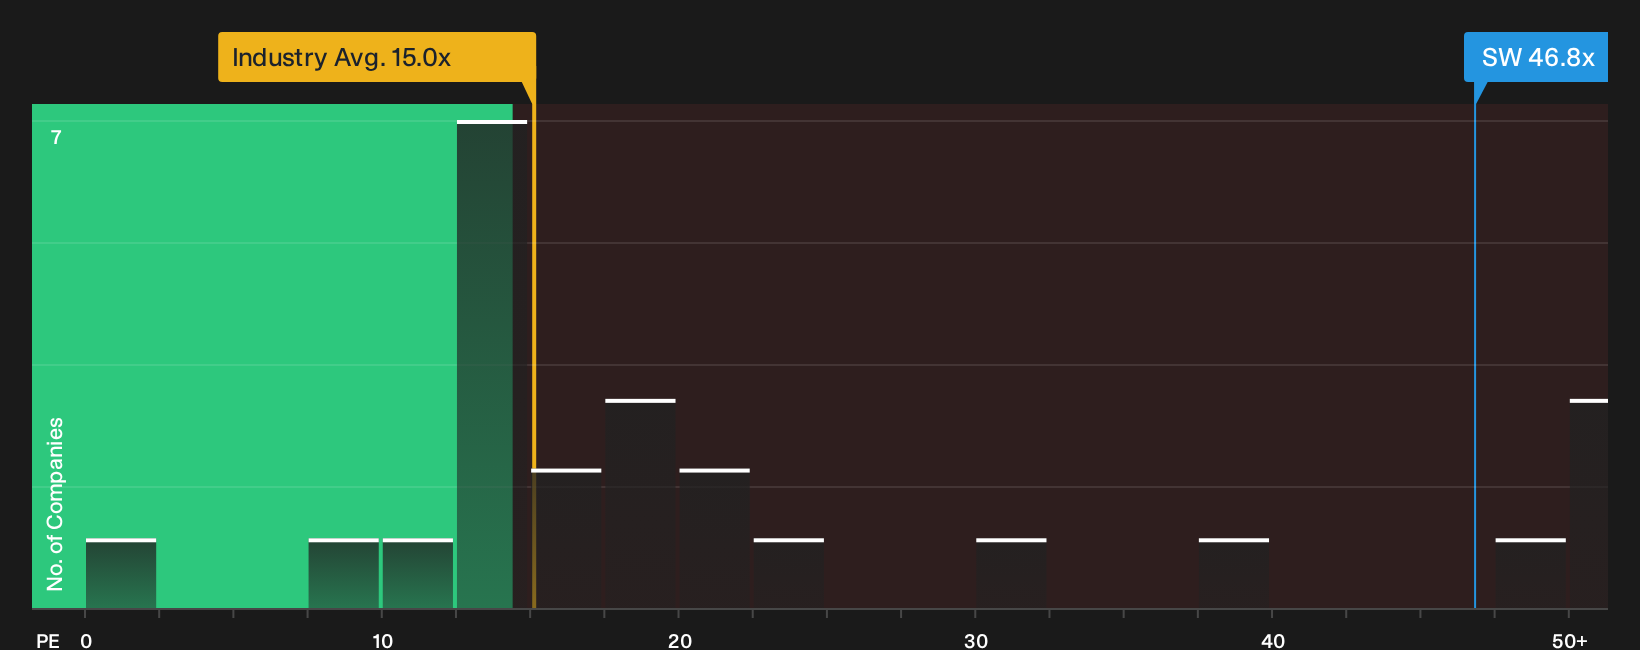
Smurfit Westrock looks inexpensive compared with the fair value estimate of $56.43. However, its current P/E of 46.8x is high relative to the global packaging group on 15x and a fair ratio of 37.4x. That gap highlights valuation risk if sentiment shifts or earnings fall short. Which signal do you trust more?
To see how this pricing gap lines up with earnings quality and peer comparisons, take a closer look at the valuation breakdown using our See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Smurfit Westrock so far. Consider reviewing the full picture by weighing its 4 key rewards and 3 important warning signs while sentiment is still forming.
Looking for more Smurfit Westrock sized investment ideas?
Do not stop with Smurfit Westrock. Use this pullback as a cue to refresh your watchlist with high conviction ideas that match your risk and income goals.
- Target stronger upside potential by scanning for quality companies trading below estimated value using our 31 high quality undervalued stocks.
- Lock in steadier cash flows by focusing on income opportunities screened through our 6 dividend fortresses.
- Dial down portfolio stress and concentrate on capital preservation with our 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com