
3 US Discount Retail Stocks Worth Watching As Shoppers Trade Down
Confidence is cracking, inflation is biting and borrowing is more expensive, yet discount and value-oriented retailers are where many households still stretch every paycheck. That tension between tighter wallets and the hunt for cheaper baskets can create openings for investors who are willing to look closely at how specific businesses respond to weaker sentiment. This article walks through 3 US-listed discount retail stocks exposed to these trends and explains why they might deserve a spot on your watchlist.
The three stocks discussed below are only a sample of the opportunity set, and the full screen surfaced 8 more US discount and value-oriented retailers with equally compelling stories that are not covered here. To identify and analyze the most interesting ideas for your own watchlist, head straight into the US Discount and Value-Oriented Retailers screener.
TJX Companies (TJX)
Overview: TJX Companies runs a global off price retail chain that sells branded apparel and home goods at discounted prices to value conscious shoppers.
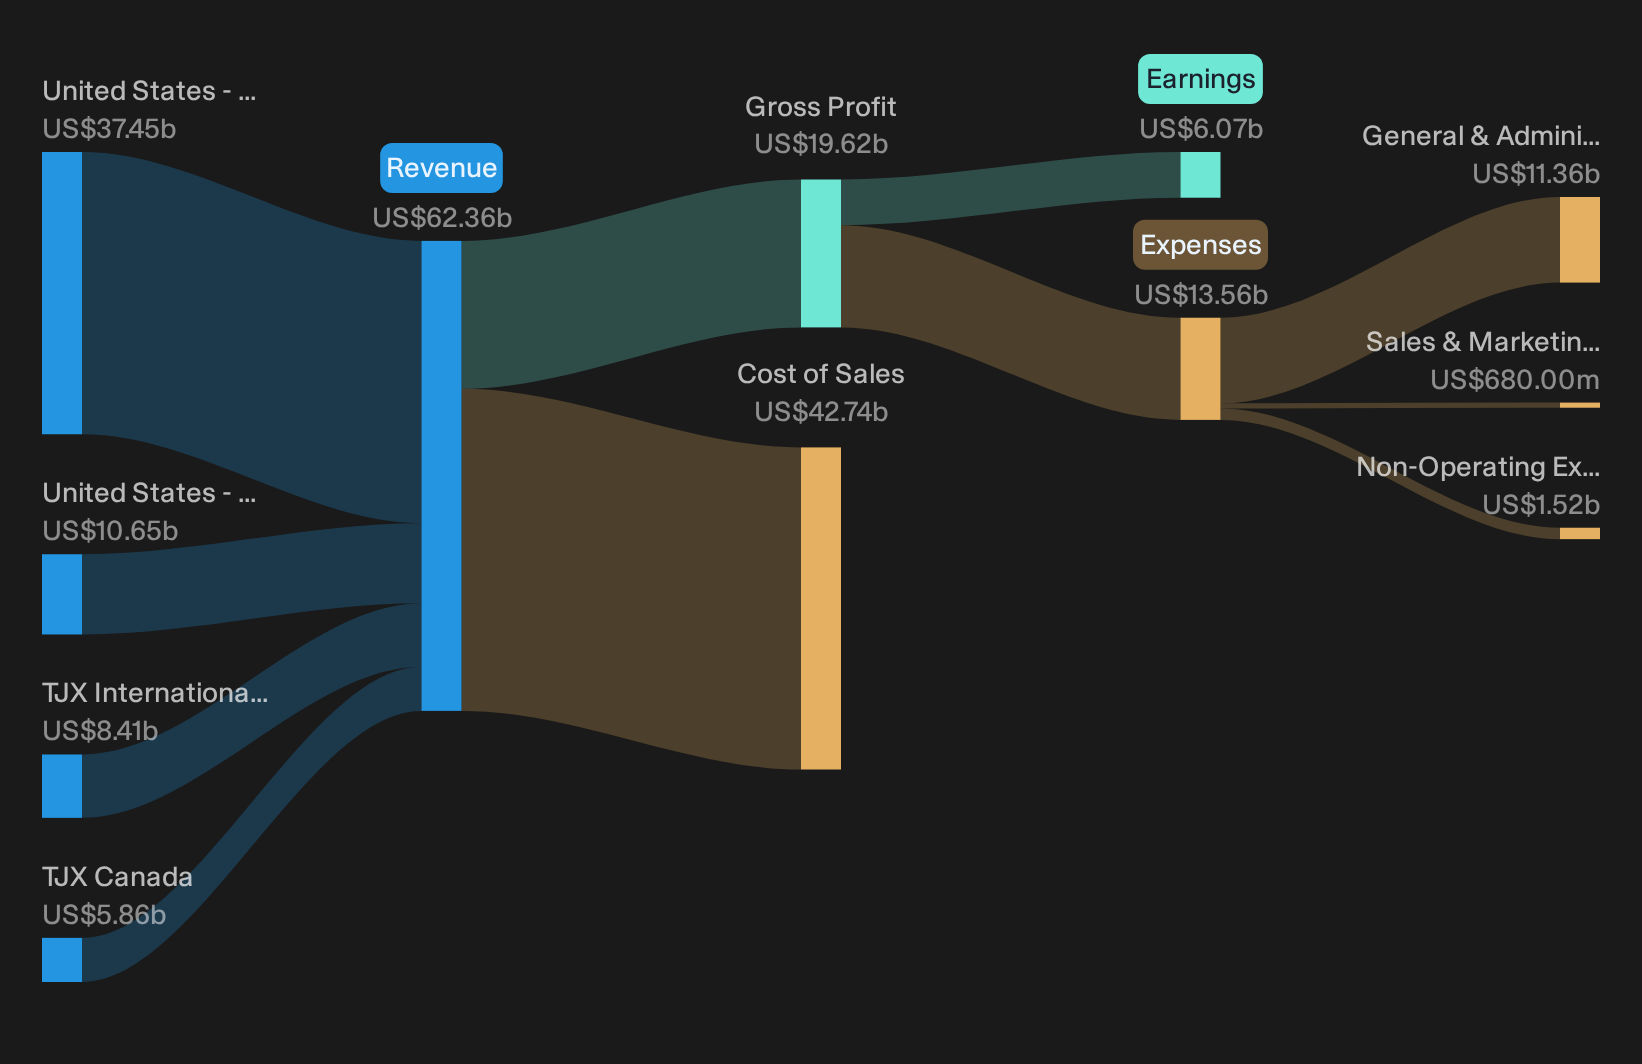
Operations: TJX generates most of its revenue in the US, with about US$37.5b from Marmaxx, US$10.6b from HomeGoods, plus US$5.9b from TJX Canada and US$8.4b from TJX International.
Market Cap: US$143.3b
TJX Companies is a flagship example of the US Discount and Value Oriented Retailers theme, because its off price format directly serves shoppers trading down from full price stores when budgets tighten.
"Strong merchandise availability due to excess inventory in the market allows TJX's experienced global buying teams to secure quality branded goods at favorable prices, which should underpin higher gross margins and mitigate cost pressures."
What those margins look like over time will depend heavily on how one unseen pressure in the sourcing pipeline ultimately plays out.
How that sourcing pressure ultimately filters into pricing and shopper traffic is unpacked in the full narrative for TJX Companies, which maps where TJX Companies could be accelerating or stalling next.
BJ's Wholesale Club Holdings (BJ)
Overview: BJ's Wholesale Club Holdings runs membership-based warehouse clubs across the eastern United States, offering bulk groceries, fuel and general merchandise to value-focused households.
Operations: BJ's Wholesale Club generates US$22.8b of revenue from club retail operations, all sourced from its United States membership base.
Market Cap: US$12.2b
When consumer confidence weakens and everyday costs feel heavier, BJ's Wholesale Club can become a go-to outlet for shoppers trading convenience for lower unit prices and bulk savings.
"Membership fee income trajectory. The May call committed to a directional expectation: MFI growth running at roughly 10% would moderate as the year progressed and the prior year fee increase normalized, with no specific exit rate named."
What happens to pricing power and renewal economics if the balance between membership growth, fee levels and value perception shifts even slightly?
If that balance is what you are watching, the full narrative for BJ's Wholesale Club Holdings breaks down how fee trends, club traffic and value perception could be decoupling beneath the surface.

Ross Stores (ROST)
Overview: Ross Stores runs US off price Ross Dress for Less and dd’s DISCOUNTS chains, selling branded apparel and home goods to budget conscious shoppers.
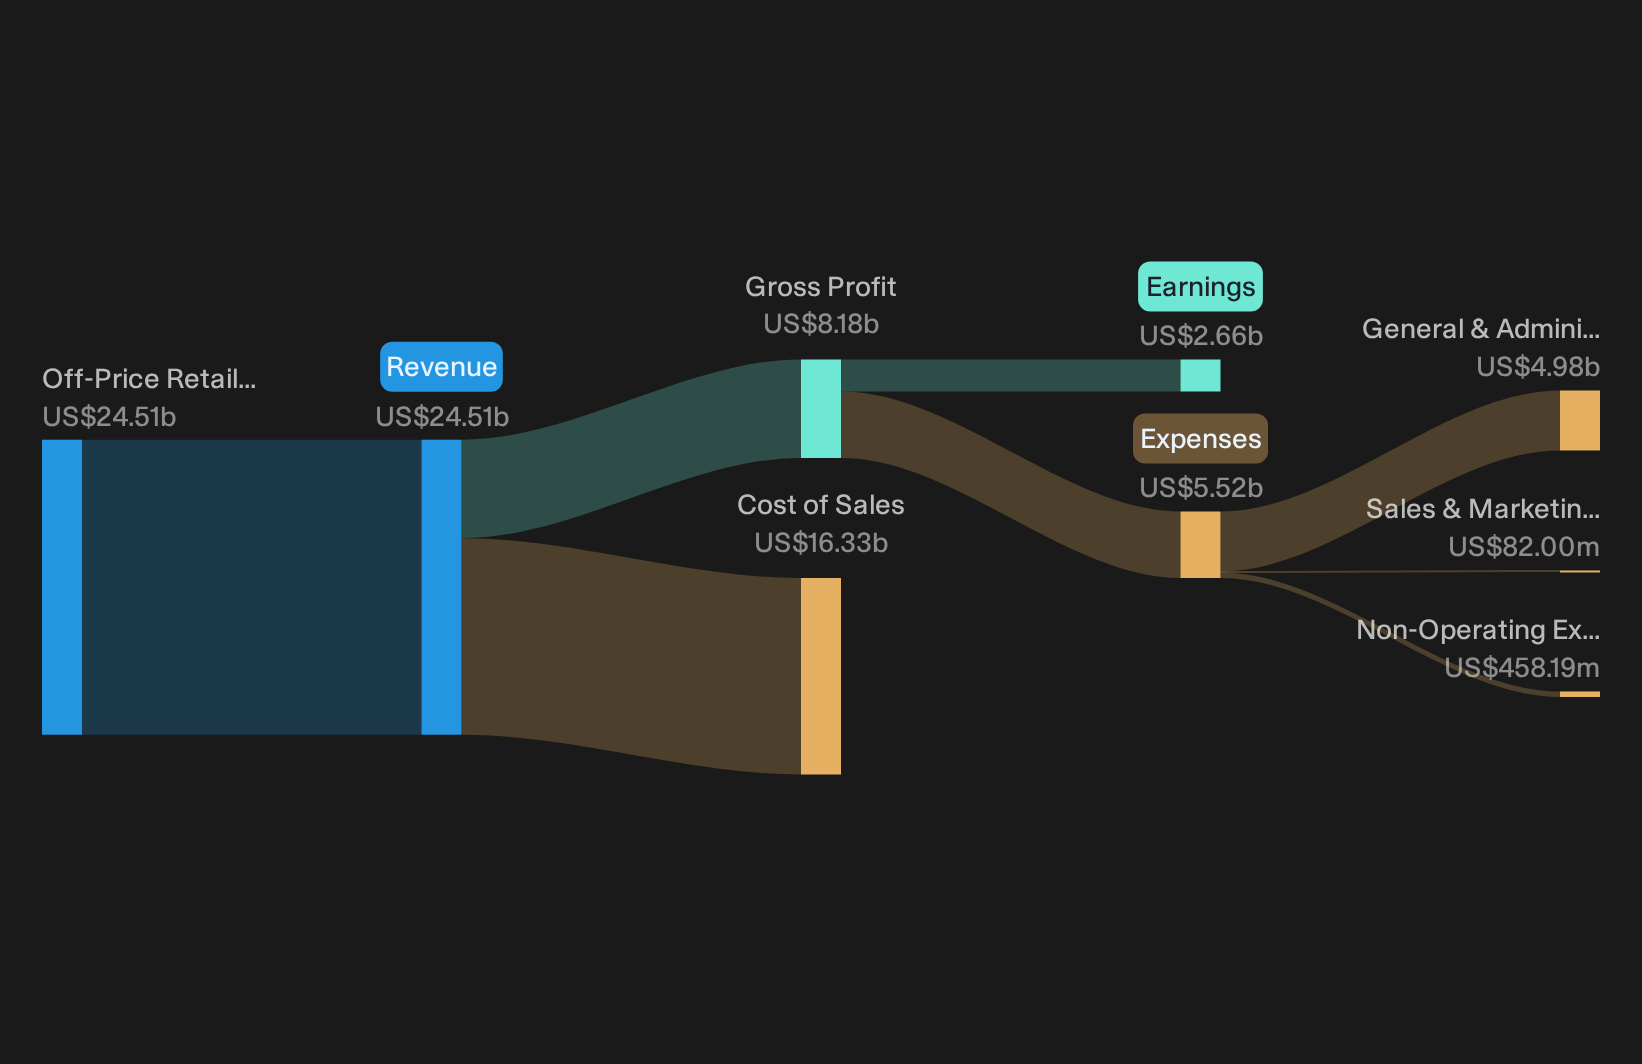
Operations: Ross Stores generates all of its US$24.5b in annual revenue from off price retailing in the United States, fully tied to discount shopping.
Market Cap: US$75.7b
Ross Stores is tightly linked to the US Discount and Value Oriented Retailers theme, because its model depends on shoppers trading down to lower ticket baskets when confidence weakens and full price retailers feel too expensive.
"The reason to own it is that the downside is unusually well defended, given a net cash balance sheet of roughly $3.1B, no owned real estate obligation, no e-commerce cost structure, and 40 years of audited results through four recessions."
What happens to Ross Stores' earnings path if one key assumption about how far shoppers trade down when budgets tighten does not hold?
If that trade down risk is what you care about, the full narrative for Ross Stores shows where Ross Stores could be accelerating, where it could be masking pressure, or where it could be quietly stalling next.
Curious About Your Next Investing Alternative
Fresh ideas can move before they are widely noticed. By the time momentum is rising, it is easy to feel late to the opportunity. Scan these focused themes while it matters and consider getting in at an earlier stage.
- Target stronger income potential by checking companies in the 6 dividend fortresses before yields change or prices reset.
- Track early movers in machine learning by filtering through the 37 profitable AI stocks that aren't just burning cash while these businesses may still be under the radar.
- Spot potential breakout miners by reviewing the curated 36 elite gold producer stocks before the next phase of commodity momentum develops.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com