
Why Sysco (SYY) Is Getting Attention Today
Sysco (SYY) has been busy on the financing side. The foodservice distributor issued CAD 1.5b of senior notes on September 25, 2026 to help fund its pending JRD Unico and Warehouse Realty acquisition.
Sysco’s financing push comes as the share price has eased, with a 30 day share price return down 4.21% and a 90 day share price return down 6.03%. Even though the year to date share price return is up 8.08% and the 3 year total shareholder return is 32.70%, this suggests that longer term holders have seen meaningfully better results than more recent buyers.
Position your Sysco view alongside a curated set of foodservice and consumer staples peers by scanning list of solid balance sheet and fundamentals (25 results).Sysco now trades below both intrinsic value estimates and published analyst targets after that recent pullback. Is the discount a genuine opportunity or a fair response to heavier debt and acquisition risk as the valuation math is examined next?
Most Popular Narrative: 13% Undervalued
Sysco trades at $78.49 against a widely followed fair value view of about $90.31, so the narrative is leaning toward a material discount and relies heavily on execution of a few large strategic projects.
The planned acquisition of Jetro Restaurant Depot, which produced about US$16 billion of revenue, US$2.1 billion of EBITDA and nearly US$2 billion of free cash flow, is expected to add roughly 20% to combined revenue, about 45% to EBITDA and about 55% to free cash flow, which would increase overall EBITDA margins and earnings power once integrated.
See why 66 investors see Sysco as 13% undervalued.
Result: Fair Value of $90.31 (UNDERVALUED)
Still, the Sysco story could change quickly if higher leverage after Restaurant Depot sours market sentiment or if AI efficiency gains arrive more slowly than analysts currently project.
Find out about the key risks to this Sysco narrative.
Another View On Sysco’s Valuation
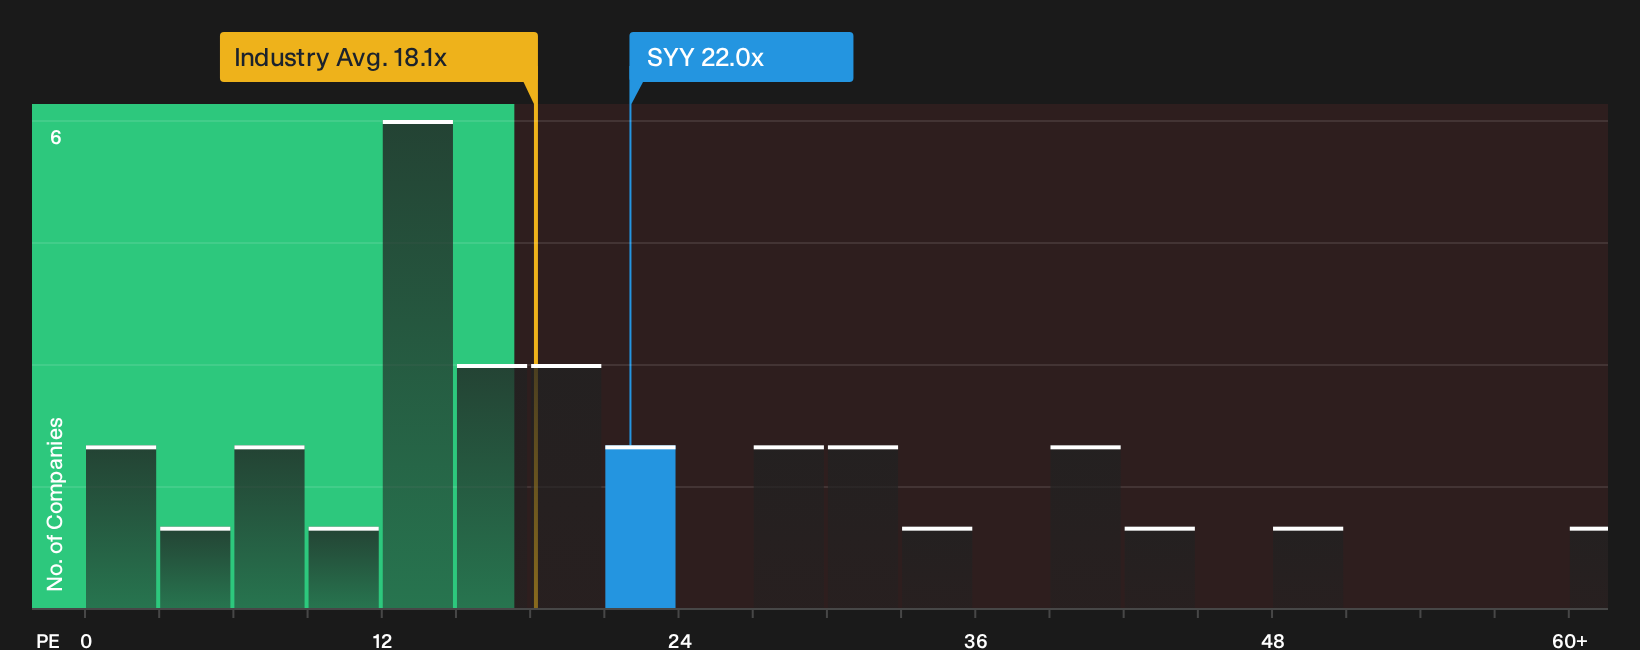
The first story paints Sysco as materially undervalued, yet its current P/E of 22x is higher than the US Consumer Retailing average of 18.1x and sits below a fair ratio of 32x. That mix hints at both downside risk if sentiment cools and upside if the market moves toward that fair ratio, so which side do you think dominates from here?
For a closer look at how this earnings multiple stacks up against sector norms and the fair ratio, take a few minutes to review See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Sysco’s value can feel unsettling, so move quickly, check the underlying data yourself, and weigh both sides of the story using the 3 key rewards and 1 important warning sign.
Looking for more Sysco sized investment ideas?
Sysco might be front of mind today, but you give yourself a real edge by lining it up against other clear, data backed opportunities using the Simply Wall Street Screener.
- Target potential mispricings across the market by running a scan for 31 high quality undervalued stocks that pair robust fundamentals with attractive entry points.
- Build a more resilient portfolio by screening for 32 resilient stocks with low risk scores that show steadier risk profiles and fewer financial red flags.
- Get ahead of the crowd by mapping out 17 high quality undiscovered gems before they appear on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com