
What Asbury Automotive Group (ABG)'s Medford Toyota Opening Means For Shareholders
- Asbury Automotive Group has completed a multi year redevelopment of a former five acre office campus in Medford into a more than 200,000 square foot Toyota dealership with four floors of climate controlled showroom space, parking for over 570 vehicles, and 37 service bays with room to expand.
- The project created about 50 new local jobs plus 50 relocated roles, which points to a heavier fixed cost footprint but also greater capacity to support parts, service, and sales volume following the Herb Chambers acquisition.
- We will examine how Asbury Automotive Group's investment narrative is shaped by this large Medford Toyota expansion and the associated service capacity build out.
Scan how Asbury Automotive Group's expansion story compares with other operators investing heavily in capacity by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
Asbury Automotive Group Investment Narrative Recap
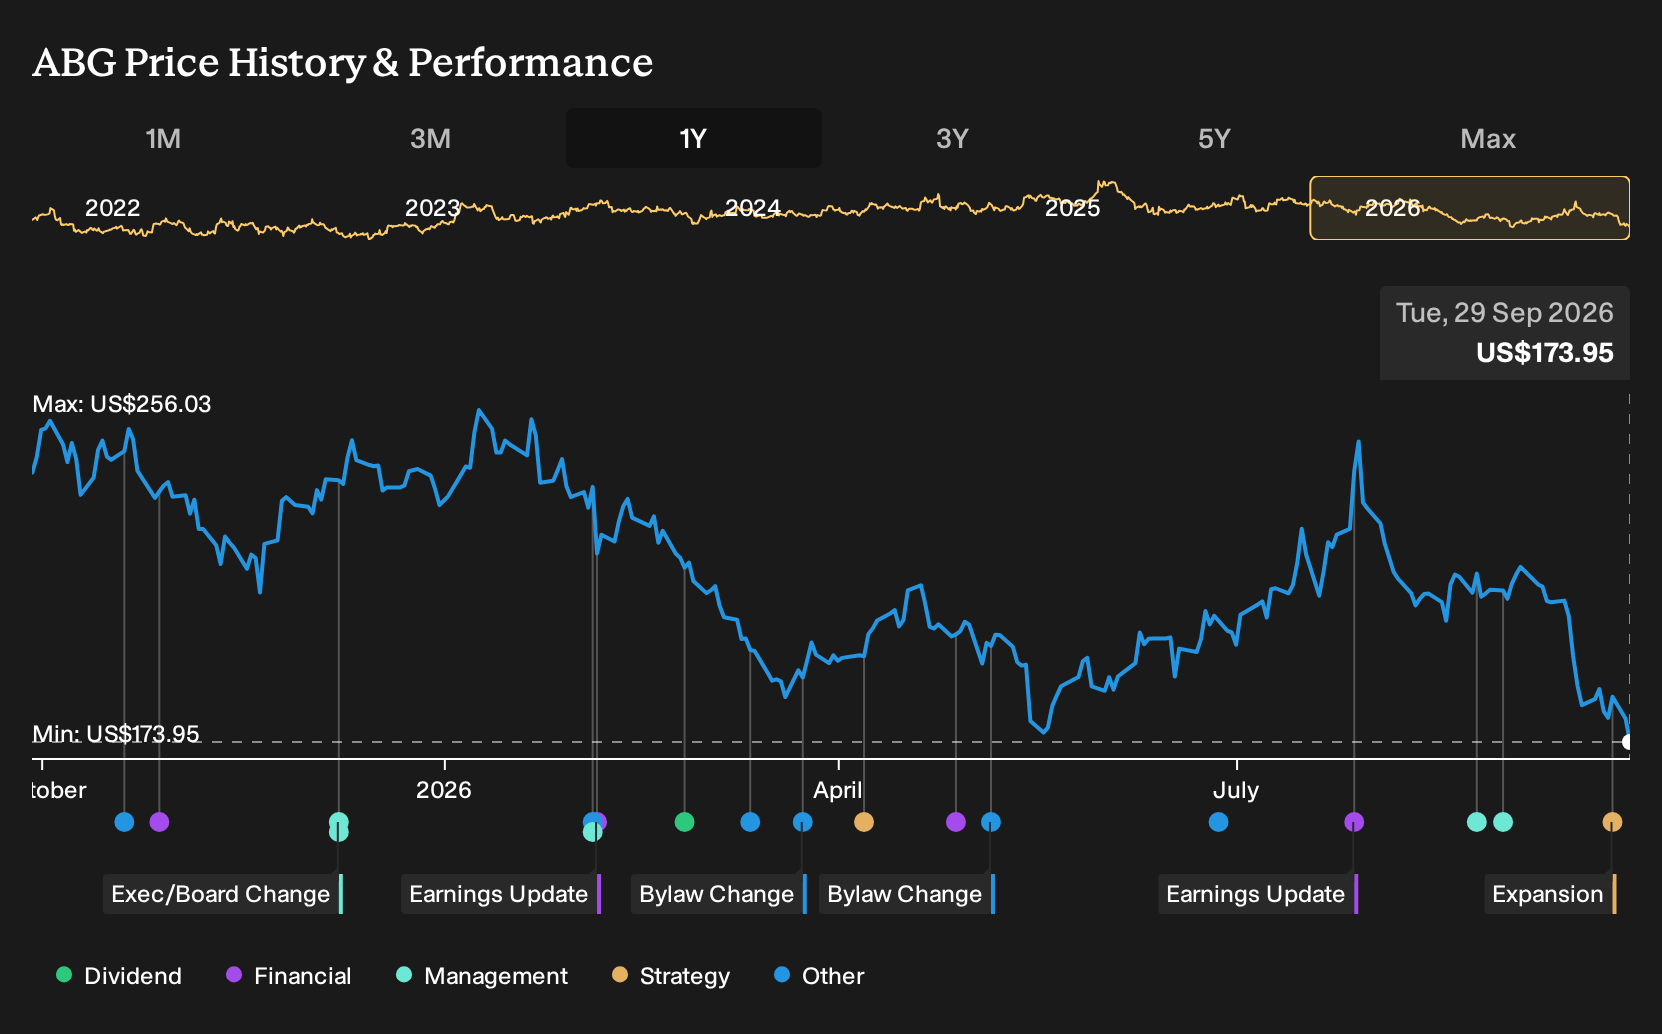
For you to own Asbury Automotive Group, you need to believe the dealer model can still generate solid cash flow even as digital retail and direct to consumer formats grow. The Medford Toyota build out adds high fixed costs and capacity. That probably matters less for the share price near term than management proving it can stabilize earnings after a stretch of declining profits and margin compression.
The biggest swing factor over the next year still looks like execution on acquisitions and cost control rather than this single site. Leverage already leans on operating cash flow, so any misstep in integrating Herb Chambers or weaker used vehicle volumes would likely weigh more heavily on the story than the Medford opening helps.
The Medford Toyota expansion ties directly back to the Herb Chambers acquisition, which pushed Asbury Automotive Group deeper into New England with higher ticket brands. This redevelopment shows the group is willing to commit significant capital to that region. The payoff depends on whether the larger service footprint and showroom can sustain higher parts, service, and F&I throughput over time.
There is a trade off. A premium facility can support the narrative of growing high margin fixed operations, yet it also adds pressure on cash generation when debt is already flagged as not well covered by operating cash flow. Investors will likely watch how quickly this location ramps, and whether similar projects are paced cautiously while earnings and used vehicle supply trends remain uncertain.
Asbury Automotive Group's current analyst narrative points to US$21.2b in revenue and US$639.2m in earnings by 2029, built on 5.6% yearly revenue expansion and an earnings increase of roughly US$129.7m from the US$509.5m reported today.
Uncover how Asbury Automotive Group's fair value indicates a 46% potential upside to its current price before the discount to Asbury Automotive Group closes.
Exploring Other Perspectives
Some bullish analysts focus less on the Medford fixed cost risk and more on efficiency tools like Tekion and Total Care Auto. They were already modeling about US$21.4b of revenue and US$644.9m of earnings by 2029 before this opening. You can compare those more optimistic views with your own and decide whether this redevelopment shifts the story.
Explore 2 other Asbury Automotive Group fair value estimates, including one that suggests the potential for as much as 191% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Asbury Automotive Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Asbury Automotive Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Asbury Automotive Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Asbury Automotive Group?
Once you have a view on Asbury Automotive Group, it can help to line that thesis up against other opportunities with different risk and return profiles. The Simply Wall St Screener lets you compare businesses side by side so you can see which ones better match your goals on quality, valuation, income, or balance sheet strength.
- If you want potential growth with tighter risk controls, start by reviewing a set of 32 resilient stocks with low risk scores that score well on stability and resilience.
- For investors who like to get paid while they wait, scan income opportunities through a curated group of 6 dividend fortresses built around high-yield payouts.
- Or, if you are hunting for opportunities that are less crowded, check a focused pool of 17 high quality undiscovered gems with strong fundamentals that are off many investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com