
Is Bank of New York Mellon Corporation (BNY) Undervalued As ADR Depositary News Draws Attention?
Kazia Therapeutics’ decision to replace Bank of New York Mellon Corporation (BNY) as depositary for its American Depositary Receipt program with JPMorgan puts a small but clear spotlight on BNY’s securities services franchise.
Recent trading has been a bit softer for Bank of New York Mellon Corporation, with the share price down 9.6% over the past month and 2.1% over the last week. Yet the stock still shows strong momentum in the bigger picture, given a 25.6% year to date share price gain and a 37.2% one year total shareholder return, extending a very strong three year total shareholder return of around 2.8x that hints at investors repricing the business on shifting expectations for its earnings power and risk profile.
Scan beyond Bank of New York Mellon Corporation and compare its recent run to a hand picked group of financials with resilient balance sheets using our list of solid balance sheet and fundamentals (25 results).
After a long run that has lifted BNY more than 2x over five years, the recent pullback raises a simple tension: Is this a reasonable spot to commit fresh capital, or does patience for a cheaper entry make more sense once valuation is on the table next?
Most Popular Narrative: 12% Undervalued
Bank of New York Mellon Corporation’s most followed narrative pegs fair value at about $167.79 using a 9.69% discount rate, compared with the recent $146.98 close. This frames the latest pullback as a potential gap between execution and expectations.
Accelerated investment in digital platforms, including the AI supported platform operating model funded by roughly US$4b of annual engineering spend and hundreds of AI use cases, is now showing up in 600 basis points of positive operating leverage in the first half of 2026. This can continue to influence net margins and earnings as capacity creation allows more revenue on a relatively fixed employee base.
See why 40 investors see Bank of New York Mellon as 12% undervalued.
Result: Fair Value of $167.79 (UNDERVALUED)
Still, if fee pressure in custody and asset servicing returns, or if expense growth pushes ahead of revenue, the bullish narrative on Bank of New York Mellon Corporation could quickly reset.
Find out about the key risks to this Bank of New York Mellon narrative.
Another View: DCF Puts Bank of New York Mellon Corporation Slightly Ahead of Itself
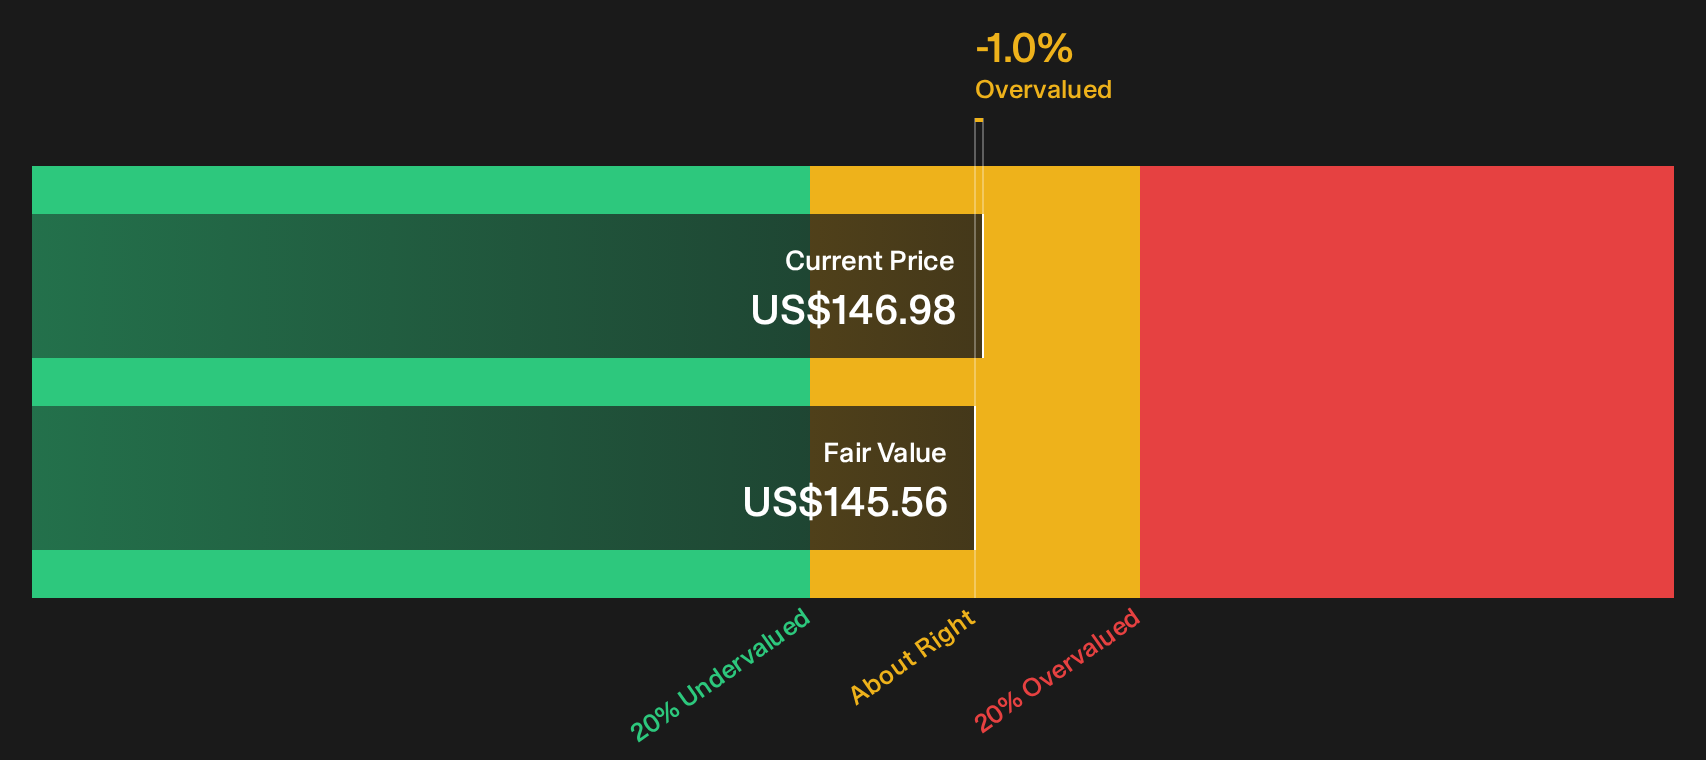
There is a twist when the SWS DCF model is brought in. On this approach, Bank of New York Mellon Corporation at $146.98 sits just above an estimated future cash flow value of $145.56, which points to the shares being a touch overvalued rather than 12% undervalued. That kind of small gap can still matter if sentiment cools.
For readers who want to see how the cash flow math stacks up line by line, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of New York Mellon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Bank of New York Mellon Corporation can create urgency, but the quickest edge is your own homework. Pressure test both the upside and the downside and then walk through the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Bank of New York Mellon Corporation?
If you stop with Bank of New York Mellon Corporation, you only see one angle. Broaden your watchlist now or risk missing income, value, and growth opportunities that may be sturdier.
- Target income streams by reviewing dividend payers screened as potential 6 dividend fortresses.
- Look for quality at a discount by scanning companies flagged as 31 high quality undervalued stocks.
- Prioritise capital protection and review stocks filtered as 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com