
Hafnia (OB:HAFNI) Following Its Equity Raise Is The Stock Already Fully Valued
Hafnia (OB:HAFNI) has just completed a follow on equity offering worth about US$299 million, issuing more than 35 million ordinary shares at a modest discount, a move that reshapes its capital base.
The follow-on deal comes at a time when Hafnia’s short-term share price return has been strong, with a 17.39% 1-month gain contributing to a 40.23% 3-month rise and a 73.49% year-to-date move. The 5-year total shareholder return is very large, suggesting that recent equity issuance and board changes are being weighed against a multi-year track record of value creation.
Scan beyond Hafnia and see how other tanker and energy transport stocks with rising volumes and fresh equity raises stack up on our curated 620 high quality undiscovered gems list.
After that sharp run and a fresh US$299 million equity raise, Hafnia now trades almost exactly in line with the NOK 91 analyst target, while its intrinsic value estimate signals a roughly 29% premium. Which reference point is likely to be used as the anchor for fair value next?
Price-to-Earnings of 7.2x for Hafnia: Is it justified?
Hafnia now trades on a P/E of 7.2x, with the share price at NOK91.15 and recent returns strong, while peers and the wider Norwegian market change hands at roughly double that earnings multiple.
The P/E ratio compares what investors pay for each unit of current profit to what other businesses command. This can matter a lot for tanker operators where earnings can be tied closely to freight cycles and vessel utilization. A 7.2x multiple means the equity is priced at just over seven years of current earnings, using today’s share price and Hafnia’s recent profitability as the anchor.
Relative to the Norwegian market P/E of 14.1x and the European Oil and Gas industry average of 14x, Hafnia trades at a much lower earnings multiple. This suggests investors are pricing in more cautious future profits or a less durable earnings profile. The SWS fair P/E estimate of 6x sits even lower than the current 7.2x. That indicates a level the market could move toward if those more conservative assumptions prove correct and the recent share price strength cools.
Explore the SWS fair ratio for Hafnia.
Result: Price-to-Earnings of 7.2x (ABOUT RIGHT)
Still, Hafnia’s recent revenue and net income declines, along with its exposure to freight cycles and vessel demand, could quickly challenge today’s valuation optimism.
Find out about the key risks to this Hafnia narrative.
Another View on Hafnia’s Value
The P/E story flags Hafnia as cheap against peers, but the SWS DCF model tells a different tale. On that forward cash flow view, the shares at NOK91.15 sit above an estimated value of NOK70.87. Does that point to froth, or just a higher appetite for near term earnings?
Look into how the SWS DCF model arrives at its fair value.
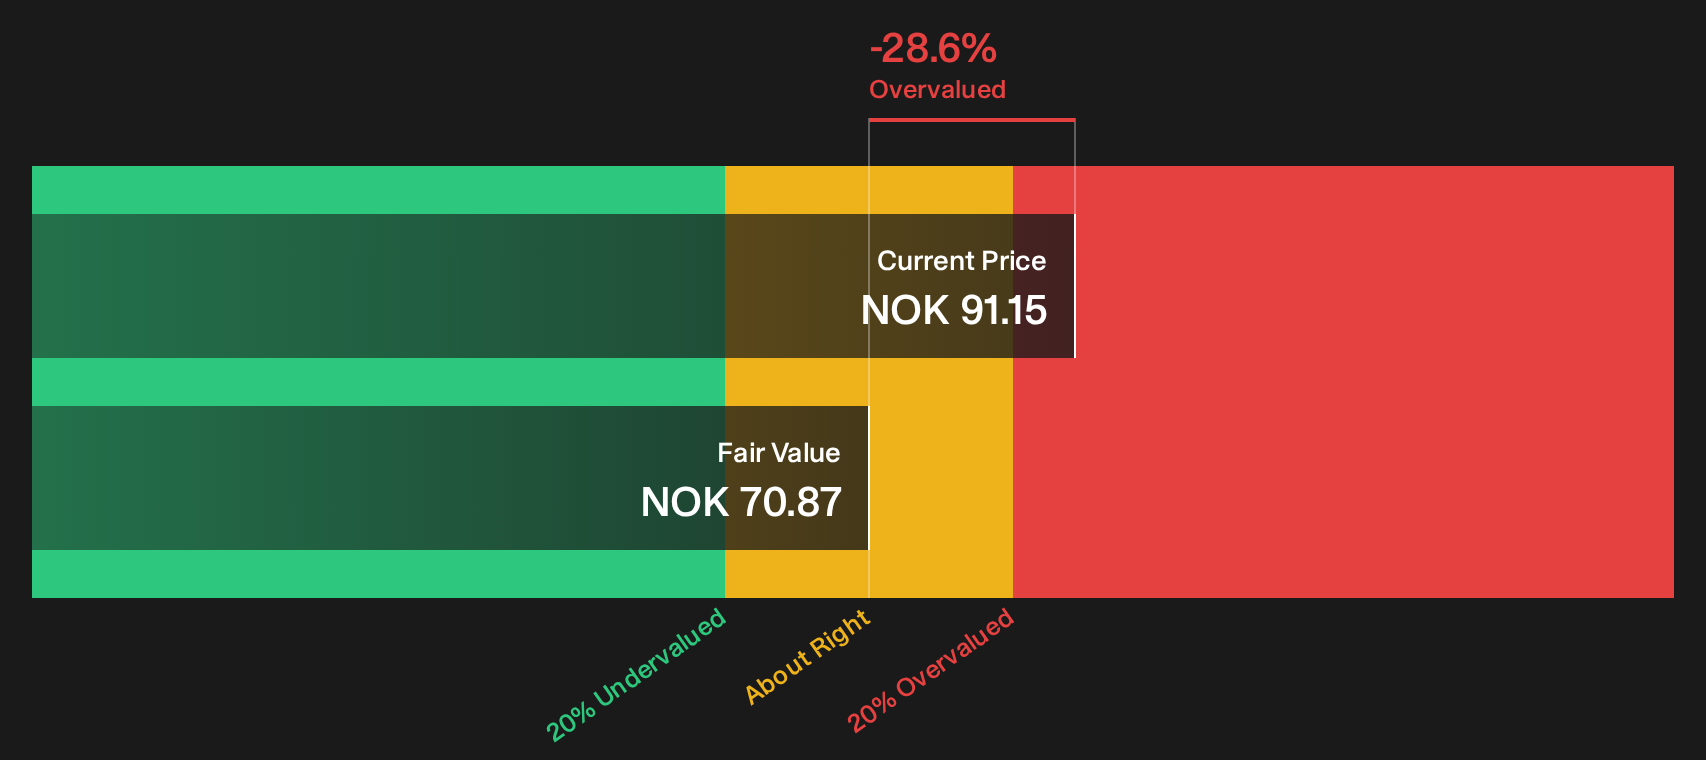
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hafnia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hafnia’s valuation and recent moves can look messy at first glance. Check the numbers yourself, weigh the trade offs, and then use the 2 key rewards and 2 important warning signs.
Looking for more Hafnia sized investment ideas?
Hafnia’s setup is only one angle. Broaden your watchlist now so you are not relying on a single story when the next opportunity appears.
- Target value first and let the market come to you by scanning our 197 high quality undervalued stocks built around quality businesses at attractive prices.
- Strengthen your downside protection by reviewing the 227 resilient stocks with low risk scores that filters for resilient balance sheets and steadier risk profiles.
- Cast a wider net across lesser known opportunities using the 126 elite penny stocks with strong financials curated for higher potential ideas with leaner market caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com