
3 Australian Penny Stocks With Revenue Up To A$3 Billion
With Australian interest rates now at a 15-year high, cash in the bank pays more, but rising borrowing costs are putting real pressure on weaker balance sheets. That is where financially solid penny stocks come into focus. You get exposure to early stage stories while the screener filters for companies that look better equipped to handle higher funding costs. This article walks through three standouts from that group.
The three stocks covered next are just a sample from this idea, and the full screen surfaced 396 more companies with similarly interesting financial stories not covered here. To size up that wider group quickly, head straight into the Financially Fit Penny Stocks screener to identify, analyze, and focus on your highest conviction penny stock candidates.
Ora Banda Mining (ASX:OBM)
Ora Banda Mining is an Australian gold producer focused on the Davyhurst Gold Project, a producing mine that underpins its inclusion in a “Financially Fit Penny Stocks” screen through direct gold and ore sales. The business generated A$807 million from gold production and exploration in Australia and has a market cap of A$2.9b.
For a penny stock, Ora Banda Mining combines a producing gold hub at Davyhurst with reported A$807 million in gold related revenue and A$216.2 million in net income, which fits a financially solid profile. The question is how that strength holds up if a single unseen pressure on mining margins shifts.
If that pressure is building quietly in the background, the 4 key rewards and 1 important warning sign shows where Ora Banda Mining’s current strength could either compound or start to fray.

DroneShield (ASX:DRO)
DroneShield builds counter-drone hardware and software that detects and disrupts hostile drones for defence, security, and critical infrastructure customers, tying it tightly to the Financially Fit Penny Stocks screener theme. The firm reports A$270 million in aerospace and defense revenue and carries a market value around A$1.5b.
DroneShield taps straight into the surge in counter-drone security spending, giving this penny stock screen some real-world defense exposure rather than just a concept story.
"If management continues converting its growing pipeline into multi-year contracts while expanding margins through scale manufacturing, we could see a valuation re-rating over the next 12 to 24 months."
What happens if the current momentum in long term defence contracts slows just as one key cost driver starts to shift.
If that risk is starting to bite, the full narrative for DroneShield unpacks how DroneShield’s contract momentum, cost base, and potential re rating could be pulling in different directions.

Perenti (ASX:PRN)
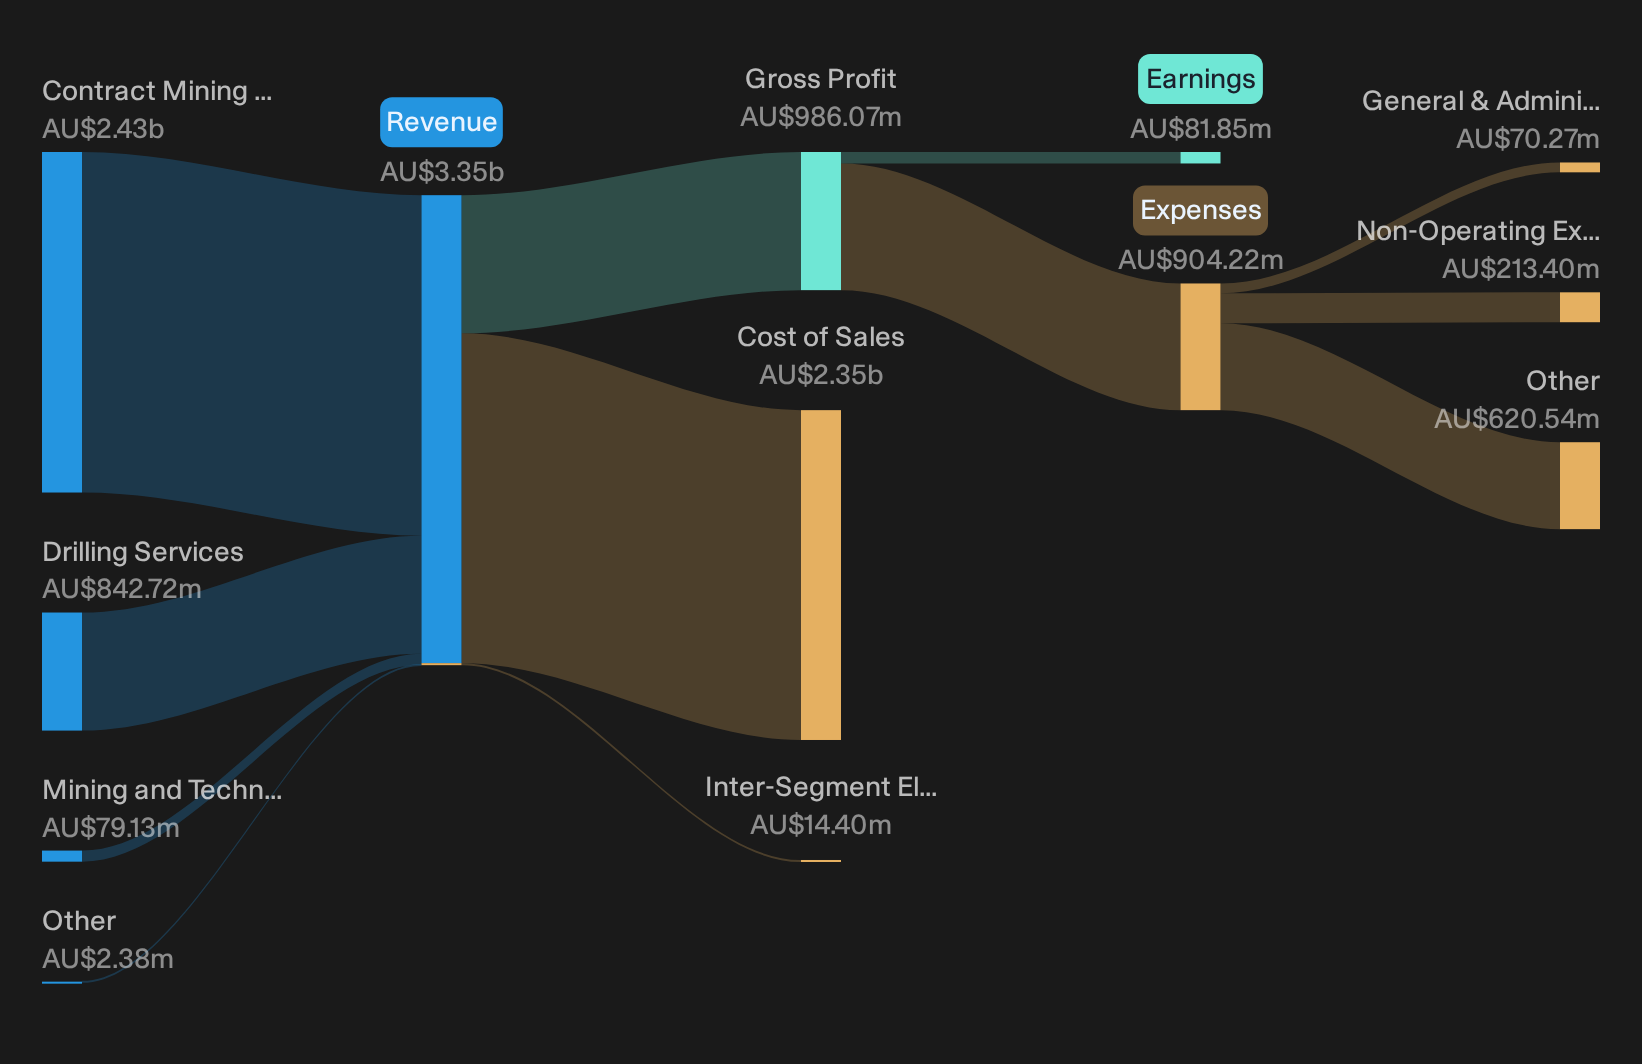
Perenti is a mining services group in the Financially Fit Penny Stocks theme, where the contract mining arm is the key link. It generates about A$2.4b of underground and surface mining revenue alongside A$843 million from drilling services, on top of a roughly A$2.2b market value.
Perenti brings something slightly different to this penny stock screen. It offers a mature contract mining business that still carries small-cap upside but with revenue tied to long term service work rather than single projects, which sets up a different kind of risk and reward profile.
"The accelerating demand for critical minerals (such as copper, lithium, and nickel) driven by global energy transition and electrification is fueling a large and sustained pipeline of projects, which underpins Perenti's long-term contract opportunities and provides high revenue visibility and growth potential."
The real test comes if one cost and margin pressure that has been building quietly in the background starts to move faster than expected.
If that pressure really accelerates, the full narrative for Perenti shows how Perenti’s contract book, cost profile, and copper heavy exposure could still set up an overlooked upside skew.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time everyone sees the breakout, the clean entry often goes missing. Scan these curated lists while the momentum is under the radar for now and look for opportunities early.
- Identify resilient cash generators before the crowd by running through a curated list of solid balance sheet and fundamentals (11 results) that filters for sturdier fundamentals and clearer financial footing.
- Explore potential income opportunities with a hand picked pool of higher yielding payers using the curated 3 dividend fortresses that focuses on stronger balance sheets alongside elevated payouts.
- Follow where AI infrastructure spending may be directed next by scanning the curated 88 AI infrastructure stocks and filtering for companies tied directly to that build out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com