
Walker & Dunlop (WD) Lands $238 Million Refinance As Fair Value Debate Stays In Focus
Walker & Dunlop (WD) arranged a US$238 million refinancing for The Landmark South, a 631 unit multifamily property in Doral, Florida, highlighting the firm’s role in large scale commercial real estate lending.
Recent trading has been much tougher for Walker & Dunlop, with the share price down 12.21% over the past 30 days and 33.90% over 90 days, while the year-to-date share price return has fallen 38.18%.
Including dividends, total shareholder return has declined 54.09% over the past year and 64.08% over five years, which points to fading momentum even as deals like the Landmark South refinancing keep the business active in commercial real estate capital markets.
Scan other commercial real estate lenders that are under pressure from recent drawdowns and compare Walker & Dunlop with our hand picked list of 32 resilient stocks with low risk scores.
Walker & Dunlop has seen a sharp reset in its share price while continuing to execute deals like The Landmark South refinancing. The real question now is whether most of the recovery story is already behind the stock or still ahead.
Most Popular Narrative: 36% Undervalued
Walker & Dunlop last closed at $36.30, while the most popular narrative anchors fair value at $57. That gap frames the refinancing headlines against a valuation story built on multifamily demand, technology spending, and capital markets recovery.
The structural shortage and unaffordability of single-family housing, along with record apartment absorption and high multifamily occupancy (96%), are expected to drive up rents and property values, leading to increased demand for multifamily financing, higher origination fees, and a larger servicing portfolio, all supporting both revenue and earnings expansion.
See why 1 investors see Walker & Dunlop as 36% undervalued.
Result: Fair Value of $57 (UNDERVALUED)
Still, the Walker & Dunlop story can crack if high interest rate volatility keeps transaction volumes muted and if heavier technology spending fails to lift profitability.
Find out about the key risks to this Walker & Dunlop narrative.
Another View on Walker & Dunlop's Valuation
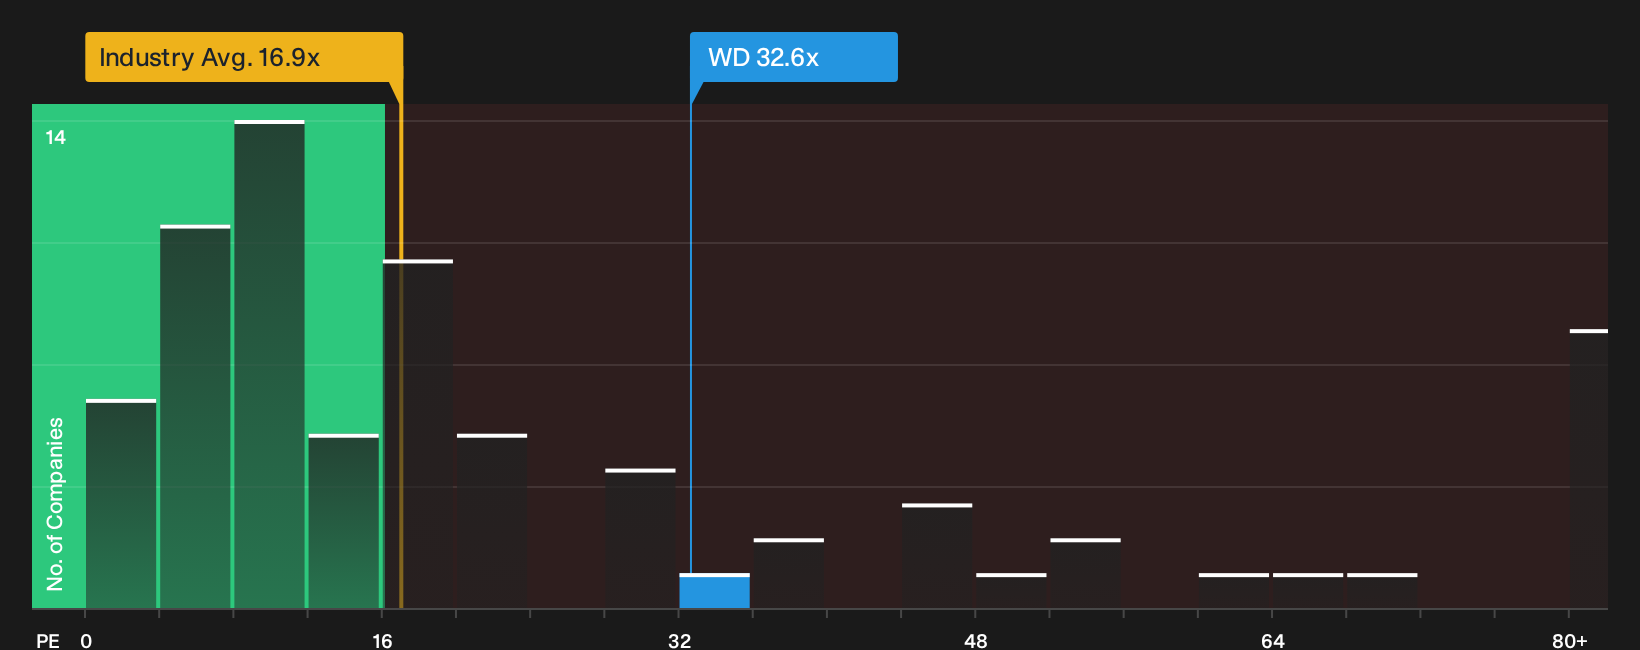
The first narrative frames Walker & Dunlop as undervalued against a $57 fair value, yet the current P/E of 32.6x tells a tougher story. That multiple is far above peers at 9.2x, the US diversified financials average at 16.9x, and even the 20.4x fair ratio estimate.
If earnings or sentiment disappoint, that gap leaves less margin for error than a simple discount to fair value might suggest. It raises a harder question for investors: Is the recent share price reset enough compensation for paying such a rich multiple for WD right now, or not?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Walker & Dunlop can feel confusing, so move quickly. Look through the numbers yourself and weigh both sides of the story with 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Walker & Dunlop?
If Walker & Dunlop has you rethinking your watchlist, do not stop there. Broaden your opportunity set and let data do the heavy lifting for you.
- Target potential value opportunities early and scan a curated set of 17 high quality undiscovered gems that many investors may not be watching yet.
- Strengthen the defensive side of your portfolio by focusing on companies with robust finances through a focused list of solid balance sheet and fundamentals (25 results).
- Build a cash flow stream with resilience by reviewing established payers in the 6 dividend fortresses that offer substantial yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com