
3 US Bank Stocks Built For Higher Rates And Cash Management Growth
Rates are moving back into the spotlight, with the New York Fed signalling at least one more hike this year and a higher for longer script that keeps cash yields in focus. That shift can change how money flows between cash-like products and the stock market, creating pockets of opportunity and risk. This piece breaks down three US-listed cash management and money market beneficiaries that appear particularly exposed to the latest Fed signals.
The stocks covered below are just a sample, with the full screen surfacing 24 more US cash management and money market beneficiaries that have similarly detailed business stories but are not covered in this article. To identify and analyze the highest conviction ideas that fit your own risk and income goals, head straight into the US Cash Management and Money Market Beneficiaries screener.
Prosperity Bancshares (PB)
Prosperity Bancshares plugs straight into the screener theme as a regional banking group that lives on deposits, cash-management and money market products, making its earnings power closely tied to how effectively it turns idle client balances into interest income.
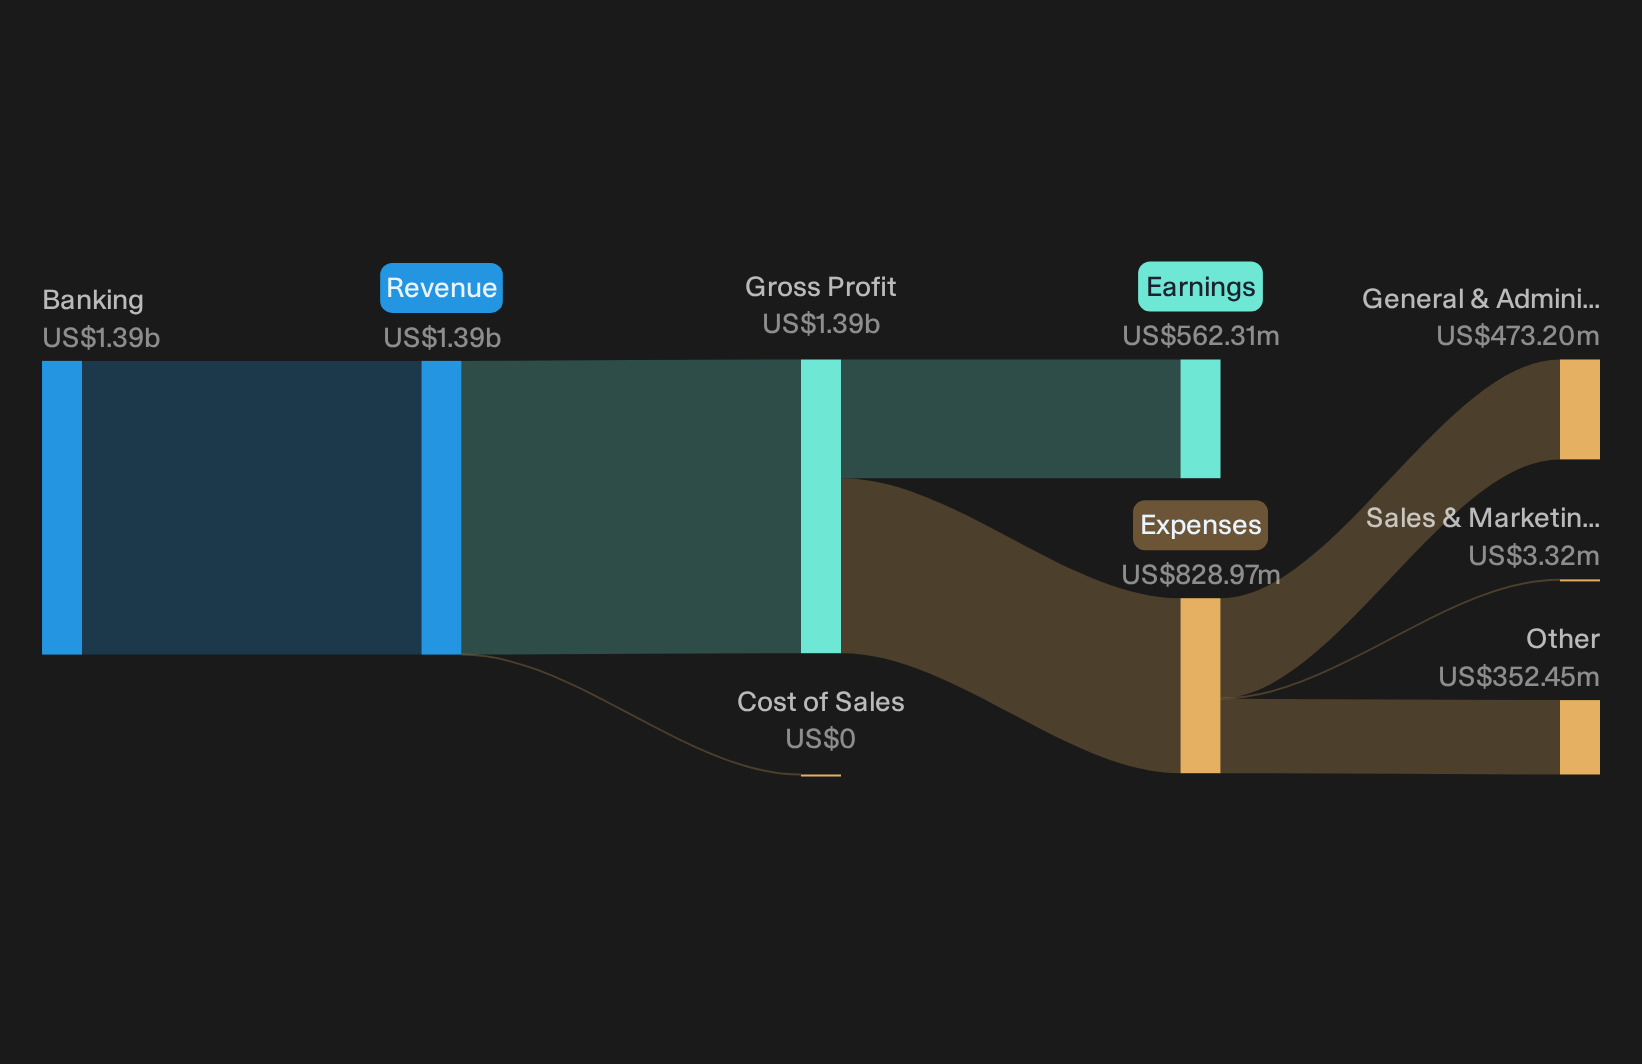
Prosperity Bancshares generates all its US$1.39b of revenue from banking activities in the United States and has a market value of about US$8.1b.
"Completion of the American Bank, Texas Partners and Stellar transactions positions Prosperity Bancshares to consolidate a larger Texas and Oklahoma footprint. Management points to about US$100 to US$110 million of annual pretax cost savings that would directly support a lower efficiency ratio and higher net earnings power once integration is complete."
For investors watching cash-management beneficiaries, what happens when one quiet assumption about future funding costs shifts could be decisive for Prosperity Bancshares.
When that funding-cost assumption finally moves, the full picture sits inside the full narrative for Prosperity Bancshares, including where integration gains could accelerate or where funding pressures might still bite.
Pinnacle Financial Partners (PNFP)
Pinnacle Financial Partners taps directly into the cash management theme because so much of its franchise is built around deposit funding, treasury services and money market accounts, which puts short term rates at the center of how its balance sheet earns a return.
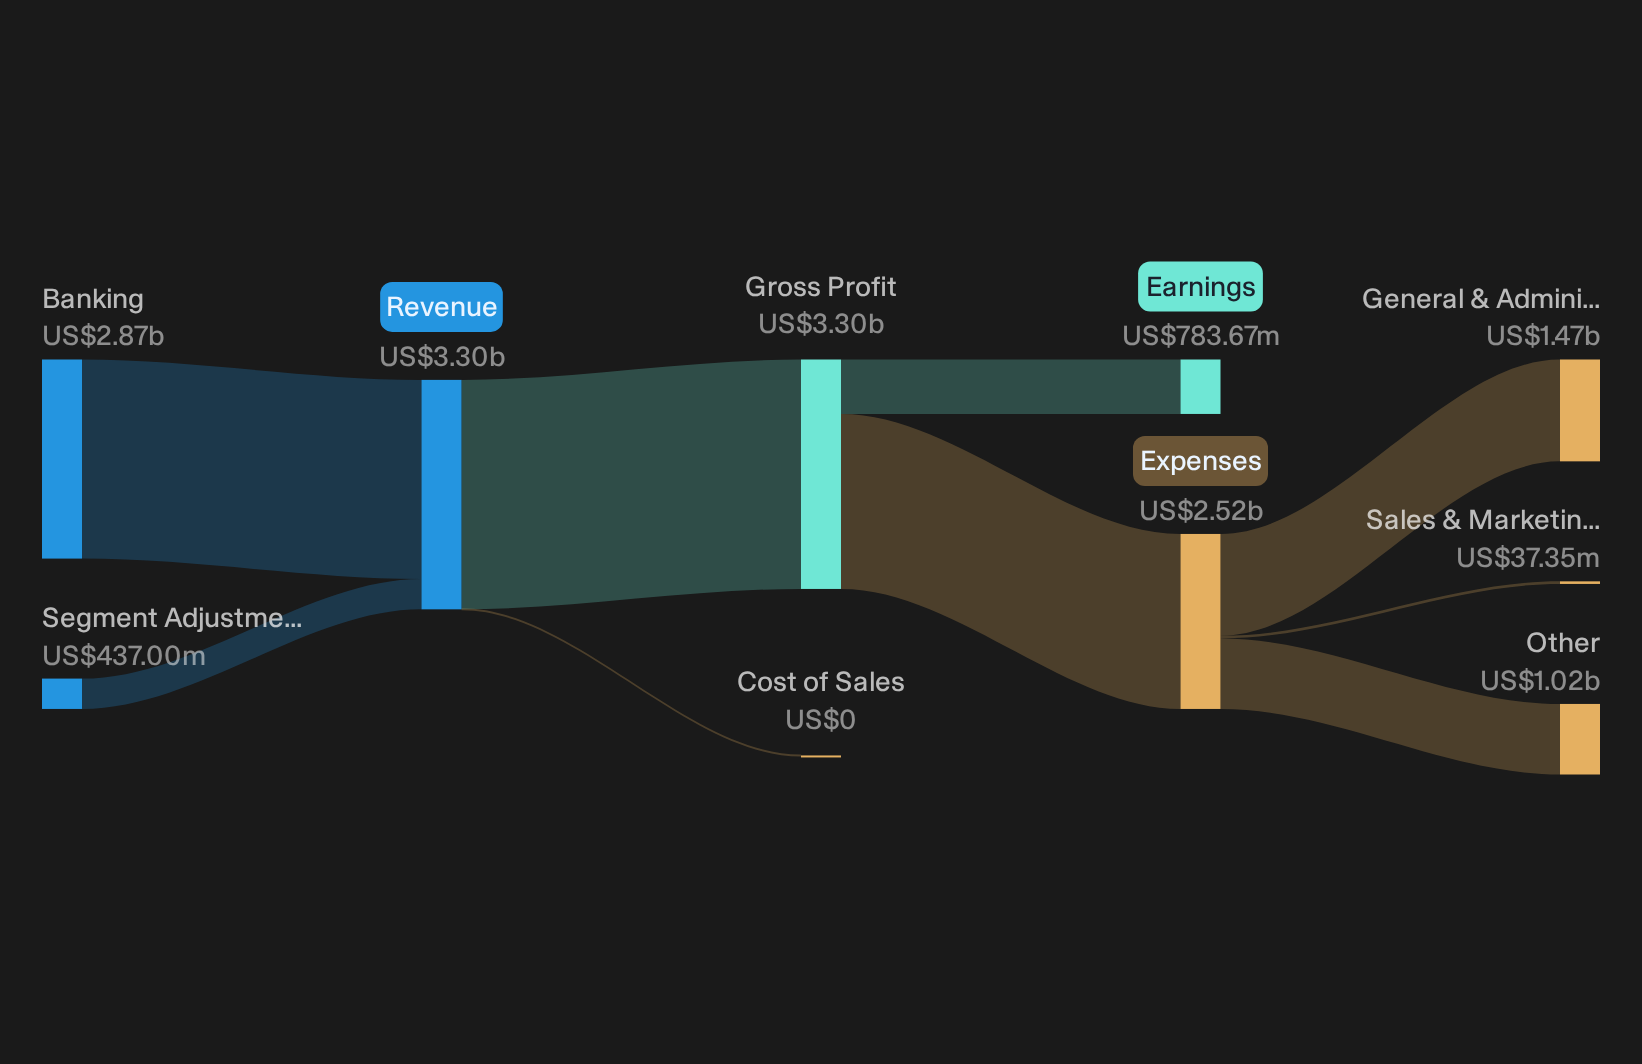
Pinnacle Financial Partners generates about US$2.9b from banking operations and segment adjustments, all in the United States, and carries a market value of roughly US$14.1b.
"Ongoing hiring of experienced revenue producers, including 124 added year-to-date 2026 and a full-year target of 225 to 250, together with banker retention of around 94%, can extend above-peer balance sheet growth and support future earnings."
A key risk is what happens if a single assumption about how quickly funding costs shift against those higher yielding cash balances turns out to be wrong.
That funding swing is exactly what the full narrative for Pinnacle Financial Partners unpacks, revealing where Pinnacle Financial Partners could still accelerate earnings power if deposit behavior and hiring momentum decouple from peers.
Fifth Third Bancorp (FITB)
Fifth Third Bancorp focuses on cash management through a broad US banking franchise that turns everyday deposits and payments activity into interest income and fees, making its approach to low cost balances especially relevant as short term rates remain elevated.
"Growth in payments and deposit rich platforms such as Direct Express and Newline, which together contribute several billions of dollars of low cost deposits and rising fee revenue, gives Fifth Third Bancorp additional levers to support net interest income and noninterest income over time."
What happens if a single assumption about how fiercely deposit pricing competition heats up proves too optimistic for Fifth Third Bancorp?
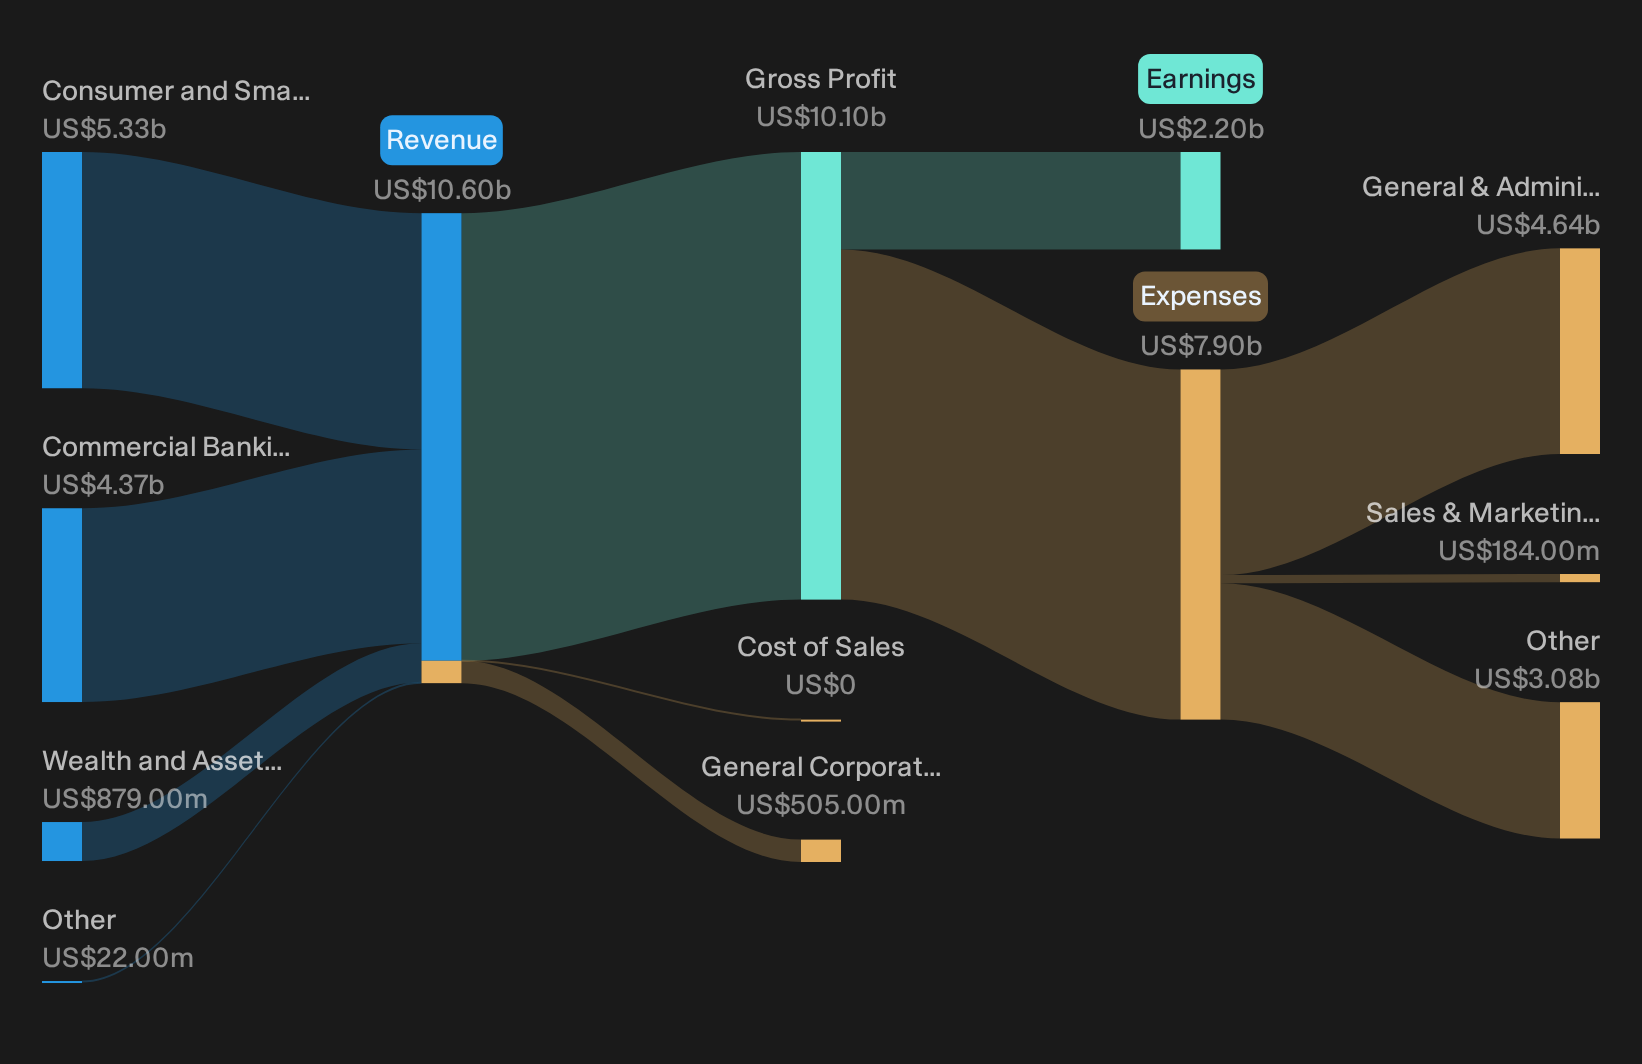
Fifth Third Bancorp is a US$46.8b bank holding group that earns about US$5.3b from Consumer and Small Business Banking, US$4.4b from Commercial Banking and US$879m from Wealth and Asset Management, with all US$10.1b of revenue generated in the United States.
If that deposit slugfest is what worries you, the full narrative for Fifth Third Bancorp shows where Fifth Third Bancorp’s cash engines could still be quietly accelerating.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now and data edges decay fast. Consider acting promptly to avoid missing potential opportunities.
- Explore resilient cash generators before they attract wider attention by scanning a curated list of solid balance sheet and fundamentals (25 results) that keeps you focused on balance sheet strength while it remains a key consideration.
- Gain exposure to structural income themes by examining curated high yield payers through the 6 dividend fortresses before their momentum draws in a broader set of income-focused investors.
- Prepare for potential AI infrastructure developments by tracking hand picked enablers using the 88 AI infrastructure stocks while these operators may still be less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com