
Will EquipmentShare Fleet Deal Change Cummins Stock Narrative
- EquipmentShare.com Inc. announced a multi year fleet agreement with Cummins Inc., committing to build out up to 1 gigawatt of natural gas generation capacity across the U.S. using Cummins units such as the C1400N6C.
- The partnership effectively turns EquipmentShare into a rental and distribution channel for Cummins power products, tying Cummins more closely to temporary power, microgrid, and battery storage demand for mission critical infrastructure that seeks cleaner and potentially lower cost alternatives to traditional mobile power.
- We will now look at how Cummins' multi year natural gas power deal with EquipmentShare could shape its broader investment narrative.
Scan beyond Cummins and explore other power and infrastructure players that may be preparing for similar demand shifts with our hand picked 39 power grid technology and infrastructure stocks
Cummins Investment Narrative Recap
Cummins appeals to shareholders who think its engine heritage, power systems reach, and Accelera bets on cleaner tech can all work together. The main idea is that power generation, data center demand, and energy transition projects can help balance truck cycles. This EquipmentShare deal supports that narrative by deepening exposure to distributed power, without changing the core thesis.
In the short term, the key swing factor still appears to be how weak North American heavy and medium duty truck demand affects engine and component margins. The largest risk remains regulatory and tariff uncertainty and the cost of meeting future rules such as EPA27. The new agreement does not remove those issues, but it broadens where Cummins earns money.
The multi year EquipmentShare agreement is closely tied to Cummins power systems catalyst. Analysts already highlight strong interest in power generation equipment, a sizable backlog, and capacity expansions expected to matter from 2026. This fleet buildout to up to 1 gigawatt of natural gas units falls within that same demand channel and connects Cummins more deeply to temporary and microgrid projects.
For you as an investor, the operational question is execution. Cummins needs to deliver C1400N6C and related units at scale while still funding Accelera and managing weaker truck cycles, all under uncertain regulation and tariffs. If the firm maintains high quality earnings and its 20.3% return on equity while doing that, the power systems narrative remains an important earnings driver.
Cummins' current narrative projects US$44.2b in revenue and US$5.3b in earnings by 2029. This is based on analyst estimates of 9.3% yearly revenue growth and an earnings increase of about US$2.6b from earnings today of US$2.7b.
Uncover why Cummins' fair value indicates a 44% potential upside to its current price that could narrow quickly.
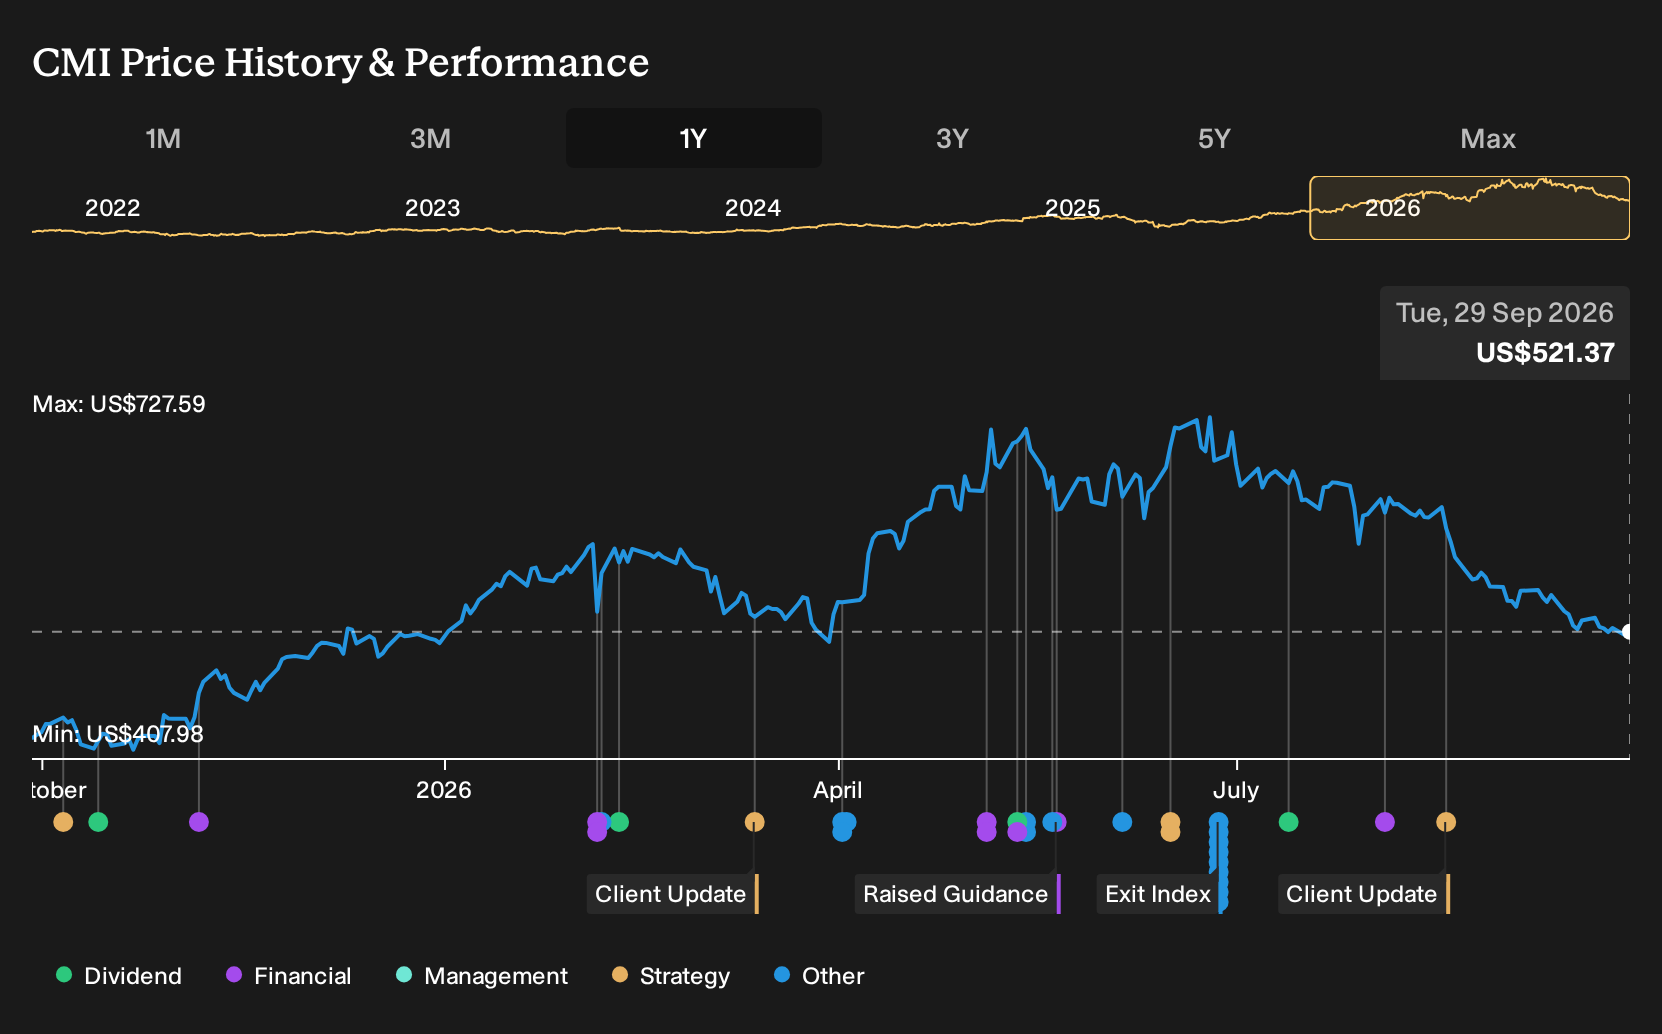
Exploring Other Perspectives
Some of the most optimistic analysts focus on Cummins’ zero emission push instead of truck softness. They were already modeling revenue climbing to about US$49.7b and earnings near US$6.2b by 2029. This new EquipmentShare deal could nudge those expectations again, which is why you may want to compare several viewpoints.
Explore 3 other Cummins fair value estimates, including one that suggests as much as 73% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cummins research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cummins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cummins' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cummins?
If the Cummins story has sharpened your thinking about power, infrastructure, and earnings quality, it may be time to widen the net and see what else fits your criteria using the Simply Wall St Screener.
- If you want businesses trading below what their fundamentals might justify, start with a focused set of 31 high quality undervalued stocks that already score well on quality.
- For investors who care about income strength and consistency, scan a handpicked group of 6 dividend fortresses that pair higher yields with robust profiles.
- If capital preservation matters most to you right now, narrow your watchlist to a curated pool of 32 resilient stocks with low risk scores that screen well on resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com