
Vusion Stock In Focus After Return To Profitability
- Vusion reported half year 2026 results with sales of €819.8 million compared with €614.1 million a year earlier and net income of €131.7 million after a prior loss of €9.7 million.
- The swing from loss to profit signals that Vusion’s commercial digitalization offering is gaining traction, which may ease prior concerns about execution and demand across its key retail clients.
- Investors may now assess how this move to profitability shapes Vusion’s investment narrative, particularly in light of the stronger half year net income.
Scan how Vusion’s move into the black compares with other potential breakout stories by reviewing our hand picked 620 high quality undiscovered gems across the market.
Vusion Investment Narrative Recap
To own Vusion, you need to believe its digital retail platform can continue winning large rollouts and cross sell higher margin services such as VusionCloud, data tools, and media. The move to a €131.7 million profit on €819.8 million in half year sales points to operating leverage and may keep the Walmart backed growth story front and center as a short term catalyst.
The flip side is execution and concentration risk. A lot still rests on big contracts such as Walmart and on fresh demand as earlier European projects complete. Forecasts of declining earnings over the next three years highlight how quickly sentiment could turn if orders slow or product adoption such as EdgeSense stalls.
Among all the noise, the clearest recent data point is the half year 2026 earnings announcement itself. Vusion reported €819.8 million in sales and €131.7 million in net income, compared with €614.1 million in sales and a €9.7 million loss a year earlier. That swing is what now sits behind the “became profitable this year” label in many screeners.
This step into the black feeds directly into the main catalysts investors often watch. Higher quality earnings and strong P/E and discount metrics give management more room to invest in R&D, win new retail verticals, and support U.S. manufacturing moves. At the same time, the volatility in the share price and analyst expectations for earnings to decline keep execution and contract concentration as central risks to track quarter by quarter.
Vusion's analyst narrative points to forecast revenues of €1.8b and earnings of €195.0 million by 2029, based on revenue growth assumptions of 6.6% per year and an increase in earnings of about €51.7 million from €143.3 million today.
Uncover how Vusion's fair value indicates a 61% potential upside to its current price that may not last much longer.
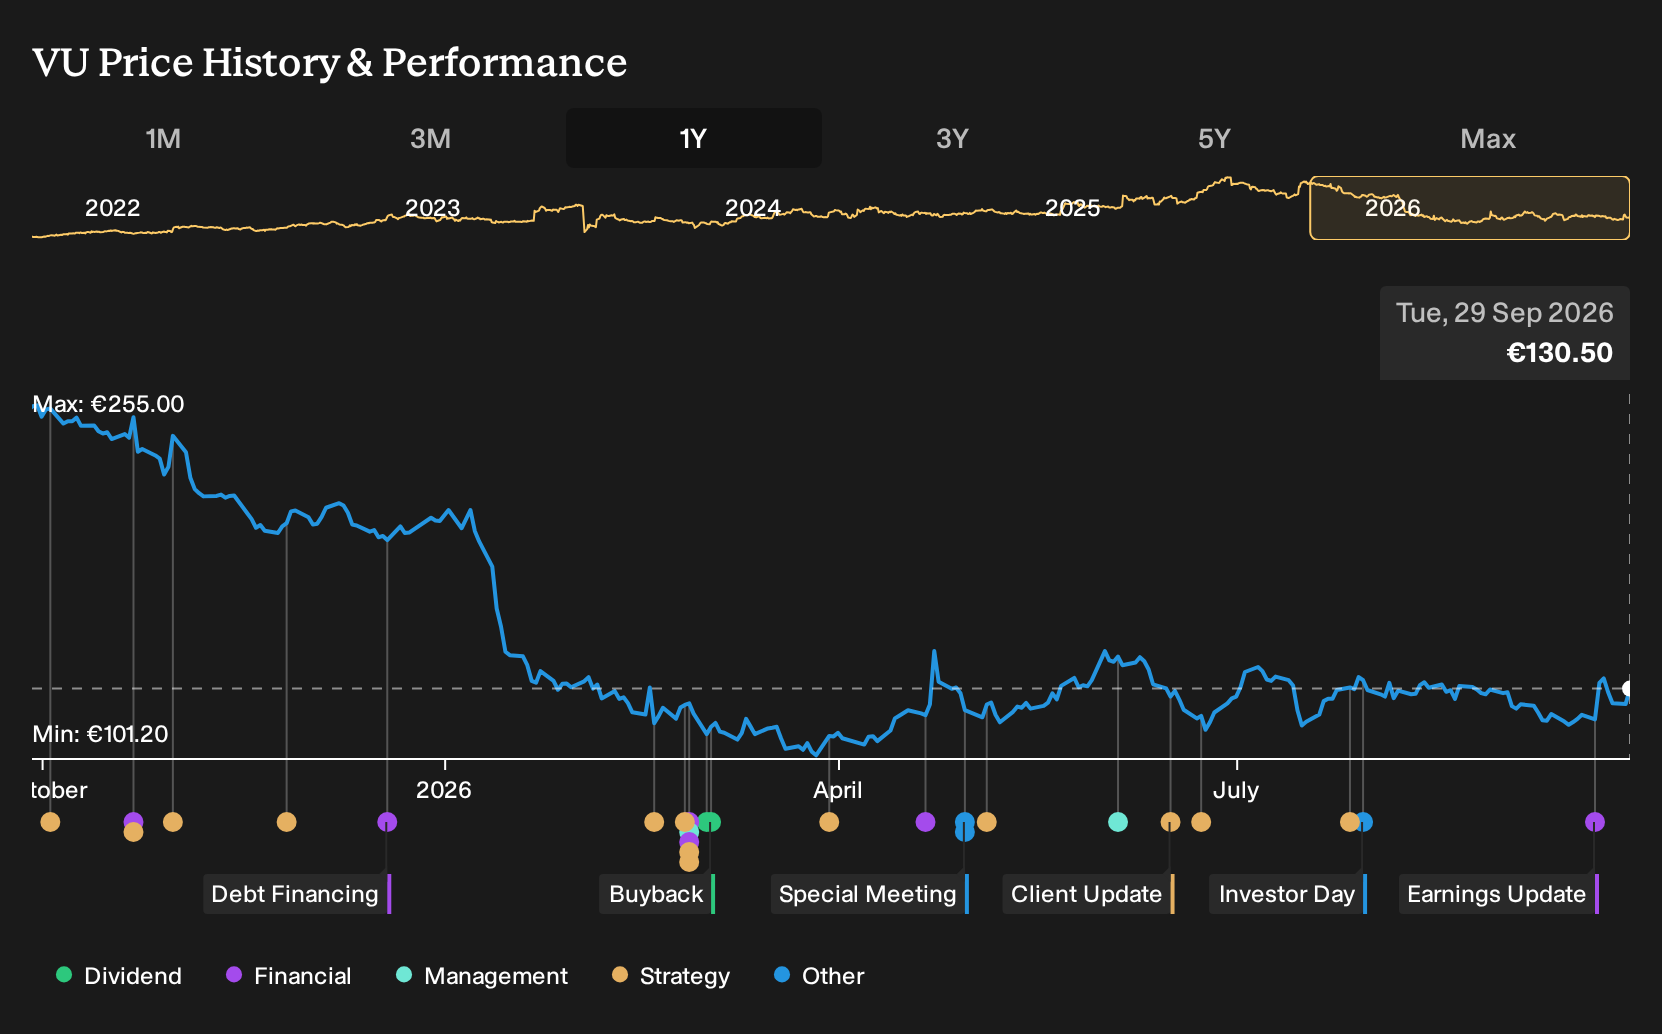
Exploring Other Perspectives
For Vusion, the real point of tension is earnings power once Walmart’s EdgeSense rollout cools. The most pessimistic analysts were penciling in revenue of about €1.7b and earnings sliding toward €135.0 million by 2029. That is far below consensus, and this fresh profit print may eventually push those views to shift.
Explore 3 other Vusion fair value estimates, including one that suggests as much as 27% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vusion research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vusion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vusion's overall financial health at a glance.
Looking for more investment ideas beyond Vusion?
Once you have a view on Vusion, it can help to widen the lens and compare it with other opportunities that match different goals such as value, resilience, or income.
- If you are hunting for quality at a discount, scan a curated 198 high quality undervalued stocks that combine strong fundamentals with prices that still look restrained.
- If capital preservation ranks high on your checklist, review a 226 resilient stocks with low risk scores that score well on balance sheet strength and risk factors.
- If steady cash returns appeal to you, focus on a 162 dividend fortresses that offer yields above 5% while aiming to keep payouts supported by underlying earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com