
Block (XYZ) Following Apple Business Integration Has Valuation Back In Focus
Block (XYZ) is back in focus after Square rolled out an Apple Business integration that lets merchants manage Apple Maps and related Apple apps directly from the Square Dashboard.
Recent moves in Block’s share price tell a mixed story. The stock has a 30 day share price return of down 11.39% and a 7 day share price return of down 4.49%. Yet year to date the share price is up 13.66% and the 3 year total shareholder return is very large at about 7x. This signals longer term momentum even as the latest pullback suggests investors are reassessing how new partnerships like the Apple Business integration and customer expansions such as Ideal Nutrition’s rollout translate into future demand and risk.
Spot opportunities tied to this kind of payments and AI-driven commerce shift by scanning our hand picked list of 88 AI infrastructure stocks.Block is caught between a sharp recent pullback and a still strong multiyear return profile. Does that mix justify stepping in around US$74 today, or does patience on a better entry make more sense once you see the valuation math next?
Most Popular Narrative: 24% Undervalued
Block’s most followed narrative pins fair value at $97.60, which sits well above the last close at $74.05 and presents the recent pullback as part of a longer earnings and product story that points to higher future profitability.
The rapid acceleration in new product launches, especially around peer-to-peer features (like Cash App Pools) and the integration of AI into product development, is increasing Cash App's network effects and virality. This is likely driving improved user acquisition and engagement and supports recurring revenue expansion in future quarters.
Continued expansion of embedded banking and lending products (Borrow and BNPL) within Cash App, supported by proprietary credit scoring and increasing eligibility and limits, is opening new user cohorts and higher-ARPU segments. This underpins sustained revenue growth and strengthens long-term net margins through higher-margin banking activity.
See why 189 investors see Block as 24% undervalued.
Result: Fair Value of $97.60 (UNDERVALUED)
Still, the story can break if Cash App engagement cools as competition tightens, or if Bitcoin and BNPL related credit losses hit Block’s earnings power.
Find out about the key risks to this Block narrative.
Another View On Block’s Valuation
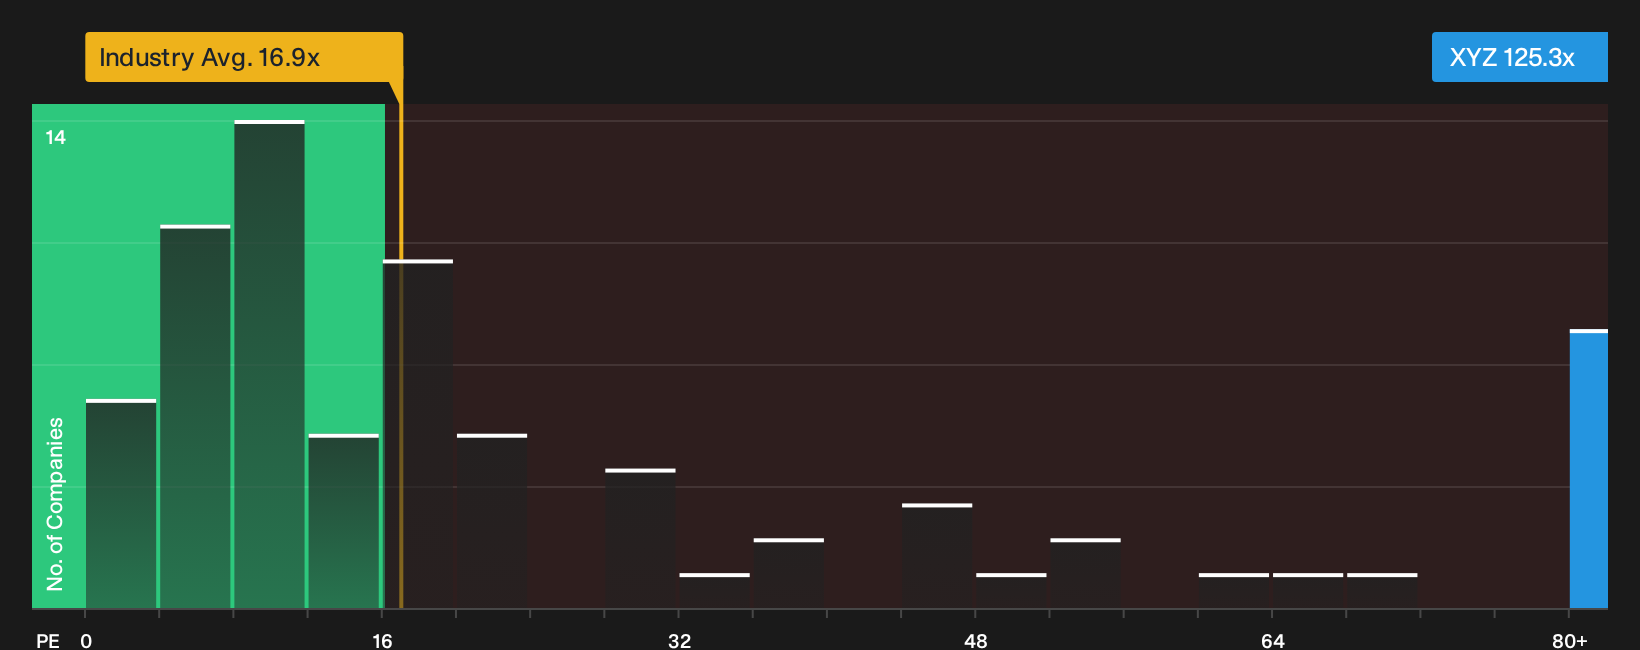
Analysts see upside for Block, with the $74.05 share price sitting well below a $98.36 consensus target and an estimated fair value of $97.60. Yet the current P/E of 125.3x is far above the 16.6x industry average and a 35.7x fair ratio, which raises questions about how much optimism is already reflected in the price.
This kind of gap can matter for you because rich multiples often compress if growth or margins fall short of expectations. The core issue is whether Block’s earnings path and risk profile justify paying a valuation that is so much higher than both peers and that fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Block can be useful if you move quickly and assess the trade-off yourself using the underlying numbers, risks and rewards. To see both sides clearly, review our snapshot of 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Block?
Block’s story is only one angle. Use the same data driven tools to spot other opportunities that fit your risk tolerance and income goals before they run away from you.
- Target potential mispricing by scanning a curated mix of quality businesses trading below estimated value through the 32 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for companies with robust finances in the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities by using the 17 high quality undiscovered gems that many investors may still be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com