
Our Pick Of The Best Japanese Insider Owned Growth Stocks In September 2026
Australian interest rates sit at a 15-year high, so easy money is gone and funding costs matter again. That puts a spotlight on Japanese businesses where insiders already own a large slice of the equity and expectations for future expansion are optimistic. This article breaks down three fast growing Japanese stocks with high insider ownership to highlight where committed management teams are backing that growth outlook with their own capital.
The three companies below are just a sample, with the wider screen surfacing 102 more high growth businesses where insiders already hold meaningful stakes and analysts have optimistic outlooks that are not covered in this article. To cast a wider net and quickly identify, analyze, and rate your own highest conviction ideas, head straight into the Fast Growing Stocks With High Insider Ownership screener.
Round One (TSE:4680)
Round One runs large indoor leisure complexes that bundle bowling, arcade games, karaoke, billiards, and Spo-Cha sports zones, giving it a clear tie to the leisure theme. The group is valued at about ¥321.4b.
Round One lines up neatly with the screener idea. Earnings have grown around 35.7% a year over five years, and the stock trades on a P/E below the industry average. Everything now hinges on how each new complex replicates the returns of the existing locations if a single key assumption breaks.
If that assumption feels brittle, dig into the DCF valuation analysis for Round One to see how sensitive Round One’s appeal is to the economics of each new site.
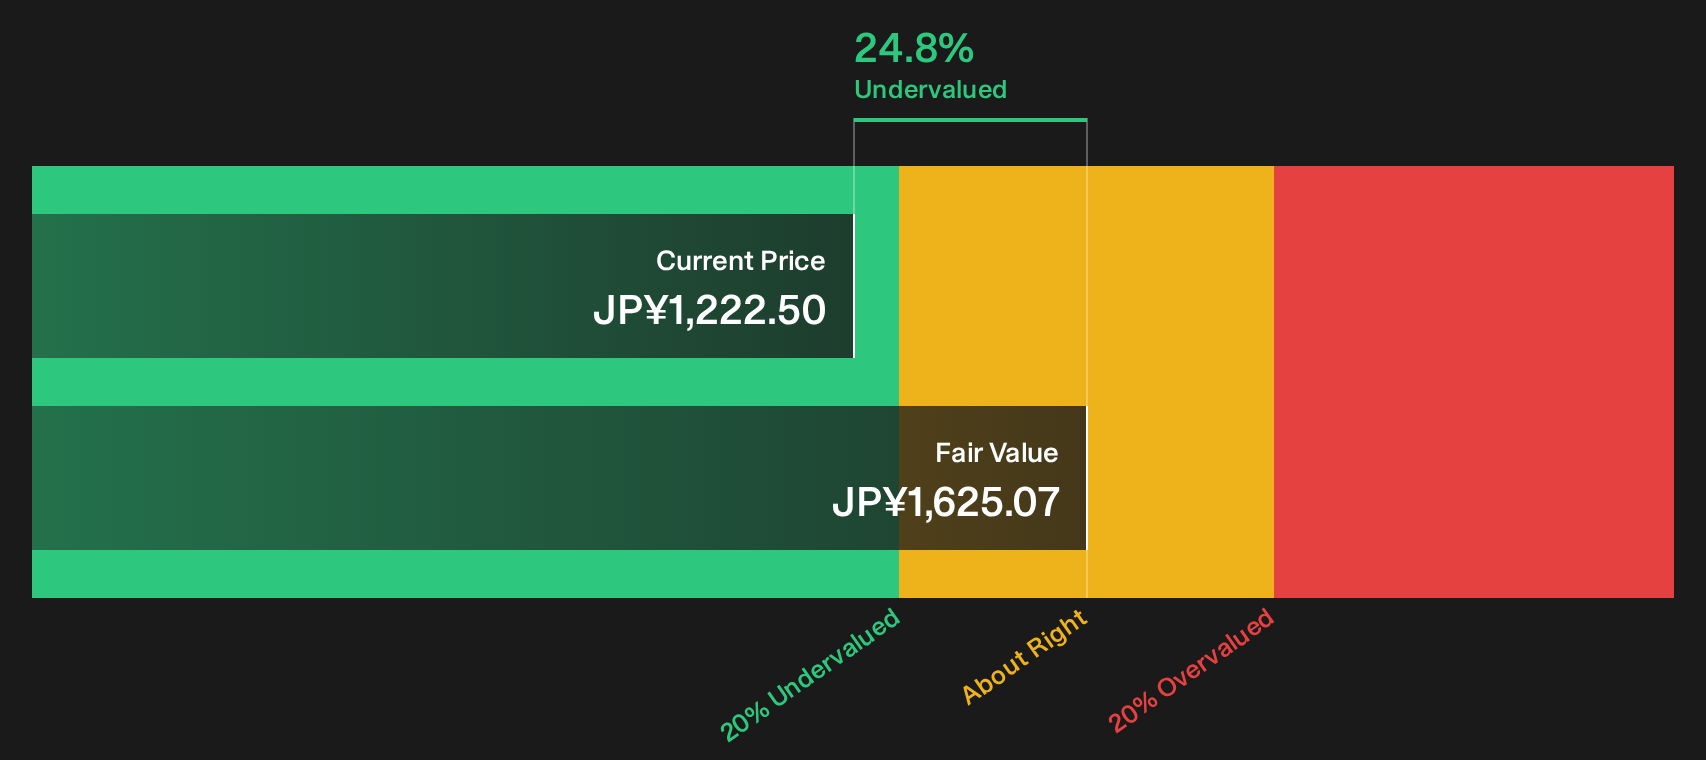
Micronics Japan (TSE:6871)
Micronics Japan develops body measuring systems and inspection gear but is primarily tied to semiconductor demand through its probe cards, wafer probers and test sockets. The probe card segment generates about ¥84.9b of revenue versus ¥1.4b for TE, and the group is valued around ¥535.4b.
Earnings are forecast to grow about 24.9% a year, with revenue guided to ¥103.8b and operating profit to ¥31.4b for 2026 as probe card demand linked to AI memory chips builds. That momentum will depend on how pressure in the memory cycle affects pricing and margins.
That pricing power question sits right at the edge of Micronics Japan’s appeal, so tap into the 2 key rewards and 1 important major warning sign to see what the market might be missing.

Rakuten Group (TSE:4755)
Rakuten Group runs a broad digital ecosystem that spans online shopping, streaming, telecoms and a fast growing FinTech arm built around its card, banking, brokerage and payments products. Internet Services generated ¥1,395.4b, FinTech ¥1,090.4b, Mobile ¥512.6b and the group was valued at about ¥1.48t.
Rakuten Group taps the screener theme through its FinTech engine, where cards, banking and payments are tightly integrated into a wider e-commerce and mobile network, and management is leaning into that growth path with capital and product focus.
"Rakuten Mobile is achieving rapid growth in subscribers, expected to drive the growth of the entire Rakuten ecosystem, contributing significantly to future revenue increases through cross-selling of Rakuten services to mobile users."
The real test will come if one pressure on profitability shifts faster than the current growth narrative assumes.
If that pressure point matters to you, read the full narrative for Rakuten Group to see how subscriber growth, cross selling, and capital needs are really interacting beneath the surface.

Seeking Alternatives Before Momentum Flies Past
Fresh ideas move fast. Breakout themes gain momentum, weaker stories get caught dropping, and under the radar for now opportunities fade before the crowd reacts. Consider acting before conditions change.
- Scan for resilient compounding potential in companies with strong balance sheets using the curated list of solid balance sheet and fundamentals (22 results) before market attention drives valuations away from your comfort zone.
- Spot early-phase resource momentum by checking the hand picked 36 elite gold producer stocks while producers are still pricing in today’s data instead of tomorrow’s expectations.
- Track real-world automation demand with the focused 93 robotics and automation stocks so you do not miss manufacturers building long term contracts while the headlines lag.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com