
Power Systems Order Could Change The Case For 2G Energy Stock (XTRA:2GB)
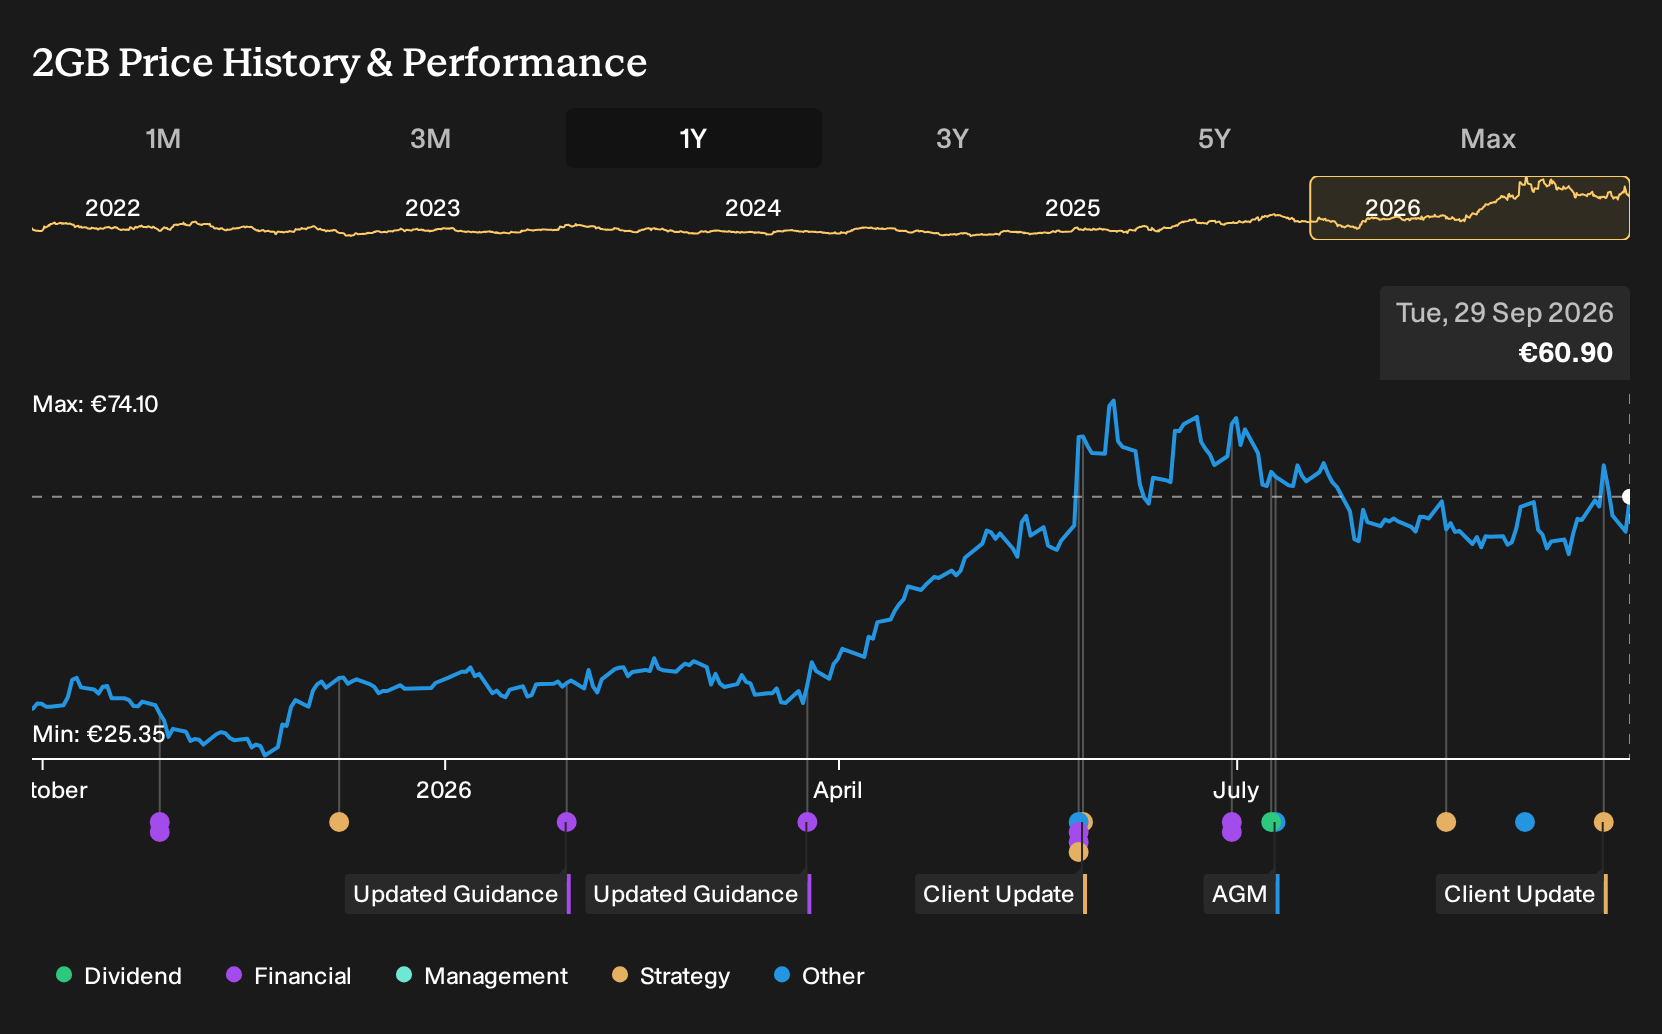
- Energy Vault Holding Inc. announced a 275 MW order from 2G Energy AG for containerized power generation systems in the US, targeting AI and hyperscale data center infrastructure with deliveries planned between late 2027 and late 2028, plus long term service support.
- The project positions 2G Energy inside Energy Vault's integrated power stack as the dispatchable generation layer, tying the manufacturer directly to mission critical AI compute loads that require real time coordination of generation, storage and power quality.
- Next, the focus turns to how 2G Energy's large US AI power order could reshape the broader investment narrative for the business.
Scan beyond 2G Energy's AI data center deal by sizing up hand-picked grid and data infrastructure plays in our 39 power grid technology and infrastructure stocks that are positioned to support similar compute hungry demand.
What Is 2G Energy's Investment Narrative?
The heart of the 2G Energy story is simple. You need to believe this manufacturer can turn its niche in decentralized CHP units into a bigger role supplying reliable on site power for data centers, industry and municipal heating. The €1.1b company already reports €398.6m of revenue and €16.8m of net income. Forecasts that point to revenue growth of 21.1% a year and strong expected earnings expansion only matter if execution stays tight as projects scale.
The 275 MW Energy Vault order fits that belief. It supports the idea that 2G Energy can win large, complex AI power projects and secure long term service work, not just sell hardware. That said, margins are currently thinner than a year ago, P/E at 65.2x screens rich versus peers and non cash earnings are elevated, so a lot rests on this and similar contracts translating into clean cash flow rather than accounting comfort.
Even so, there is a specific pressure point in the story that could matter far more than the headline AI order if ...
There's only one way to know the right time to buy, sell or hold 2G Energy. Head to Simply Wall St's company report for the latest analysis of 2G Energy's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly €72.6 to €105.5, so private investors on that platform already disagree meaningfully on where 2G Energy should trade. Those views were set before the 275 MW Energy Vault contract and the recent conference appearance, so you are seeing starting points rather than finished conclusions.
Explore another 2G Energy fair value estimate, including one that suggests there may be as much as 73% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your 2G Energy research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for 2G Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 2G Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond 2G Energy?
If the 2G Energy story has you thinking more broadly about where to put fresh capital to work, it can help to scan other companies with very different drivers and risk profiles.
- For readers hunting for potential mispricings with quality behind them, start by reviewing our 198 high quality undervalued stocks that pair solid fundamentals with discounted valuations.
- If resilience and balance sheet strength matter most to you, filter for companies in the list of solid balance sheet and fundamentals (204 results) that can better withstand tougher conditions.
- Those looking for ideas that fly under the radar can review our 620 high quality undiscovered gems to spot lesser known businesses with strong underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com