
KLN Logistics Group (SEHK:636), Why Is The Stock Drawing Fresh Attention?
KLN Logistics Group (SEHK:636) has been removed from the FTSE All-World Index, an action that can prompt index-tracking funds to adjust holdings and lead investors to reassess how the logistics stock fits in diversified portfolios.
Recent trading has been mixed for KLN Logistics Group, with a 90-day share price return of 8.20% contrasting with a decline of 17.73% year to date and a 5-year total shareholder return that is down 55.25%. This suggests longer term momentum has been fading, even as short term moves remain relatively resilient around the HK$5.94 level.
Stress test your KLN Logistics Group thesis against a curated 198 high quality undervalued stocks that may be attracting capital as index changes prompt investors to rethink holdings.
Bulls see KLN Logistics Group as a temporary index casualty, while bears see a structurally weaker transporter. Which story fits the price once valuation and fundamentals are laid side by side?
Preferred P/E of 7.5x for KLN Logistics Group: Is it justified?
On simple valuation terms, KLN Logistics Group changes hands at 7.5x earnings, which screens as inexpensive relative to both peers and the wider Asian logistics sector given its recent HK$5.94 close.
The P/E multiple compares the current share price with the company’s earnings per share and is often used as a shorthand for how much investors are willing to pay for each dollar of profit. For a logistics operator with global operations across Hong Kong, Mainland China, EMEA and the Americas, earnings power and its stability tend to matter more than top line alone when investors weigh that ratio.
KLN Logistics Group is flagged as trading at good value on several fronts, with its 7.5x P/E ratio lower than the peer average of 14.7x and below the wider Asian logistics industry average of 14.3x. The estimated fair P/E of 8.9x also sits above the current level, which points to a market valuation that is materially more cautious than the level the fair ratio model suggests could be reasonable if conditions line up with expectations.
Explore the SWS fair ratio for KLN Logistics Group.
Result: Price-to-earnings of 7.5x (UNDERVALUED)
Still, the long term share price decline of 55.25% and removal from the FTSE All-World Index could continue to put pressure on KLN Logistics Group’s valuation story.
Find out about the key risks to this KLN Logistics Group narrative.
Another View on KLN Logistics Group’s Value
The low 7.5x P/E paints KLN Logistics Group as inexpensive, but the SWS DCF model suggests a fair value of about HK$7.05 per share versus the current HK$5.94. That still indicates the stock trades at a discount, so the real question is whether the cash flow assumptions prove too cautious or too generous.
Look into how the SWS DCF model arrives at its fair value.
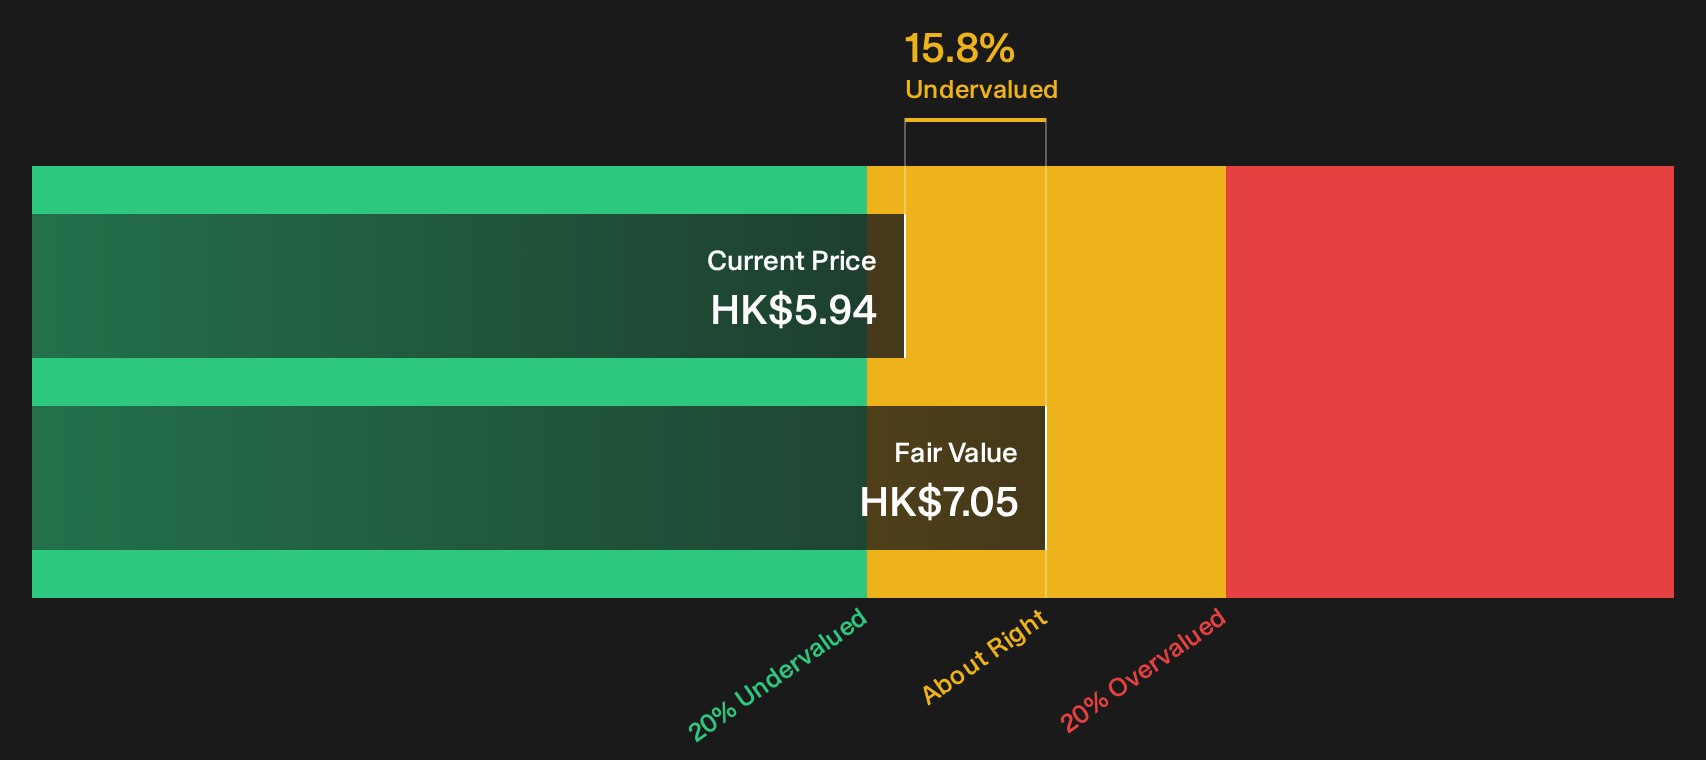
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KLN Logistics Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Uncertain whether KLN Logistics Group is being priced for caution or quiet recovery after the index removal and long term drawdown? Consider acting while sentiment is still split and test the thesis against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond KLN Logistics Group?
Index changes can create openings elsewhere. Do not leave potential ideas on the table while you reassess KLN Logistics Group and refresh your watchlist.
- Target steadier portfolio candidates by reviewing a 226 resilient stocks with low risk scores that focuses on businesses with resilient profiles and lower risk scores.
- Hunt for potential mispricings by scanning a 620 high quality undiscovered gems built around strong fundamentals that the market may not be fully watching yet.
- Strengthen your income plan by checking a 162 dividend fortresses that concentrates on 5%+ yield carriers with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com