
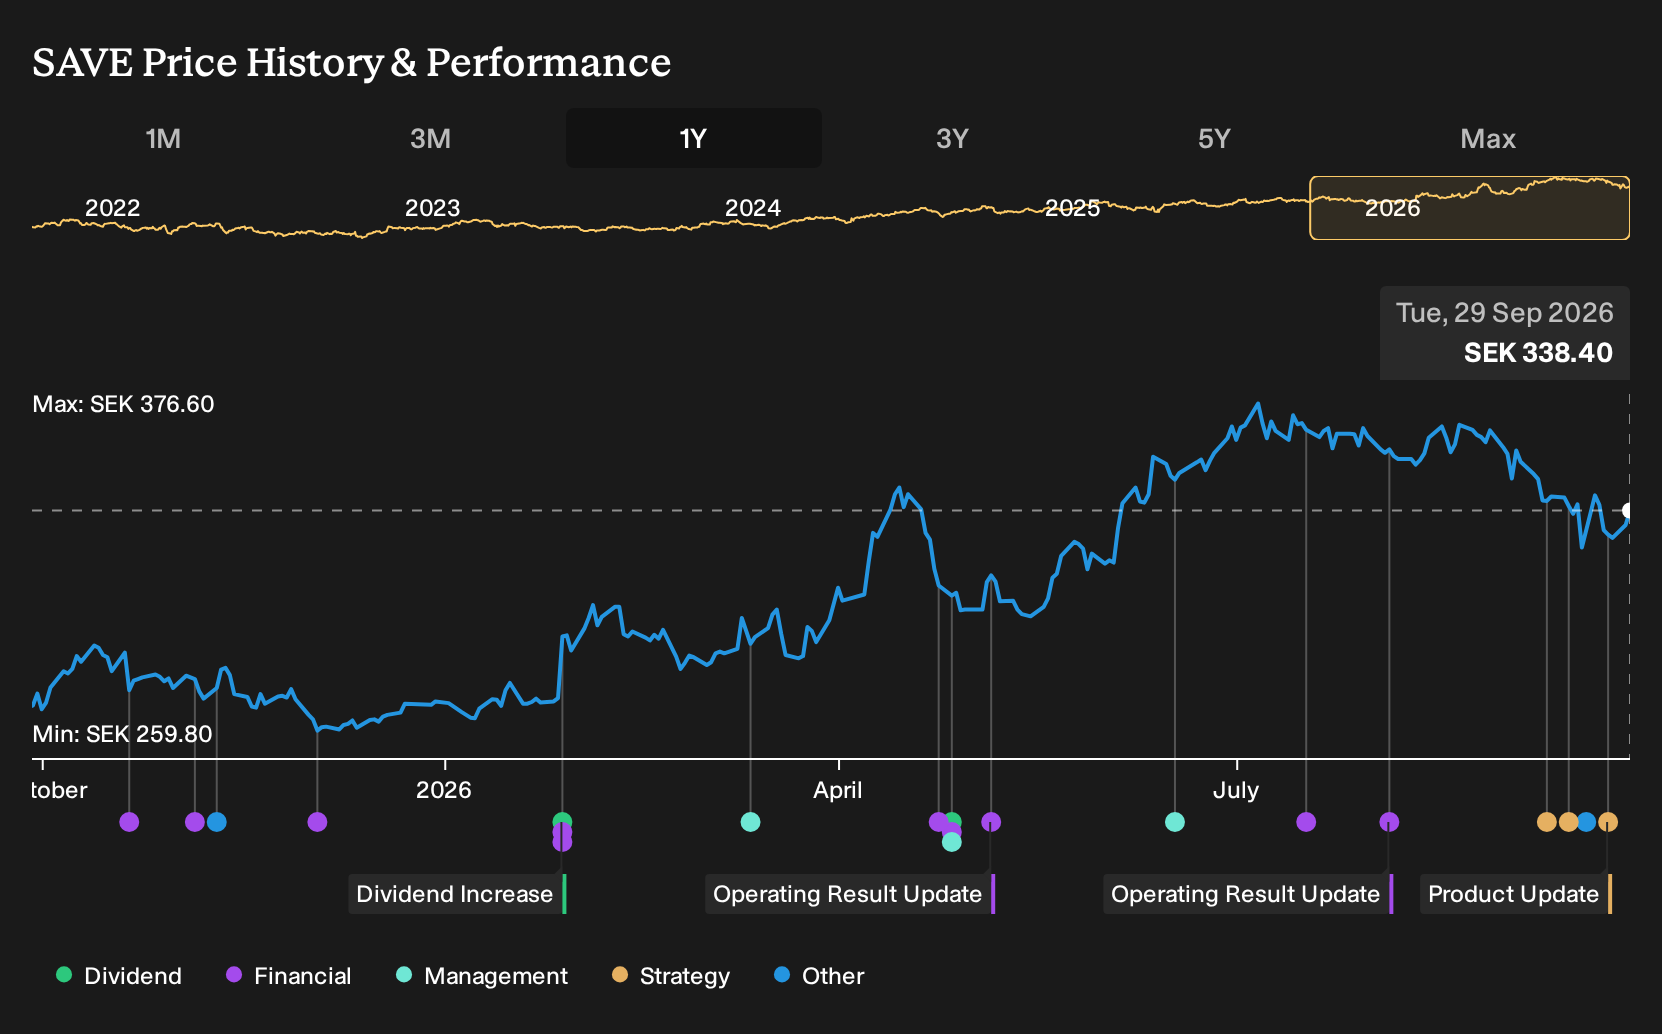
Did Proprietary ETF Launch Just Shift Nordnet's (OM:SAVE) Investment Narrative?
- Nordnet has announced that it will expand its fund business by launching a series of proprietary ETFs, managed by Nordnet Fonder with J.P. Morgan, across Sweden, Norway, Denmark, Finland and the upcoming German market.
- The move into own-label ETFs could reshape Nordnet's product mix, shifting more savings into in-house vehicles and potentially changing how fee and cost structures develop over time.
- We will now look at how Nordnet's investment narrative could be influenced by the planned roll out of proprietary ETFs.
Scan beyond Nordnet and this ETF push by reviewing a hand picked list of cost focused and fundamentally strong asset managers and platforms in our list of solid balance sheet and fundamentals (204 results).
Nordnet Investment Narrative Recap
To own Nordnet, you need to be comfortable with a digital savings platform that leans on growing customer activity, fee income from brokerage and funds, and expansion into new markets like Germany. The proprietary ETF launch fits that story because it could gradually tilt the revenue mix toward more recurring, product based fees rather than purely trading driven income.
The key near term swing factor still looks like the balance between rising costs and revenue progress, especially with ongoing investment in new products and markets. The biggest risk remains margin pressure if fee competition intensifies or trading activity cools, and the ETF rollout alone does not fundamentally change that risk right now.
The ETF launch across the Nordics and Germany is the announcement that connects most directly to Nordnet's current catalysts. It plugs into the existing push to broaden the offering beyond brokerage into funds, pensions and more platform based products, which can deepen customer relationships and potentially support more stable fee pools over time.
For you as a shareholder, the interesting question is how well Nordnet executes the ETF build out while also entering Germany and managing funding and cost pressures. If management can scale these products efficiently and keep pricing discipline in a competitive Nordic market, the ETF move could reinforce the longer term growth narrative without adding disproportionate operational risk.
Nordnet Forecasts Behind the ETF Story
Nordnet's narrative projects SEK 8.2b revenue and SEK 4.8b earnings by 2029. This is based on analysts assuming 7.6% yearly revenue growth and an earnings increase of about SEK 1.4b from SEK 3.4b today.
Uncover why Nordnet's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view sees Nordnet's ETF push through the lens of upside from fund economics rather than cost risk. The most optimistic analysts were already working off SEK 8.5b revenue and SEK 5.2b earnings by 2029, compared with the SEK 8.2b and SEK 4.8b consensus. You can now ask whether this new ETF plan shifts those narratives again.
Explore 2 other Nordnet fair value estimates, including one that suggests up to 11% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Nordnet research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nordnet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordnet's overall financial health at a glance.
Looking for more Nordnet style investment ideas?
If the Nordnet story has sharpened your thinking, use that same lens to scan for other businesses with the balance sheets, income streams and risk profiles that fit your playbook.
- For investors who want potential bargains with quality fundamentals, start with 198 high quality undervalued stocks and see which companies fit your return and risk criteria.
- If capital preservation matters as much as upside, filter for companies with stronger financial footing using the 226 resilient stocks with low risk scores to narrow your watchlist.
- When you want to get ahead of the crowd, focus on underfollowed opportunities backed by solid numbers using the 620 high quality undiscovered gems to spot ideas before they are widely discussed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com