
Sun Life Financial And 2 Canadian Dividend Stocks To Watch
When U.S. Treasury yields reach a 25 year high and cash suddenly looks more tempting, dependable Canadian dividend payers start to feel a lot more important in a portfolio. Investors chasing only growth can end up on a roller coaster. Those who collect steady income from companies with yields above 3% and solid coverage may sleep better. This article breaks down three such dividend stocks that investors may want to examine more closely.
The three stocks below are just a small sample of the income ideas that meet these quality checks, while the full screen surfaced 17 more companies with equally compelling dividend stories that are not covered here. To see the entire field and immediately identify which ones best fit your goals, head into the Dividend Powerhouses (3%+ Yield) screener.
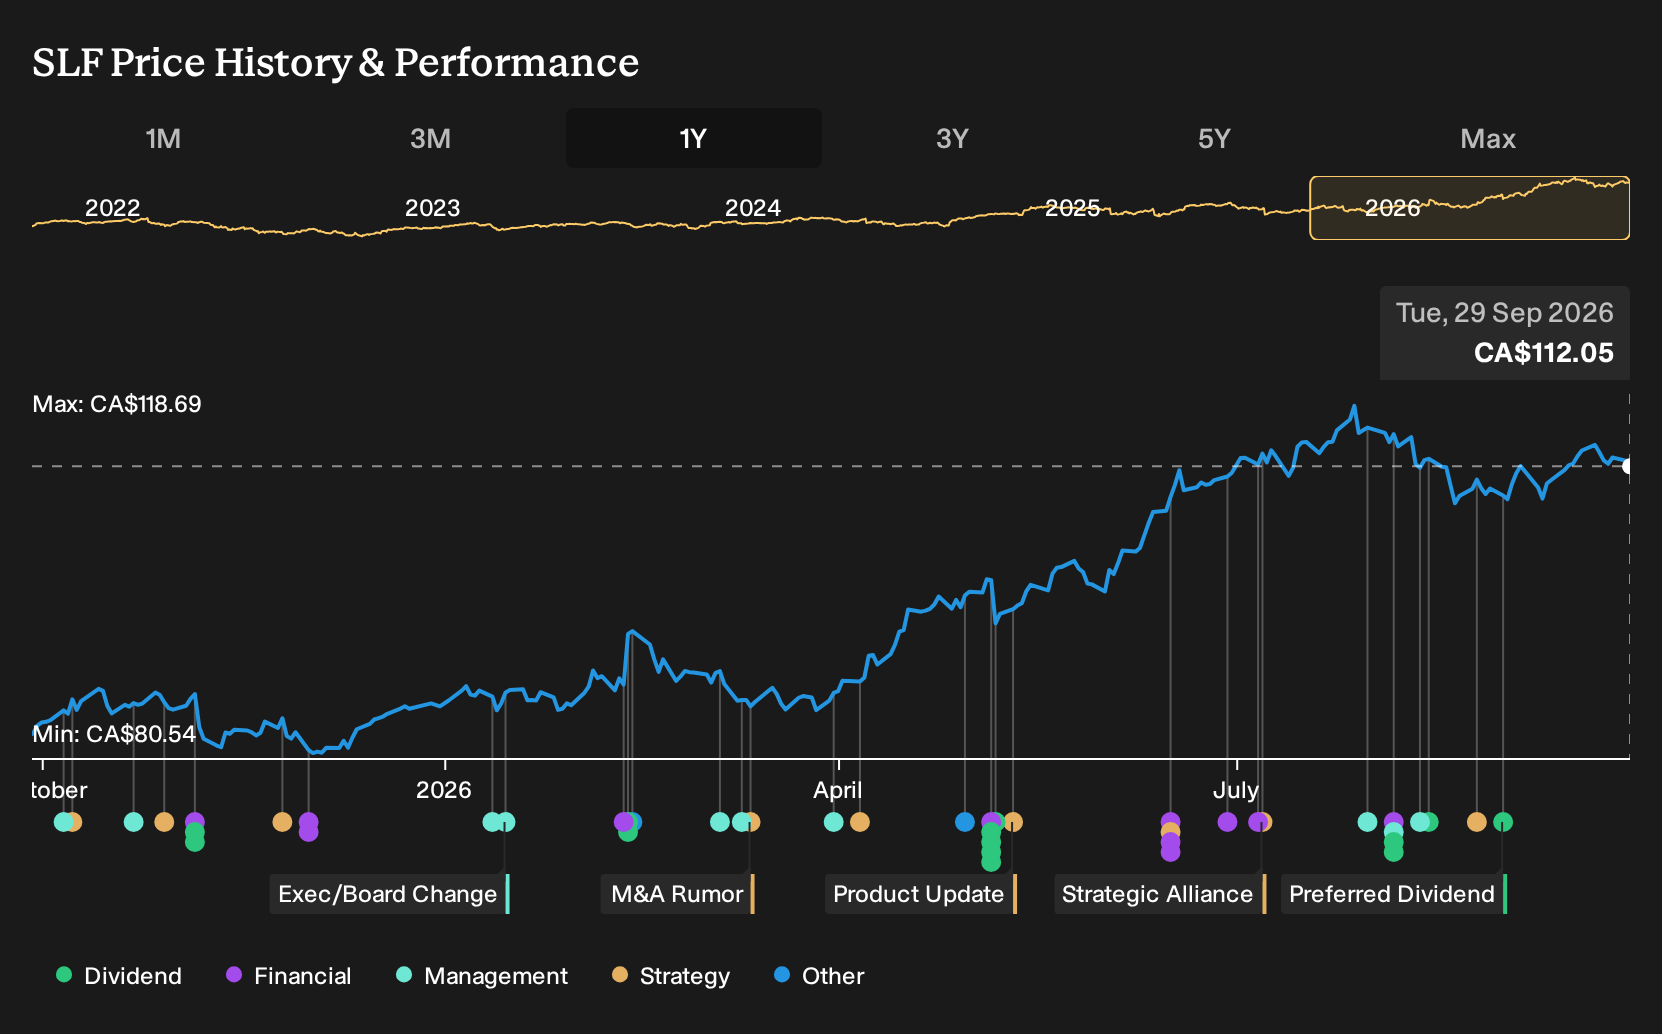
Sun Life Financial (TSX:SLF)
Sun Life Financial is a global insurer and asset manager that fits the Dividend Powerhouses theme by pairing recurring fee income with steady insurance cash flows. This gives it the kind of earnings visibility that can support a well covered, above 3% payout for long term income seekers.
Sun Life Financial runs insurance, wealth, and health businesses across Canada, the U.S., and Asia, with revenue mainly from Canada at about CA$15.7b and its SLAM asset management arm at roughly CA$7.7b. The group is valued at about CA$62.7b.
"Strong growth across Asian markets, particularly in Individual Protection and wealth products, is expanding Sun Life's addressable market and creating significant new revenue sources. This is reinforced by double-digit sales and CSM growth in the region year-over-year."
What ultimately keeps Sun Life’s dividend story interesting is how one unseen pressure on its funding costs could reshape future payout comfort.
To see how that funding pressure, along with Asian expansion, shapes the income story, read the full narrative for Sun Life Financial and see what the headline yield may be masking.
Canadian Tire Corporation (TSX:CTC.A)
Canadian Tire Corporation ties its 3%+ yield appeal to a mix of everyday retail spending, financial services income, and a real estate arm that throws off steady rent from Canadian Tire anchored properties. This structure gives its dividend a more diversified cash source than many pure retailers.
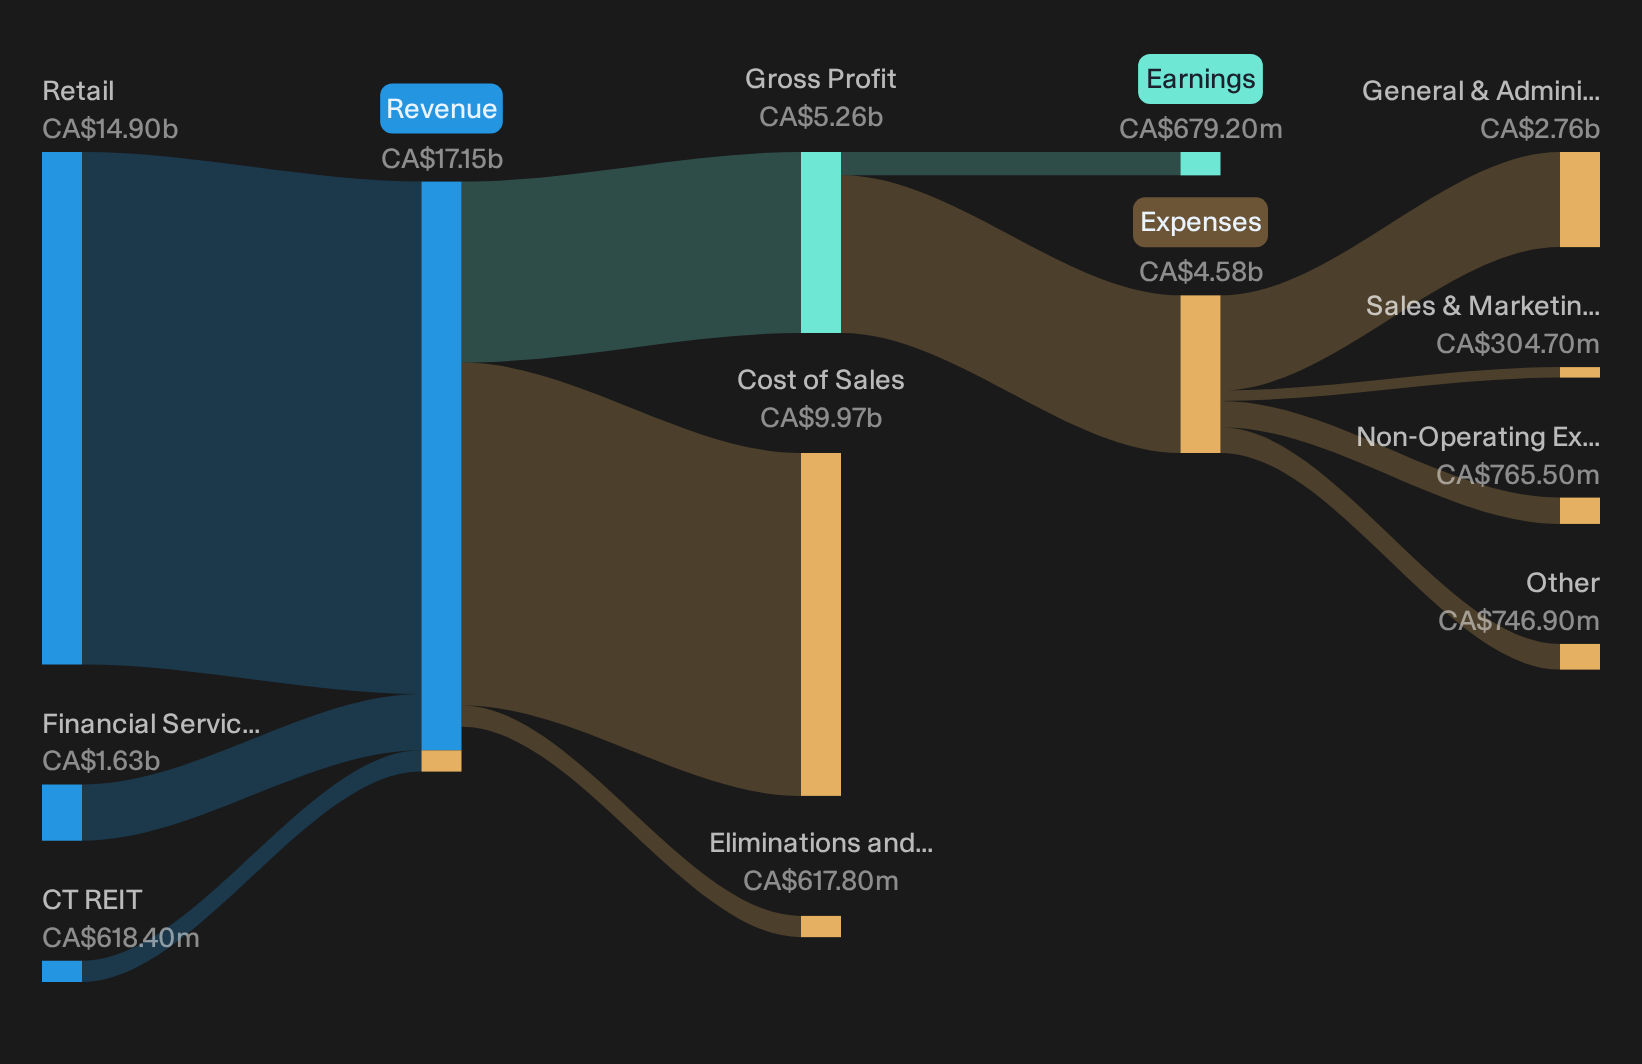
Canadian Tire Corporation runs a broad Canadian retail network supported by credit cards and other financial products, while CT REIT supplies rent from Canadian Tire anchored properties. Retail contributes about CA$14.9b of revenue, Financial Services about CA$1.6b, CT REIT about CA$618m, and the group is valued near CA$10.1b.
For income investors, Canadian Tire Corporation brings together big box retail, a credit card book, and CT REIT’s rental stream, so the dividend story is not tied to a single consumer cycle.
"Ongoing investments in store refreshes, loyalty programs, and supply chain optimization are expected to drive cost efficiencies over time; however, the current and projected increase in fixed and variable costs, combined with wage and utility inflation, could pressure net margins and delay anticipated operating leverage improvements."
The real test for Canadian Tire will come if one key assumption about future spending patterns proves too optimistic for those margin plans.
If that spending picture proves too optimistic, the full narrative for Canadian Tire Corporation explains how Canadian Tire Corporation could still accelerate its income story through underlying cash engines the market may be discounting.
Whitecap Resources (TSX:WCP)
Whitecap Resources is all about turning Western Canadian oil and gas production into dependable cash flow, which is exactly what supports a higher yield that investors in this Dividend Powerhouses screen are looking for and frames the latest operational update.
"Successful integration of Veren assets is resulting in early operational synergies, cost reductions, and improved capital efficiency, which are expected to unlock further sustainable cost savings and margin expansion over the next 6 to 12 months, directly supporting higher future earnings and free cash flow."
What happens if one key assumption about how much of that extra free cash flow actually reaches shareholders turns out to be too optimistic.
Whitecap Resources is a Calgary based producer focused on acquiring and developing oil and gas fields in Western Canada, generating about CA$7.2b in Oil & Gas exploration and production revenue and carrying a market value near CA$21.9b.
If that payout path matters more to you than the headline yield, go straight to the full narrative for Whitecap Resources to see how Whitecap Resources is positioning future cash returns.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first, then everyone chases. Some of the next breakout stories may still be under the radar for now. Spot them before the crowd and act now.
- Scan for resilient balance sheets and steady fundamentals using the curated list of solid balance sheet and fundamentals (7 results) while it still highlights companies the broader market has not fully caught.
- Explore early AI momentum by running through 37 profitable AI stocks that aren't just burning cash, which filters for businesses generating earnings and cash flow instead of burning through capital.
- Look for under followed opportunities through the hand picked 9 high quality undiscovered gems to identify ideas before institutional interest increases and opportunities become more widely recognized.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com